OPEN-SOURCE SCRIPT
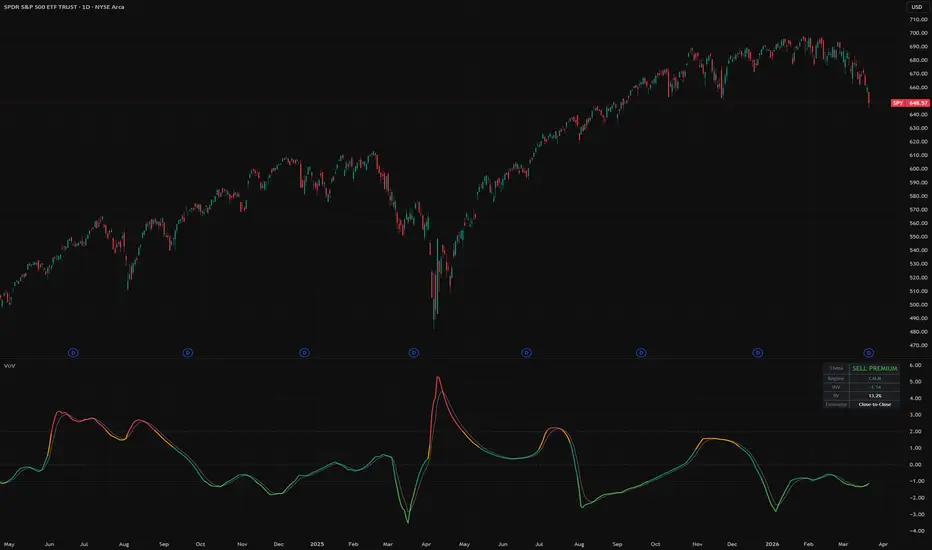
Volatility of Volatility [ThetaLoop]
Here is a thought experiment.
Two stocks both have 25% annualized volatility right now. Stock A has been sitting between 23% and 27% for six months. Stock B was at 12% three weeks ago, spiked to 40%, and just happened to pass through 25% on its way back down.
Would you sell the same put on both? Probably not. But every standard volatility indicator shows the exact same number for both.
This indicator solves that problem. It measures how stable volatility itself is — the second derivative of risk. The CBOE publishes this concept as the VVIX index, but only for the S&P 500. This version works on any stock, ETF, commodity, or crypto pair because it derives everything from price data alone.
The math is straightforward: take rolling realized volatility, then measure the standard deviation of that volatility over a longer window. Normalize as a Z-Score and you get a clean oscillator that answers one question — can I trust my current volatility estimate?
Reading the indicator
CALM regime — Volatility has been stable and predictable. Your realized vol estimate is reliable. This is the ideal environment for selling premium because theta decay behaves as expected and position sizing math works as intended.
NORMAL regime — Some fluctuation in vol, nothing unusual. Standard conditions.
ELEVATED regime — Volatility is jumping around. Your vol estimate might be stale by tomorrow. Consider reducing position size because your risk calculations are built on an unstable foundation.
UNSTABLE regime — Vol is all over the place. Whatever number your broker shows you for IV or HV is probably wrong by the time you submit your order. The premium looks juicy but you cannot reliably estimate what you are actually risking.
Estimator choice
Close-to-Close uses standard log return standard deviation. Simple, widely understood, matches what most platforms report as "historical volatility."
Parkinson uses the daily High-Low range instead. It extracts roughly 5x more information from each bar because it captures intraday movement, not just where the price happened to land at the close. Generally recommended unless you are analyzing something with unreliable intraday data.
Settings overview
RV Window (default 20) — How many days of returns to use for the inner realized volatility calculation. Shorter = more reactive but noisier.
VoV Window (default 60) — How many days of vol readings to analyze for stability. Longer = more reliable regime classification but slower to react.
Display Mode — Z-Score (default, deviation from normal), Percentile (0-100 rank), or Raw (unnormalized coefficient of variation).
Alerts
VoV Unstable — Volatility stability has deteriorated to extreme levels.
VoV Calm — Volatility has become unusually stable. Favorable conditions for systematic premium selling.
Mã nguồn mở
Theo đúng tinh thần TradingView, tác giả của tập lệnh này đã công bố nó dưới dạng mã nguồn mở, để các nhà giao dịch có thể xem xét và xác minh chức năng. Chúc mừng tác giả! Mặc dù bạn có thể sử dụng miễn phí, hãy nhớ rằng việc công bố lại mã phải tuân theo Nội quy.

ThetaLoop | Algorithmic Options Research
🔍 Free CSP Score for any ticker — X-Ray Scanner:
thetaloop.app/xray
(Not financial advice)
🔍 Free CSP Score for any ticker — X-Ray Scanner:
thetaloop.app/xray
(Not financial advice)
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Mã nguồn mở
Theo đúng tinh thần TradingView, tác giả của tập lệnh này đã công bố nó dưới dạng mã nguồn mở, để các nhà giao dịch có thể xem xét và xác minh chức năng. Chúc mừng tác giả! Mặc dù bạn có thể sử dụng miễn phí, hãy nhớ rằng việc công bố lại mã phải tuân theo Nội quy.
ThetaLoop | Algorithmic Options Research
🔍 Free CSP Score for any ticker — X-Ray Scanner:
thetaloop.app/xray
(Not financial advice)
🔍 Free CSP Score for any ticker — X-Ray Scanner:
thetaloop.app/xray
(Not financial advice)
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.