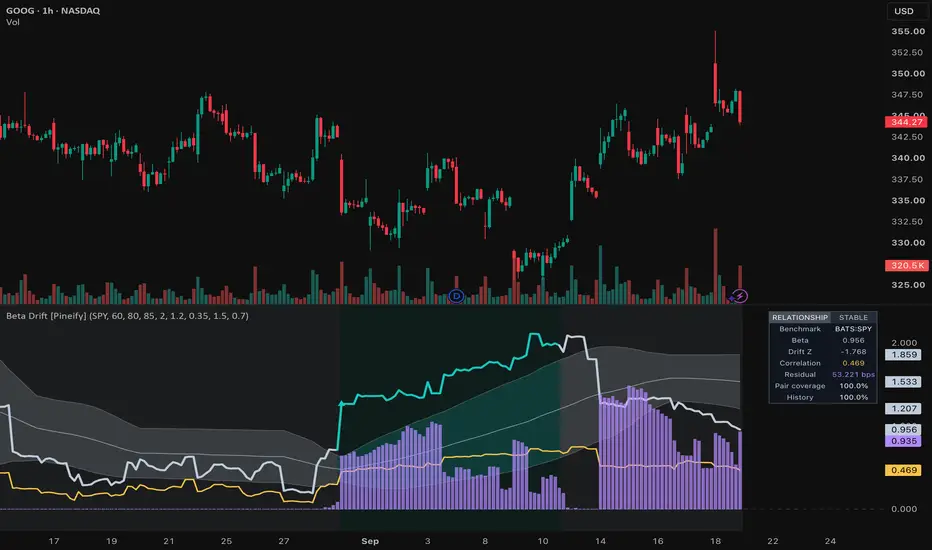
Rolling Beta Drift Monitor [Pineify]Rolling Beta Drift Monitor
Overview
Tracks an asset's changing return relationship with a benchmark through rolling beta, a prior beta corridor, correlation, residual volatility, and confirmed state. It diagnoses exposure rather than predicting returns.
Problem Definition
Beta is a sample estimate, not a stable property. A moving beta can change because of covariance, low benchmark variance, unmatched sessions, or asset-specific noise. Equal betas may have different correlations. The monitor must pair observations, expose coverage, compare beta with its history, and isolate unexplained variation. Otherwise a precise coefficient may describe a fragile relationship.
Design Rationale
Log returns are scale independent. Benchmark returns use the chart timeframe, preserve gaps, disable future access, and count only with a valid asset return. This prevents forward filling but reduces cross-session coverage. Weighted moments expose missing pairs. Current beta is compared with prior estimates, excluding itself. Correlation tests coherence and residual volatility measures unexplained variation. Confirmed states use lower release thresholds to reduce chatter at the cost of delay.
Key Features
Synchronized beta and coverage gate.
Prior-only mean and one-sigma corridor.
Correlation and residual shock.
Five hysteretic states.
Optional dashboard, markers, and alerts.
How It Works
Each bar supplies asset and benchmark log returns for the same timeframe. A weight is one only when both exist. Weighted sums, squares, and cross-products over the relationship window produce means, variances, and covariance. Beta equals covariance divided by benchmark variance. Correlation scales covariance by both standard deviations. Residual variance is what the beta projection leaves; its root is shown in basis points per bar.
Output is withheld below the coverage floor or when variance is effectively zero. A second window uses prior valid beta, correlation, and residual estimates. Beta Drift Z compares current beta with its prior distribution; residual volatility is standardized likewise. At close, extreme drift enters beta-up or beta-down. Weak correlation plus residual shock, or a qualified sign change, enters decoupling. Lower releases add hysteresis. Lines develop live; states and alerts wait for close.
How Multiple Indicators Work Together
One regression supplies every component: moments determine exposure, correlation tests coherence, and residual volatility measures what beta misses. Prior standardization makes change local, coverage requires enough evidence, and hysteresis confirms state. Without correlation, weak fit resembles exposure. Without residuals, specific disturbance is hidden. Without history, drift thresholds are not comparable.
Trading Ideas and Insights
Use the monitor for portfolio and hedge context, not entries. Beta-up with firm correlation means stronger sampled benchmark sensitivity; beta-down means reduced or inverted sensitivity. Decoupling flags that a prior hedge ratio deserves review because correlation changed sign or residual noise rose. On compatible 1H–1W charts, verify coverage and assess events, liquidity, execution, and sizing separately.
Unique Aspects
Typical studies stop at rolling beta or a fixed threshold. Here one synchronized moment set drives a relationship lifecycle. Beta is judged against prior estimates; sign change requires material correlation on both sides; residual shock can reveal weak-correlation decoupling; and coverage gates each stage. Corridor opacity reports evidence quality; state color stays consistent. The contribution is this decomposition and confirmed state model, not the beta formula.
How to Use
Choose a benchmark for the exposure under review and a standard chart with a compatible calendar. Wait for WARMUP to clear. The thick line is beta; the tunnel is prior mean plus or minus one sigma; gold is correlation. Violet columns show capped residual shock; exact values stay in the dashboard and Data Window. Read confirmed transitions only after checking paired and history coverage.
Customization
Relationship Window sets covariance history; Drift Reference sets coefficient history. Minimum Coverage handles session mismatch. Beta Drift Entry controls sensitivity, while Release must be lower for hysteresis. Correlation Floor rejects tiny sign changes. Residual thresholds govern weak-correlation decoupling. Short windows vary faster; long windows retain regimes. Visual switches do not alter calculations or alerts.
Assumptions and Limitations
The method assumes comparable synchronized returns and a useful local one-factor line. Calendars, stale prices, illiquidity, actions, rolls, and benchmark choice alter estimates. Gaps are not filled. Near-zero benchmark variance is blocked, but economic relevance is not proven. Z-scores are empirical, not probabilities; references lag breaks. Residual risk is per bar, not annualized. Live visuals change; states wait for close, while inputs or loaded history can recalculate values. Causality, extra factors, costs, sizing, profitability, and execution are outside scope.
Conclusion
The monitor turns one changing coefficient into a coverage-aware diagnosis. The layers separate coherent repricing from decoupling. Review confirmed changes with independent portfolio and risk analysis.
Chỉ báo