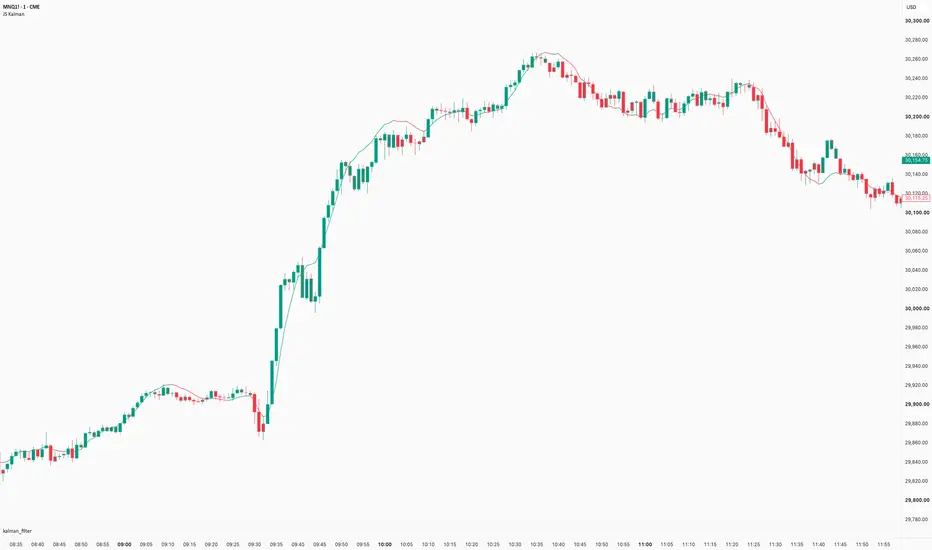
Joint-state Kalman Filter (Linear / Extended / Unscented)Joint-state Kalman Filter (Linear / Extended / Unscented) · JS Kalman
A joint-state price filter — not a typical 1D random-walk smoother. It estimates coupled (and optionally acceleration) in one shared covariance, so trend tracking and reversal behaviour move together.
Filter types
Linear — kinematic Kalman; less lag on trends, can overshoot at sharp reversals (more with C.Accel).
Extended — same layout with velocity damping v' = v × (1 − damping × |v|) ; analytic Jacobian.
U
指标