Smart AVWAPs## Smart AVWAPs
Smart AVWAPs is a multi-anchored VWAP indicator designed for swing traders who want to identify areas where several important volume-weighted price levels converge.
Instead of anchoring VWAPs to every minor swing, the indicator automatically creates AVWAPs from selected high-importance events:
* High relative volume swing highs and lows
* Earnings gaps
* 52-week highs and lows
* Major reversal candles with elevated volume
The indicator keeps the most recent active AVWAPs on the chart, making it easier to visually identify price zones where multiple anchored VWAPs overlap or compress.
### How to Use
AVWAP convergence can highlight areas where participants anchored to different market events have similar volume-weighted cost bases.
For swing trading, these areas can be monitored as potential support, resistance, consolidation, or breakout zones.
A typical workflow is:
1. Look for several AVWAPs converging within a narrow price range.
2. Observe how price behaves around the convergence area.
3. Wait for confirmation such as a strong breakout, reclaim, increased relative volume, or successful retest.
4. Use broader trend, market structure, and risk management before taking a position.
AVWAP convergence itself is not intended to be an automatic buy or sell signal.
### Inputs
**Active AVWAPs**
Controls the maximum number of recent AVWAP anchors displayed.
**Pivot Left / Right**
Controls the sensitivity of swing-high and swing-low detection.
**Minimum RVOL**
Requires a swing or reversal candle to have elevated volume relative to its recent average.
**Earnings Gap %**
Defines the minimum price gap required for an earnings event to create an anchor.
**Reversal ATR**
Controls how large a reversal candle must be relative to ATR before it qualifies as a significant anchor.
### Intended Use
The indicator is primarily designed for daily-chart swing trading, but the settings can be adjusted for other timeframes and trading styles.
It is best used as a visual confluence tool rather than as a standalone trading system.
For research and educational purposes only. This indicator does not provide financial advice or guarantee future mar
指标

策略

指标

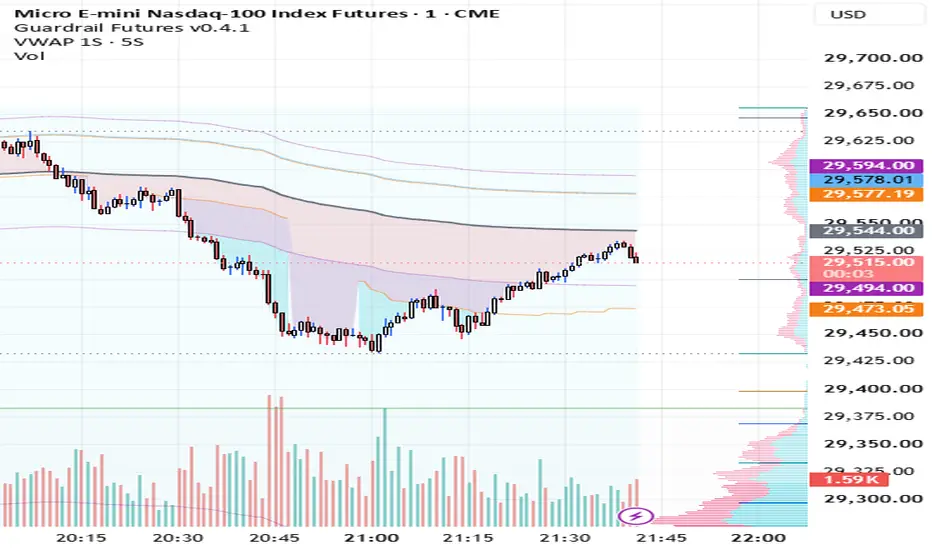
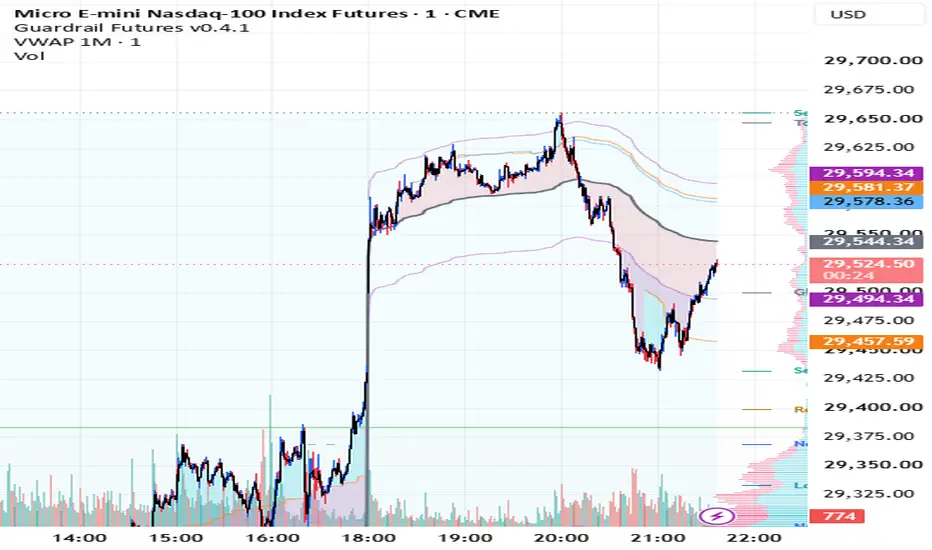
STRYK: MOMENTUMSTRYK: MOMENTUM: puts context on price in one overlay: a rolling volume-weighted average price with deviation bands, a long exponential moving average with an optional smoothing overlay, candles coloured by a selectable read (order-flow delta, participation fuel, or three price-only modes), a volume-participation background shade, and the session level map — previous Day / Week / Month highs and lows with an optional internal quartile grid, plus the overnight Asian range. Every block has a master switch and its own settings, including quick switches for the quartile lines, the zones and the paint mode; run all of it or one piece.
## Rolling VWAP
Volume-weighted average price over the last N candles of a chosen delta timeframe — with the defaults, 60-minute candles × 20, a 20-hour VWAP that slides forward as each candle completes rather than anchoring to a session. Volume-weighted standard-deviation bands at ±1σ, ±2σ and ±3σ with individual multipliers, colours and an optional ±1σ fill. The window is computed from chart bars on a ring buffer with running sums, so it loads cleanly in bar replay. A visual smoothing pass (adjustable, 1 = off) rounds the small steps that occur as the oldest candle leaves the window; the underlying values are exact.
If the chart timeframe is raised above the delta timeframe, the delta timeframe is lifted to match for that session with the same lookback (switchable to a strict error instead).
## EMA
TradingView's standard exponential moving average — length (default 233), source and offset — with its standard smoothing-MA option (SMA, EMA, SMMA/RMA, WMA, VWMA, or SMA with Bollinger Bands, default length 233) and an additional visual smoothing pass on the plotted line (1 = the stock EMA exactly).
## Candle paint — sixteen modes
Every candle (body, wick, border) is coloured by the selected mode, fading between a bear colour, a neutral colour and a bull colour through an adjustable response curve. Hide the chart's own candles so only the painted set shows. Most modes self-calibrate against their own recent history (percentile rank rather than fixed thresholds) and brighten when the bar's delta agrees with the read, dimming when it disagrees. Several modes share one visual language: a reference box (a bar's or period's value area, the previous day's range, the overnight range) — blue inside it, deepest at the centre and fading toward the edges; green above, red below, ramping with distance beyond.
Volume-profile modes — every profile is built from intrabar volume at price: **Delta size** (each bar against the prior bar's own point of control and value area), **Delta size HTF** (each bar against the last completed delta-timeframe candle's point of control and value area, alignment checked against the live higher-timeframe delta), **POC trend** (which way the live delta-timeframe candle's point of control has migrated against the completed candles before it — acceptance moving up or down — halved inside that candle's value area, boosted outside it on the migration's side; switchable to the full-session profile), and **Value area** (the session's value area as the box, brightest at the session point of control).
Order-flow modes: **Delta %** (delta as a share of volume, self-calibrated, size-gated, weighted toward how the bar closed, compounding across consecutive same-direction bars), **Fuel × Δ** (sign from the bar's delta, intensity from fuel — spike-aware participation shaped by a bell that stays full above its peak, delta agreement against the bar's own direction, and the side of the EMA), and **Participation band** (crowd presence only, no direction — a smooth gradient across the full participation rank; the background tint switches itself off while this mode is active).
Structure and level modes: **Pivot structure** (above the last confirmed pivot high bull, below the last pivot low bear, between neutral; pivots confirm after the pivot length and do not repaint), **Pivot structure HTF** (the same pivots computed on the delta timeframe's own bars), **Market structure** (a latched trend state that flips only on a close through the opposite pivot; the flip flashes at an intensity set by its quality — break distance and delta agreement — then settles to a baseline that keeps that quality), **Day range position** (the previous day's high and low as the box), and **Asian range position** (the overnight range as the box; breaks from a tight overnight range weigh more).
Trend and momentum modes: **EMA trend** (side of the script's EMA, distance self-calibrated, multiplied by the EMA's own slope and — when a smoothing line is enabled — by the EMA's position against it, with a brief flash on the bar price first crosses), **VWAP σ-distance** (stretch from the rolling VWAP in standard deviations, with a distinct exhaustion colour when price is beyond the chosen σ and delta disagrees), **Candle conviction** (pure price action — body dominance self-calibrated, gated by bar range, compounding across consecutive bars), and **RSI momentum** (gradient around 50, self-calibrated, weighted by RSI velocity and fast/slow agreement, overridden by a distinct colour on confirmed pivot divergence).
## Volume participation background
A volume EMA is normalised 0–100 against its own recent range. At the extremes the chart background tints — one colour when participation is unusually high, another when the tape is unusually quiet. Thresholds, transparency and colours are inputs.
## Session levels
**Previous Day / Week / Month high and low.** Each level comes from the completed period and is drawn from the new period's open — non-repainting. Per-timeframe toggles, colours, widths and how many past levels to keep; optional fade on older levels, name labels with position and per-timeframe text settings, extend-to-chart and project-forward options. Week start (Sunday futures / Monday cash) and the daily session-open hour are inputs. An optional **quartile grid** adds dashed lines at the 25 / 50 / 75% marks inside each shown range, and optional **zones** shade a band around each high and low line — an eighth of the range above and below it.
**Asian range.** High and low of the overnight Asian session (window set in HHMM, exchange time). The range draws dotted while the session builds, confirms solid at the session end, and can extend across the trading day or to the end of the chart. A configurable number of past sessions stays on the chart.
## Delta source — read this
Where TradingView provides volume footprint data for the bar, delta comes from `request.footprint()` bid/ask buy and sell volume. Footprint availability depends on your plan and the symbol; where it is not available the script falls back to an **estimate** of delta derived from lower-timeframe bar polarity, with the intrabar resolution chosen automatically against your plan's data budget. Estimated delta is not order-flow data and can differ materially from true delta. The footprint is built from TradingView's own tick feed: a broker data subscription does not make it real-time, and a "Delayed" chip on the chart means the colours are delayed by the same amount.
## Why these parts are together
Each block answers one part of the same question — is the current move worth trusting, and against which levels: the VWAP and bands give the fair-value anchor and stretch, the EMA gives the higher-order trend, the paint says whether the bar is being paid for (or, in the price-only modes, where it stands in structure), the background says whether anyone is participating at all, and the session levels supply the locations where those answers matter. The components are original implementations built for this combination: the rolling VWAP is window-based rather than session-anchored, the fuel paint is this script's own participation model, and the level engine draws only completed, non-repainting periods.
## Repainting
The live delta-timeframe candle's colour updates on every tick by design; completed candles do not change. Pivots (and the divergence and structure reads built on them) confirm after the pivot length. Streak counters advance only on bar close. Session levels come only from completed periods. The VWAP, bands, EMA, RSI and ATR are standard rolling calculations.
## What it is not
It draws context. It makes no prediction and contains no trade logic. 指标

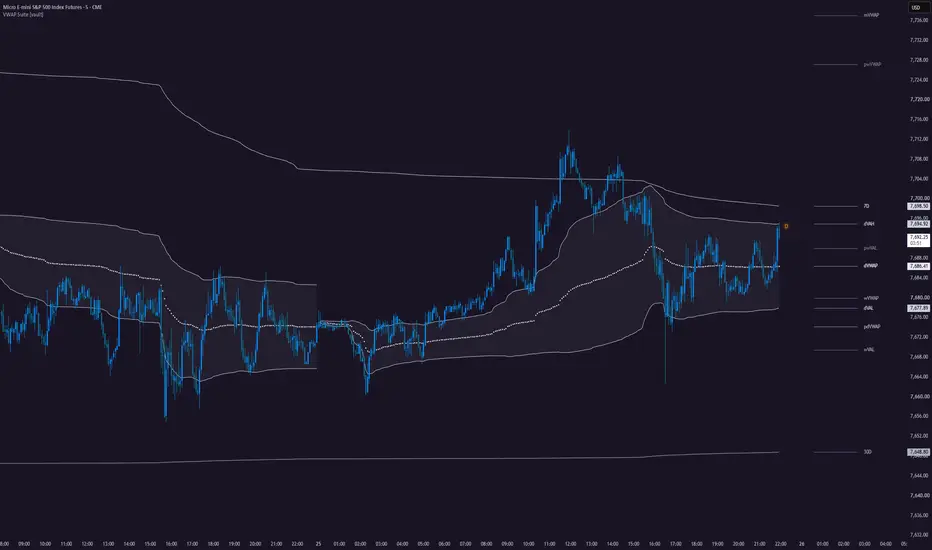
Tidemarks - Session Levels & VWAPTidemarks — Session Levels & VWAP
Tidemarks brings session levels, daily and weekly reference prices, confirmed higher-timeframe swings, and VWAP into one customizable chart overlay. It keeps key prices visible as the session develops, with individual level controls and automatic label staggering to help keep crowded areas readable.
Available levels include:
Session: Pre-market and after-hours highs and lows.
Daily: Prior-day open, high, low, and close; current-day open, high, low, and range midpoint.
Weekly: Prior-week high, low, and close; current-week open, high, and low.
Swings: Latest confirmed 1-hour and 4-hour swing highs and lows, with adjustable pivot strength.
All-time high: Highest price found in the available monthly history.
VWAP uses typical price, (high + low + close) / 3, with session, weekly, or monthly resets. Optional ±1 and ±2 standard-deviation bands show price’s distance from VWAP.
Choose between historical level segments, the latest levels extending right, or the latest levels spanning the full chart. Customize individual colors, separate line styles and widths for daily, weekly, and swing levels, label size and spacing, and optional prices on labels and the price scale. Nearby labels automatically stagger horizontally.
Built-in alert conditions cover regular-session crosses above the pre-market high or below the pre-market low, plus crosses above and below VWAP.
Tidemarks is designed primarily for intraday charts. Pre-market and after-hours levels require extended-session bars to be available and enabled. VWAP requires volume data. The 1-hour swing levels appear on chart timeframes of 1 hour or lower; 4-hour swings appear on timeframes of 4 hours or lower. Swing levels become available after confirmation, with a delay determined by the selected swing strength.
Current daily and weekly ranges develop during their periods. Historical daily, weekly, and all-time-high displays can reflect completed higher-timeframe values before those values were known live, so historical charts should not be interpreted as a record of real-time signals. The all-time-high level also depends on available history.
Rebuilt and streamlined from “Price levels” by nkwdesmond, with attribution retained under the Mozilla Public License 2.0. 指标

Stryk: VWAP + EMA# Stryk: VWAP + EMA — publish description
> Paste into the script description. No performance figures, no links, no promotional language. Estimates and data dependencies disclosed.
---
**Stryk: VWAP + EMA** puts three reads on price and nothing else: a rolling volume-weighted average price with deviation bands, a long exponential moving average with an optional smoothing overlay, and candles coloured by order-flow delta. No signals, no labels, no tables.
## Rolling VWAP
Volume-weighted average price over the last N candles of a chosen delta timeframe — with the defaults, 60-minute candles × 20, a 20-hour VWAP that slides forward as each candle completes rather than anchoring to a session. Volume-weighted standard-deviation bands at ±1σ, ±2σ and ±3σ with individual multipliers, colours and an optional ±1σ fill. The window is computed from chart bars on a ring buffer with running sums, so it loads cleanly in bar replay. A visual smoothing pass (adjustable, 1 = off) rounds the small steps that occur as the oldest candle leaves the window; the underlying values are exact.
If the chart timeframe is raised above the delta timeframe, the delta timeframe is lifted to match for that session with the same lookback (switchable to a strict error instead).
## EMA
TradingView's standard exponential moving average — length (default 233), source and offset — with its standard smoothing-MA option (SMA, EMA, SMMA/RMA, WMA, VWMA, or SMA with Bollinger Bands, default length 233) and an additional visual smoothing pass on the plotted line (1 = the stock EMA exactly).
## Candle paint
Every candle (body, wick, border) is coloured by the live delta of the delta-timeframe candle it belongs to, fading between a bear colour, a neutral colour and a bull colour. Two intensity modes: delta size relative to the recent average |Δ|, or delta as a percentage of total volume (imbalance), with a sensitivity input and a square-root "boosted" response curve. Hide the chart's own candles so only the painted set shows.
## Delta source — read this
Where TradingView provides volume footprint data for the bar, delta comes from `request.footprint()` bid/ask buy and sell volume. Footprint availability depends on your plan and the symbol; where it is not available the script falls back to an **estimate** of delta derived from lower-timeframe bar polarity, with the intrabar resolution chosen automatically against your plan's data budget. Estimated delta is not order-flow data and can differ materially from true delta. The footprint is built from TradingView's own tick feed: a broker data subscription does not make it real-time, and a "Delayed" chip on the chart means the colours are delayed by the same amount.
## Repainting
The live delta candle's colour updates on every tick by design; completed candles do not change. The VWAP, bands and EMA are standard rolling calculations.
## What it is not
It draws context. It makes no prediction and contains no trade logic. 指标

ORB+VWAP NY BounceORB + VWAP Bounce — opening-range break with a resting VWAP retest
An intraday entry model for the 1-minute chart on index futures. It
combines an opening-range breakout filter with a mean-reversion entry,
and it only ever takes one trade per session.
THE IDEA IN ONE SENTENCE
The opening range breaks; a resting LIMIT order then waits at the
session VWAP and fills the moment price retests it in the direction of
that break.
HOW IT WORKS
Each session runs through three phases.
1. RANGE — the script records the high and low of the opening-range
window (09:30–10:00 New York by default). Nothing is armed until
this window closes.
2. BREAK — when price closes beyond that high or low, the side of the
break sets the direction for the rest of the day. Broke up = long
only. Broke down = short only. This is the only thing that decides
direction.
3. RETEST — from the start of the entry window, a limit order rests on
the session VWAP, anchored at the RTH open. A long fills on the
pullback down to it; a short fills on the rally up to it.
WHY THE ENTRY IS A RESTING LIMIT, NOT A MARKET ORDER
This is the part worth understanding before using it.
A buy limit can only rest BELOW the market, and a sell limit only
ABOVE it. So "price is on the correct side of VWAP" is not something
the script has to check — it is inherent to the order type itself. A
long only exists if price is above the VWAP and pulls back into it; a
short only exists if price is below and rallies into it.
That is why there is no separate trend filter or bias input in this
script: there would be nothing left for it to decide. The break sets
direction, the order type enforces location.
The trade-off is real and you should know it: a resting limit fills at
a known price but is not guaranteed to fill at all. Days where price
breaks and never returns to the VWAP simply produce no trade. The
script is designed to sit out far more often than it trades.
SETTINGS
Session / Time — timezone, the RTH session that defines the trading
day, the opening-range window, the entry window, and a forced flat
time. No position is ever carried overnight.
Entry Logic — direction (long only / short only / both), which VWAP
anchor the limit rests on (RTH open or Globex open), an optional tick
offset so the limit sits a hair on the approach side, and the maximum
number of trades per day.
Filters / Seasonality — day-of-week switches, month exclusions, and
separate gates for the short side only (a time cut-off, weak months,
and a weekday block). All of these are OFF or neutral by default. They
exist so you can test whether your own instrument and session show
asymmetries, not because any particular setting is recommended.
Setup Quality — an optional gate on the size of the opening range,
measured either in points or as a multiple of the previous day's ATR.
The ATR mode is self-scaling, so one setting holds across changing
volatility regimes. OFF by default.
Stop / Target — the stop can be a fixed tick distance, a multiple of
the daily ATR, the VWAP line itself, the opposite side of the opening
range, or a retest swing. Targets can be an R multiple, a multiple of
the range, a fixed tick distance, or none at all.
Trailing Stop — optional, by R multiple or by points, with a
configurable activation threshold. There is a switch to remove the
fixed target once the trail is active, so a runner is not capped.
Risk Management — position size derived from a fixed dollar risk and
the actual stop distance, or a fixed contract count. Note that the
derived size is a step function: contracts = floor(risk / (stop
distance x point value)). Small changes in risk can leave the contract
count unchanged, and then jump it by a whole contract.
WHAT ELSE IS ON THE CHART
A Market Positioning table compares price against five VWAPs (session,
overnight, previous session, high-of-day, low-of-day) plus the opening
range, for the chart symbol and two correlated tickers you choose. It
also reports the opening-range size in points and in ATR multiples,
and the daily ATR itself.
There is an optional risk:reward box drawn on each entry, and an
optional prop-firm tracker that reports balance, distance to a
trailing drawdown line, worst margin reached, and a consistency
measure.
Every order carries a JSON alert_message suitable for automation
platforms that parse webhook payloads.
BACKTESTING NOTES — PLEASE READ
Two Properties settings change results substantially on this script,
and both default to values that flatter it:
- Limit order execution. Every entry here is a limit order resting on
the VWAP. The "Requested price" setting assumes a fill the moment
price grazes the line without trading through it, which is
optimistic for a resting order. Use "Standard".
- Bar detalization. Set it to High. On a 1-minute chart with intrabar
stop and target logic, the default resolution is too coarse.
Also apply realistic commission and slippage for your instrument
before drawing any conclusion.
LIMITATIONS
This script takes at most one trade per session and requires both a
range break and a retest, so it trades infrequently. On any given
instrument the sample it produces over a few years may be small enough
that ordinary variance dominates. Treat any backtest of it as a
description of one particular past, not as an expectation.
Seasonal and day-of-week filters are especially easy to overfit: with
a handful of trades per month, apparent patterns appear by chance.
They ship neutral for that reason. If you turn them on, check that the
effect holds in every year of your sample independently, not just in
the total.
Defaults are a starting point for the instrument and session they were
written around. They are not tuned for yours.
Nothing here is financial advice. 策略

Multi Anchored VWAP - Automatic Session and Custom AnchorsThis indicator was built to remove the daily manual work involved in resetting multiple anchored VWAPs.
It automatically maintains a set of recurring VWAPs based on key market/session events, while also providing discretionary anchor slots for events or levels you want to track manually.
Default automatic VWAPs
Asia — 01:00 Europe/London
Frankfurt Open (FFO) — 07:00 Europe/London
London Open (LDO) — 08:00 Europe/London
New York Open — 09:30 America/New_York
Weekly — Friday 21:00 Europe/London
Gold Auction — 15:00 Europe/London, disabled by default
Each automatic VWAP continues running until its next scheduled anchor. For example, the New York VWAP remains active overnight and through the following European session, only resetting when the next New York cash open occurs.
Timezone-aware anchors
Each VWAP uses an explicit market/event timezone rather than the trader's local timezone. This means traders in different countries can use the same settings and see the same anchored VWAPs.
The timezone and anchor time for every automatic VWAP can also be changed from the settings menu.
IANA timezones such as Europe/London and America/New_York are used so daylight-saving changes are handled automatically.
Discretionary anchored VWAPs
Three additional custom VWAP slots are included and disabled by default.
Each custom VWAP allows you to specify:
Enable/disable
Custom name
Exact anchor date/time
Colour
Line thickness
These can be useful for anchoring from events such as CPI, FOMC, major highs/lows, news events, breakout points, or any other discretionary reference.
Unlike the automatic session VWAPs, custom VWAPs do not reset automatically and remain anchored until changed or disabled.
Visual settings
Each VWAP can be individually enabled or disabled and has configurable colour and line thickness.
Right-edge labels can also be customised for size, transparency and offset, making it easy to identify each VWAP directly on the chart.
Intended use
I mainly use this on NQ, ES and Gold for intraday context, mean-reversion/reference areas, confluence and tracking how price interacts with session and event-based value.
This indicator is intended as a charting/context tool rather than a standalone entry or trade signal. 指标

Structure-Anchored VWAP [WillyAlgoTrader]📐 Structure-Anchored VWAP is an overlay indicator that anchors a true volume-weighted average price to market structure and re-anchors it automatically at every confirmed swing pivot, structure break, fast extreme, or one manual date — combining a pivot-based structure engine, an O(1) prefix-sum VWAP core, volume-weighted sigma bands, a retest entry model with ATR risk management, and a sectioned dashboard with session statistics.
The core insight: a VWAP anchored to the start of the current structural leg tells you the average price at which volume actually changed hands since this move began. That is the level participants in this leg are collectively break-even at. Session VWAP resets at midnight and ignores structure. Manual anchored VWAP requires you to drag it and re-drag it. This indicator keeps the anchor synchronised with the structure itself, and measures how stretched price is from that anchor in the leg's own volume-weighted standard deviations rather than in generic ATR units.
It works on any market and any timeframe. On instruments with no volume feed it falls back to time weighting automatically and says so in the dashboard.
🧩 WHY THESE COMPONENTS WORK TOGETHER
A VWAP alone has no memory of structure — it does not know whether the market is making higher highs or lower lows, so it cannot know when its own anchor has gone stale. A structure detector alone tells you HH / HL / LH / LL but gives you no price level to trade against. Deviation bands built on ATR describe candle size, not participation, so they say nothing about where volume was actually transacted. And an entry signal without a fixed stop and target is not a trade, it is an opinion.
This indicator connects all four into one chain:
Pivot structure engine → anchor selection → prefix-sum anchored VWAP → volume-weighted sigma bands → retest detection → ATR risk model → session statistics
The structure engine finds confirmed swing highs and lows, filters them by ATR amplitude and enforces strict high/low alternation, so every anchor is a real structural turn rather than a passing wick. Anchor selection decides which of those turns starts a new leg, with four different policies for four trading styles. The prefix-sum core then computes the anchored VWAP for that leg — and because it also accumulates the sum of squared prices, the same pass produces the leg's own volume-weighted standard deviation, so the bands are derived from the same data as the line instead of being bolted on. The retest engine watches the distance between price and that line, requires price to leave and come back, and only then produces an entry. The risk model turns the entry into a fixed stop and three targets, and the statistics layer records what happened to each of them.
Remove any link and the chain stops working. Without structure anchoring, the VWAP measures a leg that ended days ago. Without the ATR amplitude filter, every minor wick creates a new anchor and the line resets constantly. Without the sigma bands, "far from VWAP" has no unit. Without the retest rule, every touch of the line is a signal, including the fifty touches that happen while price is glued to it. Without the risk layer, you know where to enter but not where you are wrong.
🔍 WHAT MAKES IT ORIGINAL
1️⃣ Prefix-sum VWAP core — any anchor evaluated in O(1), including a decayed one.
Three running totals are maintained on every bar, where p is the price source and w is the bar weight:
— S_w(t) = lam × S_w(t−1) + w(t)
— S_pw(t) = lam × S_pw(t−1) + p(t) × w(t)
— S_p2(t) = lam × S_p2(t−1) + p(t)² × w(t)
The sum over any leg is then recovered without looping:
— sum = S(t) − lam^(t−a+1) × S(a−1)
With lam = 1 this is an exact cumulative anchored VWAP — every bar of the leg keeps its full weight, the same quantity the built-in Anchored VWAP tool computes. With lam < 1 the same identity still holds, which is what makes the optional Half-life mode possible without a second engine.
Why this matters: re-anchoring becomes cheap. Moving the anchor does not require replaying the whole leg bar by bar, so the indicator can afford four anchor modes and legs up to 4000 bars long without a performance penalty.
2️⃣ Volume-weighted sigma bands — dispersion of the leg, not size of the candle.
Because the squared-price sum is already accumulated, the leg's variance comes out of the same pass:
— VWAP = sum_pw / sum_w
— sigma = sqrt( max( sum_p2 / sum_w − VWAP², 0 ) )
Bands are drawn at VWAP ± multiplier × sigma. Band 1 defaults to 0.5 sigma (the value-area edge of this leg), Band 2 to 2.0 sigma and is off by default.
Why this matters: an ATR band tells you how big recent candles were. A volume-weighted sigma band tells you how widely the volume of this specific leg was distributed around its own average price. Two markets with identical ATR but different participation profiles get different bands, and the "Premium / Fair value / Discount" classification in the dashboard becomes comparable across instruments.
3️⃣ Four anchor modes — one engine, four trading styles.
— Swing (default): a new leg starts at every confirmed pivot. The anchor is the opposite extreme, so a bullish leg is anchored at the swing low that preceded it.
— Structure break : a new leg starts only when price closes beyond the previous swing. The anchor is then the extreme that preceded the break, found by scanning back from that swing. Fewer legs, each tied to an actual break of structure.
— Fast : no confirmation delay. The bar printing the highest high or lowest low of the last N bars (default 30) is treated as a new extreme, and the leg flips the moment an extreme opposite to the previous one appears. When a bar prints both a new high and a new low, the candle direction decides which one is taken.
— Manual : a single leg from a chosen date and time, which reproduces the behaviour of the built-in Anchored VWAP tool inside the same framework — useful for comparing against a manual anchor or pinning a level.
4️⃣ Structure engine with ATR amplitude filter and strict alternation.
Pivots come from equal left/right lookback (default 55/55). A new pivot of the opposite type is only accepted when it clears an ATR-scaled amplitude:
— accept a new high when: pivotHigh − lastSwingLow ≥ minSwing × ATR(atrLen)
— accept a new low when: lastSwingHigh − pivotLow ≥ minSwing × ATR(atrLen)
Default minSwing 1.5, ATR length 13. A pivot of the same type as the last one does not create a new structural point — it only supersedes the previous extreme if it is more extreme. This enforces a clean alternating high-low-high-low sequence instead of clusters of adjacent highs.
Classification against the previous extreme of the same type, with an equality tolerance (default 0.1 × ATR):
— |current − previous| ≤ eqTol × ATR → EQH or EQL
— current > previous → HH or HL
— current < previous → LH or LL
5️⃣ Retest entry model — price must leave before it can come back.
Every bar the engine measures the relationship between the bar range and the anchored VWAP:
— tol = sigma × touchTolerance (default 0.25), or ATR × 0.1 while sigma is still zero
— touch = low ≤ VWAP + tol and high ≥ VWAP − tol
— outside = bullish leg ? low > VWAP + tol : high < VWAP − tol
An "away" counter increments on every outside bar and resets to zero on every touch. A retest fires only when a touch happens while the committed away counter has already reached the threshold (default 5 bars).
Why this matters: a raw "price touched VWAP" condition fires continuously in the chop that surrounds every mean. Requiring a genuine departure first converts an omnipresent condition into a discrete, countable event.
6️⃣ Volume balance — who controlled this leg.
While the leg accumulates, every bar's weight is assigned to one of two buckets by where it closed relative to the VWAP at that moment:
— close ≥ VWAP → volUp += w
— close < VWAP → volDn += w
— balance = volUp / (volUp + volDn) × 100
The dashboard shows this as a percentage with a bar gauge, and relabels it "Bars above VWAP" automatically when the instrument has no volume data. Above 50 % means most of the leg's participation happened above its own average price.
7️⃣ Signal strength — a transparent 0-100 context score.
Four independent components, published in full so the number is auditable rather than a black box:
— 40 pts × (volume balance aligned with leg direction, 0..1). For a bearish leg the balance is inverted before scoring.
— 25 pts if price sits on the leg's own side of the VWAP.
— 20 pts if price is not stretched beyond Band 2, i.e. |distance in sigma| ≤ band 2 multiplier.
— 15 pts if the leg has already produced at least one retest.
The score is clamped to 100 and shown with a gauge. This is a context filter, not a proven edge — it says how coherent the current leg is, nothing more.
8️⃣ VWAP memory levels — dead legs leave a level behind.
When a leg ends on a genuine direction flip, its final VWAP value is written to the chart as a dashed horizontal line. That line extends forward until price trades through it, then it is either removed or faded to dotted, depending on a setting. Up to four such levels are kept (configurable), and the newest push out the oldest.
When a level is created, the bars between the anchor and the current bar are scanned first, so a level that was already traded through is never shown as untouched.
9️⃣ Single-position trade model with break-even and outcome tracking.
A retest signal opens a trade only while flat — signals never stack. On entry, the levels are fixed once and never recalculated:
— slDistance = ATR(riskAtrLen) × slMultiplier
— long: SL = entry − slDistance, TP(n) = entry + slDistance × tpMult(n)
— short: SL = entry + slDistance, TP(n) = entry − slDistance × tpMult(n)
Presets set all four multipliers at once — Conservative 2.5 / 1R / 2R / 4R, Balanced 1.5 / 1R / 2R / 3R, Aggressive 1.0 / 1.5R / 2.5R / 4R, Scalping 0.8 / 0.8R / 1.5R / 2R, or Custom.
Break-even is optional and on by default: the first touch of TP1 moves the stop to the entry price, the entry label changes to show it now acts as the stop, and the stop line dims. TP1 still counts as a win. Hit checks begin only on the bar after entry and only on confirmed bars, so the entry bar's own range cannot close the trade it just opened.
🔟 Persistent trade forensics — the chart keeps the last result.
SL and TP lines are not deleted when the trade closes. They stay until the next entry, so the last trade remains readable on the chart: any target that was reached is redrawn as a solid teal line and its label gets a check mark, while untouched targets keep their original dashed style. Labels can show the distance from entry in percent, for example "SL 78120.5 (-0.36%)".
1️⃣1️⃣ Realtime correctness — ring buffers and a commit/undo pattern.
Functions that only run on some bars cannot use the history operator safely, because the history they see is sparse and does not correspond to chart bars. All per-bar values this indicator needs later are therefore written to explicit ring buffers on every single bar, and read back by index.
On top of that, the live leg uses a commit/undo pattern: statistics are always recomputed from the last confirmed state, and the provisional point for the forming bar is popped before a new one is pushed. A bar being formed can therefore never be counted twice, no matter how many ticks arrive.
1️⃣2️⃣ Continuous curve across anchor changes.
When a new anchor appears, the previous leg is not erased — it is cut exactly at the new anchor bar and frozen. The curve therefore has no gaps at handover points, including the case where a stronger extreme of the same type supersedes the previous one.
⚙️ HOW IT WORKS — CALCULATION FLOW
Step 1 — Structure: On each confirmed bar the engine evaluates pivot highs and lows with equal left/right lookback, applies the ATR amplitude filter, enforces high/low alternation and classifies the result as HH, HL, LH, LL, EQH or EQL.
Step 2 — Weighting: The bar weight is volume, or 1.0 when the instrument has no volume. If spike clamping is on, the weight is capped at N × the 50-bar median volume so a single print cannot dominate the average.
Step 3 — Accumulation: The three running totals of weight, price × weight and price² × weight are advanced, decayed by lam if Half-life weighting is selected.
Step 4 — Buffering: The totals plus high, low, close and ATR are appended to ring buffers, one entry per bar, with the current bar's provisional entry overwritten rather than duplicated on repeat ticks.
Step 5 — Anchor decision: The active anchor mode decides whether this bar starts a new leg and where that leg's anchor sits.
Step 6 — Leg build: On a new anchor the previous leg is trimmed to the anchor bar, frozen and archived, a memory level is created if the direction actually flipped, and the new leg is replayed once from the anchor to the current bar. On every other bar the live leg simply advances by one point.
Step 7 — Readouts: VWAP, sigma, distance in sigma and percent, zone, volume balance, leg age and the strength score are computed for the current bar.
Step 8 — Signal: The retest rule is evaluated. A qualifying retest, on a confirmed and warmed-up bar, while flat, becomes an entry.
Step 9 — Risk: On entry the stop and three targets are fixed. On later confirmed bars they are tested for hits, break-even is applied after TP1, and the trade is closed by stop or final target.
Step 10 — Reporting: Lines, labels, markers, the dashboard and alerts are updated. Closed trades update the win/loss counters and the form strip.
📖 HOW TO USE
🎯 Quick start:
1. Add the indicator. Defaults are tuned for 15m to 4H swing structure.
2. Watch the coloured curve — it is the anchored VWAP of the leg the market is currently in.
3. Wait for a Long ▲ or Short ▼ marker. That is a retest of the VWAP in the direction of the leg.
4. Read the Trade section of the dashboard for the stop, the three targets and the R:R.
5. If signals are too frequent, raise "Bars away before a retest counts". If legs are too frequent, raise pivot strength or the minimum swing size.
👁️ Reading the chart:
— 🟢 Green curve = bullish leg, anchored at the swing low that started it.
— 🔴 Red curve = bearish leg, anchored at the swing high that started it.
— Shaded band around the curve = ± sigma of this leg. Price inside it is at fair value for the leg.
— 🟢 Long ▲ / 🔴 Short ▼ marker = a retest entry was taken on that bar.
— Dotted blue line = entry. Solid red line = stop. Dashed green lines = TP1, TP2, TP3.
— A target that turns solid teal with a ✓ in its label was reached.
— An orange entry label reading "→ SL (BE)" means the stop has been moved to break-even.
— Dashed horizontal level far from the curve = a memory level, the final VWAP of a finished leg.
— HH / HL / LH / LL / EQH / EQL tags mark every confirmed pivot.
📊 Dashboard fields:
— Trend : direction of the current leg.
— Signal : LONG, SHORT or Wait. A new trade can only open while flat.
— Strength : the 0-100 context score with a gauge.
— Last event : the most recent new leg or retest.
— Timeframe : the chart resolution.
— Mode : active anchor mode and weighting, plus a note when the symbol has no volume.
— Anchor : structure tag and price of the bar the leg is anchored to.
— Leg age : bars since the anchor and the price move from it.
— VWAP : the anchored VWAP on the current bar.
— Price vs VWAP : distance in sigma and in percent.
— Zone : Premium above Band 2, Discount below it, Fair value in between.
— Vol above VWAP : share of the leg's weight transacted above the VWAP, with a gauge.
— SL / TP1 / TP2 / TP3 : the fixed levels of the open trade. A ✓ marks a reached target, "BE @" marks a stop moved to entry.
— R:R (TP1) and SL Dist % : reward-to-risk at the first target and the stop distance as a percentage of entry.
— Trades / W / L / Win rate / Form : closed trades in the loaded history, the win-loss split, the win rate with a gauge and the last ten outcomes as ▰ and ▱.
🔧 Tuning guide:
— Too many legs, the line resets constantly: raise pivot strength (55/55 → 80/80) or the minimum swing size (1.5 → 3.0).
— Legs appear too late: lower pivot strength, or switch the anchor mode to Fast for immediate flips.
— Too many entries: raise "Bars away before a retest counts" and lower the touch tolerance.
— The line drifts too far from price on long legs: switch Weighting to Half-life. This is no longer a textbook VWAP, and the dashboard says so.
— Comparing against the built-in Anchored VWAP tool: set the mode to Manual with the same anchor time, price source to hl2, weighting to Cumulative, and turn volume clamping off.
— Stops feel too tight or too wide: change the Risk Preset before touching individual multipliers.
⚙️ KEY SETTINGS
⚙️ Main Settings:
— Pivot strength left / right (default 55 / 55): bars required on each side of a swing. Right is the confirmation delay.
— Minimum swing size (default 1.5 × ATR): amplitude filter for new pivots. 0 disables it.
— ATR Length (default 13): ATR used by the swing filter and the equality tolerance.
— Re-anchor on (default Swing): Swing, Structure break, Fast or Manual.
— Fast mode: extreme lookback (default 30): lookback for the Fast mode only.
— Equal high/low tolerance (default 0.1 × ATR): threshold for EQH and EQL tags.
— Manual anchor : date and time for the Manual mode, shown in the chart's timezone.
📐 Anchored VWAP:
— Price source (default hl2): hl2 matches the built-in tool, hlc3 weights closes more, close is the most reactive.
— Weighting (default Cumulative): Cumulative is a true VWAP, Half-life fades older bars.
— Half-life (default 21 bars): only used by Half-life weighting.
— Clamp volume spikes (default on, 4 × median): caps outlier volume bars.
— Max leg length (default 4000 bars): keeps very old anchors bounded.
📏 Deviation Bands:
— Band 1 (default on, 0.5 sigma): inner band.
— Band 2 (default off, 2.0 sigma): outer band, also defines the Premium and Discount zones.
— Fill transparency (default 90).
🎯 Signals & Levels:
— Bars away before a retest counts (default 5).
— Touch tolerance (default 0.25 sigma).
— VWAP memory levels (default on, max 4, crossed levels removed).
🛡️ Risk Management:
— Risk Preset (default Balanced): Conservative, Balanced, Aggressive, Scalping or Custom.
— ATR Length (SL) (default 13).
— SL ×ATR / TP1 / TP2 / TP3 ×Risk (defaults 1.5 / 1.0 / 2.0 / 3.0): used by the Custom preset.
— Break-Even After TP1 (default on).
— Show SL/TP Lines, Labels, % Distance (all on by default).
— Entry / SL / TP Line Style (defaults Dotted / Solid / Dashed).
🎨 Visual:
— Theme (default Auto): Auto detects the chart background, Dark and Light force it.
— Show Buy/Sell Signals, HH/HL/LH/LL, Leg Background, Watermark .
— SL/TP Label Font Size (default Small).
— Finished legs kept on chart (default 30).
📊 Dashboard:
— Position (default Top Right) and four independent section switches: Market, VWAP, Trade, Stats.
🔔 ALERTS
— 🟢 LONG — VWAP retest entry, with price, VWAP, SL, TP1, TP2, TP3 and R:R
— 🔴 SHORT — same payload, short side
— 🛑 SL HIT — entry and stop price. Reported as 🛡️ BE STOP-OUT when the stop had already been moved to break-even
— 🛡️ BREAK-EVEN — stop moved to entry after TP1 (optional)
— 🎯 TP1 HIT, 🎯🎯 TP2 HIT, 🏆 TP3 HIT — first touch of each target (optional)
— 🟢 New bullish leg / 🔴 New bearish leg — a new anchor was set (optional)
— 🔵 Close above VWAP / 🔵 Close below VWAP — the close crossed the anchored VWAP (optional)
Entry alerts support both plain text and a JSON webhook payload. All alerts fire on bar close.
⚠️ IMPORTANT NOTES
— 🚫 No repainting of confirmed values. Every structure event, entry, stop, target and alert is evaluated only when barstate.isconfirmed is true. Pivots use equal left and right lookback, so the swing point is in the past by the "right" value at the moment it becomes known — that is delayed confirmation, not a look into the future. Stop and target hits are tested only from the bar after entry. Alerts fire once per bar close.
— 📐 What does update intrabar. The VWAP value of the leg currently in progress moves while the bar is forming, because that is what an anchored average does. Values on closed bars never change. A commit/undo pattern makes sure a forming bar is never counted twice in the statistics.
— 📐 The unfinished leg can be shortened. When a stronger extreme of the same type is confirmed, the current leg is cut at that point and a new leg starts there. Legs that have already been archived are never modified.
— 📊 The statistics are not a backtest. Trades, win rate and the form strip are counted over the history currently loaded on the chart and reset when the chart reloads or a setting changes. They describe how this rule set behaved on the visible data. Past performance does not guarantee future results.
— 🧮 The strength score is a context filter. Its four components and weights are published above precisely so it can be judged on its merits. It measures the internal coherence of the current leg, not the probability of any outcome.
— ⚖️ Half-life weighting is not a VWAP. When that mode is selected the line is an exponentially weighted average, useful on instruments without volume, but it is no longer the textbook volume-weighted average price. The dashboard states the active mode at all times.
— 🌐 Universal compatibility. Works on stocks, futures, forex, crypto and indices, on every timeframe. Where no volume data exists the weighting falls back to time and the dashboard relabels the volume-balance row accordingly.
— 🛠️ Decision support, not automation. This is an anchored VWAP and structure analysis tool with a risk framework attached. It marks anchors, measures distance in the leg's own units, detects retests and lays out stops and targets — trade decisions remain yours. 指标

Multiday Anchored Auto VWAP by ByblloOVERVIEW
Multiday Anchored Auto VWAP plots up to 10 automatically anchored, rolling Volume Weighted Average Price (VWAP) lines - Rolling Day #0 (today) through Rolling Day #9 (9 days ago) - plus 5 fully independent manual VWAP lines you anchor to any date/time you choose.
Unlike anchored-VWAP tools that force a choice between automatic or manual mode, the 10 automatic Rolling Day lines and the 5 Manual Input lines here run completely independently and can be shown together - keep the last few rolling days visible for a short-term picture while also anchoring a Manual line to a specific earnings date or session open.
INTENDED USE
Well suited to short-term futures scalping - Nasdaq futures (NQ/MNQ) and similar instruments. Primarily used on the 1-minute chart, but the rolling VWAP levels hold up just as well on 2, 3, and 5-minute charts and other intraday timeframes, since the anchor logic is independent of your chart's timeframe.
FEATURES
- 10 automatic Rolling Day VWAP lines, each recalculated fresh from "now" every run (via timenow) - no hardcoded dates, so the lines never go stale or need republishing.
- 5 independent Manual Input VWAP lines with full date/time pickers, for anchoring to a specific event, earnings date, or session open.
- Single "Auto Mode Session Start Time (HHMM)" input applies to all 10 rolling lines at once - default 07:00 (Asia/Seoul), aligned with the Nasdaq futures (Globex) 18:00 ET session open during US Daylight Saving Time (shifts to 08:00 KST during US Standard Time - adjust as needed around the DST transition).
- Calendar-day based rolling (not trading-day based) for simple, predictable anchoring - see the author's companion script "Multiday VWAP by Bybllo" if you need trading-day-aware anchoring instead.
- Anchor-point safety guard prevents accumulation before each line's actual start, so no artificial spikes at the anchor bar.
- Optional anchor-start labels (#0-#9, M1-M5) marking exactly where each line begins.
- Works on any chart type (candlestick, Heikin Ashi, Renko, etc.) since prices are pulled via request.security() from the underlying ticker.
This script requires volume data from your data provider. For educational and informational purposes only, not financial advice. Always verify how these levels behave on your specific symbol and timeframe before relying on them for live trading. 指标

VWAP Z-Score Oscillator**VWAP Z-Score Oscillator — Complete Description**
**Overview**
The indicator is a single-pane oscillator that measures how far price has moved from a rolling, volume-weighted average price. It answers one question on every bar: how far is price from its recent volume-weighted fair value, and how significant is that gap. The output can be shown either as a normalized standard-deviation reading or as the raw price distance, selectable by the user.
**Core Calculation**
- **Moving VWAP.** A rolling volume-weighted mean of price is computed over a user-set lookback. Unlike a session VWAP, it slides forward continuously and never resets at the session boundary.
- **Volume-weighted standard deviation.** The dispersion of price around that Moving VWAP is calculated as a volume-weighted variance, then square-rooted. It expands when volatility rises and contracts when the market is quiet.
- **Oscillator value.** In Z-Score mode the plotted value is the price-to-VWAP gap divided by that standard deviation, so the reading is expressed in standard deviations. In Distance mode the plotted value is the raw gap in the instrument's own price units. Zero means price is resting on the Moving VWAP; positive means above, negative means below.
**Two Display Modes**
- **Z-Score (σ).** Normalized. The band levels are read directly as standard deviations, and reference lines sit at constant levels. Because the scale is unit-free, the same levels carry the same meaning on any symbol or timeframe.
- **Distance.** Raw. The oscillator shows the actual price gap, and each band is drawn at its level multiplied by the standard deviation, so the bands widen and tighten with volatility while the raw distance stays interpretable.
**Multi-Timeframe Calculation**
A calculation-timeframe selector runs the entire computation on a chosen timeframe rather than only the chart's. The default uses the chart timeframe. Choosing a higher timeframe recomputes the Moving VWAP, the standard deviation, and the oscillator on that timeframe's bars and pulls the result back through a single combined data request. The request runs without look-ahead, so no future higher-timeframe data leaks into historical bars; the current higher-timeframe value continues updating until that bar closes.
**Visual Output**
- The oscillator plots as a histogram, colored by which side of the Moving VWAP price is on.
- The histogram fades across a user-defined transparency range: faint near the VWAP, intensifying to full color as price stretches to a set distance, then holding solid beyond it.
- A solid zero line marks the Moving VWAP.
- Three standard-deviation bands are drawn above and below zero, each with its own toggle, level, and color.
**User Inputs**
*Calculation Timeframe*
- **Calculation Timeframe** — the timeframe the oscillator is computed on. Options are labeled in plain language across seconds, minutes, hours, days, weeks, and a month, plus Chart. Chart uses the current chart timeframe. Higher timeframes give a broader context; lower-than-chart selections are not recommended, and seconds-based options only work on charts that support second-level data.
*Settings*
- **Oscillator Mode** — switches between Z-Score (σ), the normalized standard-deviation reading, and Distance, the raw price gap with volatility-scaled bands.
- **Source** — the price series feeding both the Moving VWAP and the distance measurement. Defaults to the average of high, low, and close; a close-only source reacts faster.
- **Moving VWAP Length** — the number of bars in the rolling window for both the VWAP and its standard deviation. Larger values are smoother and slower; smaller values are more reactive.
- **Fallback to MA on no-volume symbols** — when enabled, symbols that report no volume use a simple moving average and plain standard deviation so the oscillator still functions; when disabled, such symbols show nothing.
*Standard Deviation Bands (three identical rows: Band 1, Band 2, Band 3)*
- **Toggle** — shows or hides that band's upper and lower lines independently.
- **Level (Σ)** — that band's distance from zero, in standard deviations, adjustable in fine steps. Defaults are 1, 2, and 3.
- **Color** — the color applied to both the upper and lower line of that band.
- Band 2's level additionally sets the threshold used by the two stretch alerts.
*Colors*
- **Above VWAP** — histogram color when the oscillator is positive.
- **Below VWAP** — histogram color when the oscillator is negative.
- **Transparency at VWAP** — histogram transparency when price sits on the Moving VWAP; the faint end of the color range.
- **Transparency at Full Color** — histogram transparency once price reaches the full-color distance; the solid end of the range.
- **Full-Color Distance (σ)** — the standard-deviation distance over which the histogram fades from faint to solid; beyond it, the color holds solid.
**Data Window Outputs**
Two values are exposed for inspection or use by other scripts: the Moving VWAP and the standard deviation. The oscillator value itself is also readable from the histogram plot. These do not draw on the chart pane.
**Alerts**
Four alert conditions are available: price crossing above the Moving VWAP, crossing below it, stretching beyond Band 2's upper level, and stretching beyond Band 2's lower level. The stretch alerts follow Band 2's configured level in both modes.
**Behavioral Notes**
- In Z-Score mode the oscillator is unbounded. During a violent move it can spike past four or five standard deviations, which reflects genuine dislocation rather than a display error.
- The Style tab is intentionally empty; all appearance and behavior controls live in the Inputs tab, so nothing there can override the code-driven output.
- The indicator's sole basis is price distance from the Moving VWAP; there is no market-structure logic in the calculation. 指标

Golden Trident | Swing-Anchored VWAP Trend SystemGolden Trident is a long-only, daily-timeframe trend-following strategy built specifically for XAUUSD (spot gold). Rather than relying on a lagging moving-average crossover or a single volatility band, it reads market structure directly — tracking swing highs and lows to determine trend direction — and pairs that with a volume-weighted anchor price that resets at every structural trend change. This gives the strategy a "fair value" reference line that adapts to each new trend leg rather than dragging a fixed-length average behind it.
The strategy is deliberately long-only. Gold has spent most of its liquid trading history in a secular uptrend, and countertrend short entries were found to meaningfully drag down both total return and risk-adjusted performance without adding diversification benefit — so the system simply steps to the sidelines when structure turns bearish, rather than fighting the dominant trend.
Position sizing is intentionally simple: a fixed percentage of equity per trade, compounding as equity grows. Risk management is handled by a single wide "catastrophe" stop rather than a tight trailing stop — the strategy is designed to exit on genuine trend reversal, not to be shaken out by normal daily noise.
How It Works
Swing Structure (Trigger): The strategy tracks rolling swing highs and lows over a configurable lookback. When the most recent extreme is a new high, structure is bullish; when it's a new low, structure is bearish.
Anchored VWAP (Trend Reference): Each time structure flips, the volume-weighted average price calculation resets and begins accumulating fresh from that point — producing a trend-relative fair-value line rather than a static average.
EMA200 Filter (Structure Confirmation): Long entries additionally require price to be trading above the 200-period EMA, keeping trades aligned with the macro trend.
Chop Filter (Volatility Gate): Entries are blocked when recent price range is too narrow relative to ATR — this avoids entering on structural "flips" that occur during sideways consolidation, where they're most likely to reverse immediately.
Exit: Positions close purely on structural trend reversal. No trailing stop is used, since research during development found trailing exits tended to cap winning trades prematurely without meaningfully reducing losses.
Backstop Stop: A wide ATR-based stop exists purely as disaster protection for extreme, unexpected moves — it is not intended to be part of normal trade management.
Features
Swing-structure trend detection (not a lagging indicator crossover)
Self-resetting anchored VWAP trend reference
Optional EMA200 macro trend filter
Optional ATR-based chop/consolidation filter
Configurable backtest date range
Trade outcome visualization (colored boxes showing each closed trade's entry-to-exit range)
Live dashboard showing current structure, volatility state, position size, and open P/L
Gold-themed visual design with gradient trend fill and directional bar coloring
Tips for Use
Timeframe: Designed and tested on the daily chart. Shorter timeframes will likely need proportionally shorter swing/EMA/ATR lengths.
Data quality matters: Backtest only over periods with clean, liquid, consistently-quoted price and volume data. Very long historical ranges on XAUUSD may include gold-standard-era pricing or unreliable volume that will distort results — the built-in date range inputs default to 2010 onward for this reason.
Position sizing: The default equity percentage is aggressive. Test at a lower size first and scale up only after reviewing max drawdown and worst losing-streak length for your specific test window — position sizing should reflect your own risk tolerance, not just backtest profit factor.
Shorting: Short entries exist as a toggle for experimentation, but are off by default based on backtest performance on gold's historical trend bias. Re-enabling changes the strategy's risk profile meaningfully.
Not financial advice: This is a backtesting and educational tool. Past performance on historical data does not guarantee future results.
策略

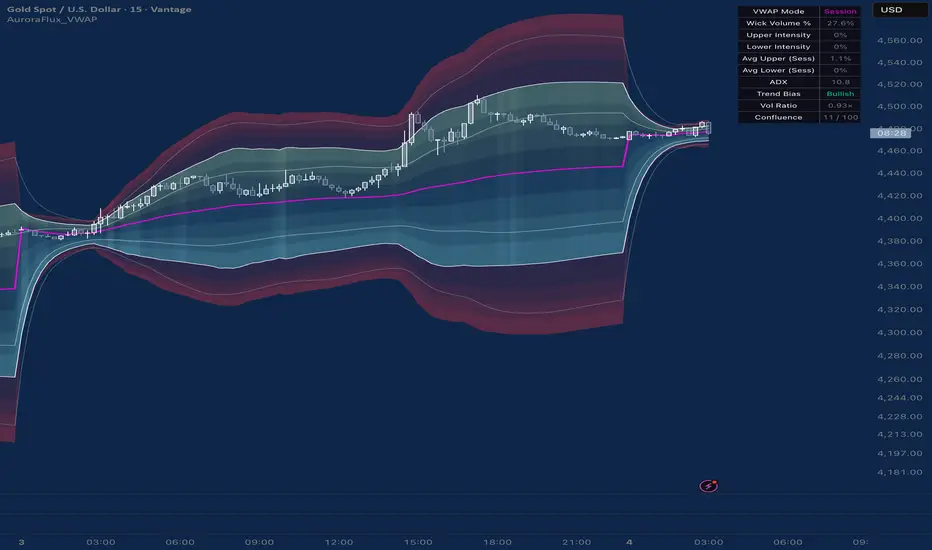
Aurora_FLux_VWAP_V2 (Drizzle_ALGO56)Aurora Flux is an adaptive VWAP system that combines volume-weighted price analysis, dynamic volatility envelopes, ADX trend filtering, and lower-timeframe wick volume analysis.
The indicator builds a volume-weighted VWAP core and expands its bands using both volume intensity and ADX strength. It then analyzes lower-timeframe data to measure how much volume occurred in the wicks versus the body of each candle. When strong wick volume coincides with price entering the outer zones, multi-layer intensity clouds light up to visualize buying or selling pressure.
The result is a clear visual map of rejection strength around the VWAP structure.
█ How It Works
⚪ Adaptive VWAP Core
Calculates either a Session VWAP or a Rolling VWAP together with volume-weighted variance. Band width is then modulated by two forces at the same time: current volume ratio and normalized ADX strength.
⚪ Wick Volume Analysis
Uses lower-timeframe data to split every chart candle into body volume and wick volume. A smoothed wick-volume ratio is calculated and used as the main intensity driver.
⚪ Intensity Mapping
When price enters the Extreme Zones (or the Main Channel depending on the selected mode), the current wick ratio is converted into an intensity value.
• Upper intensity reflects Sell pressure
• Lower intensity reflects Buy pressure
The intensity directly controls the opacity of the multi-layer clouds.
⚪ Session Average Tracking
A running average of Upper and Lower intensity is maintained throughout the session and displayed in the Dashboard. This shows the dominant rejection bias of the day.
█ How to Use
⚪ Identify Rejection Zones
Strong Extreme Zone clouds highlight price areas where high wick volume rejected the move.
These zones can act as high-quality support or resistance.
⚪ Read Buy vs Sell Pressure
• Rising Upper Intensity = increasing Sell pressure
• Rising Lower Intensity = increasing Buy pressure
Compare the current intensity with the Session Average to judge whether the rejection is stronger or weaker than the day’s average.
⚪ Combine with ADX
When ADX is high, the bands automatically widen. This reduces false signals during strong trends and keeps the focus on mean-reversion environments.
⚪ Classic Stdev Bands
Optional multi-level standard deviation bands can be enabled for additional fixed statistical reference levels.
█ Settings
• VWAP Mode (Rolling / Session)
• Base Deviation Multiplier & Volume Expansion Factor
• ADX Length, Smoothing and Band Multiplier
• Cloud Mode (Extreme Zone / Main VWAP / Both)
• Extreme Zone Offset & Width
• Main Channel and Extreme Zone colors (single color → automatic gradient)
• Automatic or Manual Lower Timeframe
• Wick Volume Ratio Threshold
• Dashboard HUD
█ Development Status
This indicator is still experimental and under active development.
Default settings are a starting point. Optimal results usually require manual fine-tuning of the Volume Expansion Factor, ADX Influence, Wick Threshold and Zone Width depending on the instrument and timeframe.
█ Feedback
Found a bug, have a suggestion, or want a specific improvement?
Feel free to reach out via TradingView private messages or leave a comment under the script. Feedback is highly appreciated.
█ Disclaimer
The content provided in this script is for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or a solicitation to buy or sell any financial instruments. Past performance is not indicative of future results. All trading involves risk, and you are solely responsible for your own trading decisions. 指标

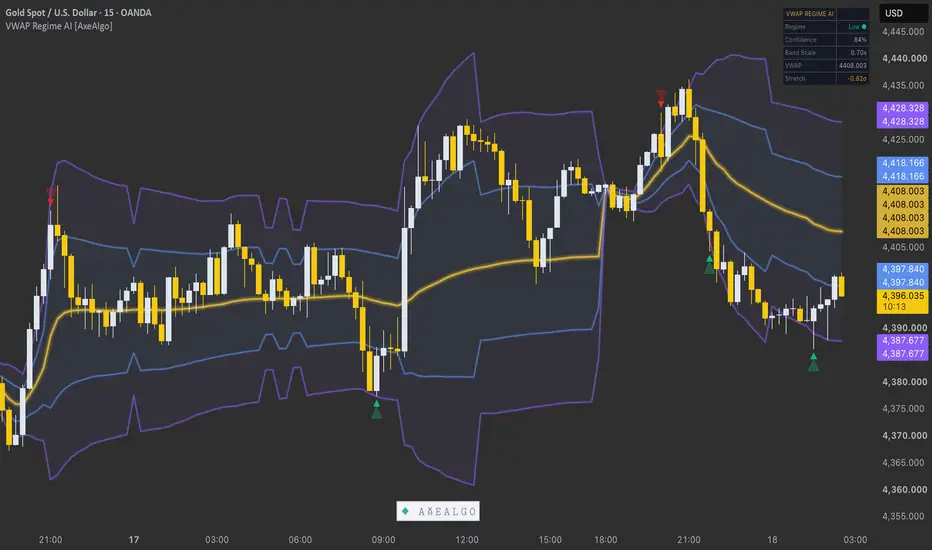
VWAP AI - Statistical Bands & Touch Stats [Dots3Red]⚓ VWAP AI - STATISTICAL BANDS & TOUCH STATS
VWAP's standard deviation bands are treated more or less as reliable support and resistance — on faith. This script checks that faith against the actual chart in front of you: every band touch is graded, every break beyond a band is graded, and the results accumulate into a running, honest record.
✨ WHY THIS MATTERS
VWAP tells you the volume-weighted average price — where the "center of gravity" of trading has actually been. The bands around it are meant to show how far price typically wanders from that center before snapping back. But "typically" varies enormously by instrument, session, and market condition, and no plain VWAP tool tells you what's actually been happening on your chart.
This script tracks it directly:
📊 +1σ | 62% rejected (n=41)
That means 41 touches of the +1σ band have been recorded on this chart, and 62% of them resulted in price genuinely rejecting back toward VWAP. Measured history, not an assumption baked into the tool.
⚙️ HOW IT WORKS
⚓ Anchoring — VWAP resets at the start of each new period. Session is the classic intraday default; Week and Month extend the same logic to longer views. Custom Bar anchors once, permanently, to a specific historical point you choose — useful for anchoring to an earnings date, a gap, or any event you want to measure from, rather than the calendar.
📏 Two-tier statistical bands — Band 1 and Band 2 are both standard-deviation multiples of VWAP, computed from a proper running variance (not an ATR approximation). Defaults are ±1σ and ±2σ, both fully adjustable.
🎯 Touch grading — when price wicks into a band without closing beyond it, that's logged as a touch. Within a configurable window, it resolves as:
• Rejection — price moved back toward VWAP by a meaningful distance
• Break — price closed convincingly through the band
• Timeout — neither happened clearly enough to call
🔄 Break-to-reversion tracking — separately, when price actually closes beyond Band 1, the script watches whether that move reverts back toward VWAP or continues away from it. This answers a different question than touch grading: not "did the band hold," but "once it didn't, did price come back anyway?"
🔒 Non-repainting — all grading happens strictly on confirmed bars.
🧭 HOW TO USE
1️⃣ Check the band stats before treating a level as reliable. "+1σ: 71% rejected (n=38)" and "+1σ: 44% rejected (n=12)" look like the same line on the chart but mean very different things about how much to lean on it.
2️⃣ Use break-reversion stats to judge a breakout beyond VWAP's range. If breaks above Band 1 have reverted back 65% of the time on this chart, that's useful context before assuming a fresh breakout will keep running.
3️⃣ Read Price vs VWAP as the simplest possible bias check. Above VWAP means the average buyer today is in profit; below means the average buyer is underwater. It's a blunt but genuinely useful read on crowd positioning.
4️⃣ Let sample sizes build before trusting the percentages. Every stat shows its N= specifically so you can judge reliability yourself — a handful of touches is not yet a pattern.
5️⃣ Match the anchor mode to what you're actually measuring. Session for pure intraday structure, Week or Month for a longer view, Custom Bar when you want to measure from one specific moment forward.
⏱️ WHICH TIMEFRAMES WORK BEST
Session-anchored VWAP is fundamentally an intraday tool — it was built for, and is most meaningful on, timeframes where a full session contains enough bars to form a real distribution: 1-minute through 1-hour is the classic and most effective range, which is exactly where VWAP sees the heaviest institutional and day-trading use.
On daily or weekly charts, a Session anchor resets so frequently relative to the bar size that it stops being meaningful — you'd see very few bars per session. For higher-timeframe or swing-style use, switch the anchor to Week, Month, or Custom Bar instead, so the accumulation window actually spans enough bars to produce a meaningful VWAP and band structure.
The touch and break statistics also need enough occurrences to mean anything — a fast-moving intraday chart will accumulate a useful sample size in days; a slow higher-timeframe anchor will take considerably longer.
🛠️ SETTINGS
⚓ Anchoring — Session / Week / Month / Custom Bar, source price
📏 Bands — Band 1 and Band 2 standard-deviation multipliers, Band 2 visibility toggle
🎯 Touch Statistics — Touch Tolerance, Rejection Distance, Reversion Distance, Outcome Window
🎨 Visualization — independent Band 1 / Band 2 touch marker toggles, Dot or Triangle marker style, marker size, VWAP and band line widths, independent fill transparency per band tier
🎨 Colors — VWAP line, Band 1 lines, Band 2 lines, upper/lower touch markers, Price Above/Below VWAP indicator, and full dashboard color control (background, border, header, row styling)
🖥️ Dashboard — show/hide, position — current VWAP value, price position, all four band stats, and both break-reversion stats in one place
📝 NOTES
Statistics accumulate from when the indicator is added to the chart and reset only when explicitly cleared by reloading. A Custom Bar anchor never resets on its own, it measures continuously from the point you chose. Band 2 statistics take meaningfully longer to build a useful sample than Band 1, simply because price reaches ±2σ far less often than ±1σ.
⚠️ DISCLAIMER
This is an analytical and visualization tool. It does not generate trade signals and does not constitute financial advice. Historical rejection and reversion rates do not guarantee future performance. 指标

MTF VWAP + POC Fan### What it does
Seven fixed-lookback windows on one anchor timeframe. Each window draws a VWAP curve — where the average participant's cost sits over that span — and can optionally draw a POC, the single price bin inside that same window that traded the most volume.
Same window, two different questions:
- **VWAP** — what the average participant paid
- **POC** — where participation actually concentrated
A dashboard reads the seven VWAP endpoints and scores the structure they form.
Default ladder is a daily one: **21 / 63 / 126 / 189 / 252 / 378 / 756** bars — roughly one month through three years. The anchor timeframe is configurable, so the same ladder on Weekly becomes five months through fourteen years.
### Why fixed lookbacks instead of swing anchors
Anchoring a VWAP at a swing high or low answers a real question — "what has been paid since that event" — but those anchors collapse into each other as windows grow. If price has not exceeded its three-month high, then the six-month, twelve-month and three-year highs are all the same bar, and several rungs draw one curve.
Fixed-lookback anchors cannot collide. The bar 252 back and the bar 378 back are always different bars, so seven rungs always mean seven distinct windows. That property is what makes a seven-horizon fan worth drawing at all.
### Reading the curve correctly
This is the part most multi-window VWAP scripts leave ambiguous, so it is worth being explicit.
At its **right edge**, VW252 equals the VWAP of the last 252 anchor-TF bars. That endpoint is the number.
The **tail behind it is not a rolling 252-bar series.** Every point on the drawn curve is the accumulation from the origin that is 252 bars back *today*, so the midpoint of the line is roughly a 126-bar average. The curve does not show what VW252 read on those past dates — on any past date it was anchored 252 bars before *that* date, at a different origin entirely.
The tail is one accumulation path from today's origin. Read historical crossings with that in mind.
### How the VWAP is calculated
Standard volume-weighted mean of the source (default HLC3) from the window's origin bar to its end bar, accumulated over **chart** bars. Origins are located on the anchor timeframe, then resolved to the exact chart bar by binary search.
When volume is missing or zero the engine substitutes 1.0, and tracks the substitution rate **per window**. Two different failures hide under one symptom:
- Missing on nearly every bar (synthetic symbols, some indices) — every bar weighs the same, so the curve is an *unweighted* mean of the source. Usable if you know that is what you are reading.
- Missing on a handful of bars in a real feed — a bar weighing 1.0 against neighbours weighing millions is not averaged in, it is effectively *dropped*. Still a proper volume-weighted mean, over a slightly smaller sample.
Curves whose own window exceeds the warning rate are suffixed with `*` and counted on the dashboard.
### How the POC is calculated
The window's high-low range is divided into bins, and each bar's volume is allocated **in proportion to how much of that bar's range overlaps each bin.**
The obvious shortcut — splitting a bar's volume equally across every bin it touches — is wrong at the edges: a bar with 2% of its range in one bin and 98% in the next would contribute 50/50. Since the POC is an argmax rather than an average, that error does not wash out. It can hand the win to the wrong bin.
Fully covered interior bins are accumulated with a difference array (one increment at the low edge, one decrement at the high edge, resolved in a single prefix sum) rather than a per-bin loop, which keeps the cost at O(bars + bins).
Three deliberate constraints:
**Resolution is capped at one bin per tick.** The bin-count input is a *maximum* resolution, not permission to invent sub-tick precision. If a window's whole range spans forty ticks, a hundred bins would put several bins inside one tick and the argmax would be choosing between prices that cannot trade. The reported level is also snapped to the instrument's tick grid, because an unrounded one-tick bin from 10.00 to 10.01 reports 10.005.
**Bin width is per window.** Each window divides its *own* range, so a P756 bin can be several times wider than a P126 bin. Two POCs landing on the same price are not confirming each other to the same tolerance. Each label's tooltip prints its bin width — read the level as the centre of that band, not as a price.
**POC is suppressed, not flagged, when volume is substituted.** A VWAP with missing volume degrades into an unweighted mean, which is still a usable number. A profile with missing volume becomes a bar-*count* histogram, whose peak answers where price spent the most bars regardless of size traded. That is a different statistic wearing the POC's name, so above a threshold nothing is drawn and the dashboard names the reason.
### Why POC is drawn forward, not backward
By default a POC starts at the last calculated bar and extends right. It is not drawn back across the window it was computed from.
A VWAP tail is a continuous accumulation with a value at every bar. A POC is a single number recomputed every bar with no value anywhere but now. Drawing both back to the same origin would make one line a genuine path and the other a snapshot impersonating one — the same visual gesture carrying two different truth-values, which teaches the wrong reading and creates hindsight support that was never there.
`Window + Forward` is available when you want to see the span, with the understanding that the backward segment is decoration.
Related: a POC **jumps**. It is an argmax, so when a different bin overtakes the leader the level teleports. A POC that sat at 70k yesterday and prints 62k today is not a data error — it is a window with two shelves close in volume. The single line cannot tell you that, which is the honest limitation of showing a POC without its profile.
### The visual grammar
- **Colour = horizon identity**, fixed per rung, never reassigned when other rungs are toggled. 252 is gold whether seven rungs are on or two.
- **Solid, width 2 = VWAP**
- **Dashed, width 1 = POC**, same colour as its VWAP
There is deliberately no horizon-based transparency and no colour-by-price-position. Fading short horizons fought the pairing and restyled everything on every toggle. Colour-by-price-position was redundant with the chart itself — whether a VWAP is above or below price is visible by looking at it — and spending the colour channel on it meant colour was unavailable for identity.
The palette is a cool progression (aqua → light blue → blue → lavender → **gold at 252** → violet → deep purple) so the fan reads as one instrument rather than seven unrelated indicators. Gold breaks the ramp deliberately, because 252 is the horizon most often referenced. Green and red stay out of the palette on purpose: they belong to the candles, and to the dashboard.
The script declares `scale=scale.none` so a distant 756-bar VWAP cannot drag the price axis and compress the candles you are actually trading.
### Seven VWAPs, three POCs
All seven VWAPs ship on. Seven ordered curves read fine, and where they bunch is itself information.
POCs are opt-in per rung, defaulting to **126 / 252 / 756** only — medium-term, annual, multi-year. Seven horizontal levels crowd a chart in a way seven curves do not. P189 and P378 are one click away. Global `Show VWAPs` and `Show POCs` switches let you inspect either family alone.
### The structure dashboard
A 0–100 read on where price sits relative to the fan and whether the fan is ordered.
```
STRUCT 88
P>VW 7/7
STACK +5/6
BIAS STRONG BULL
P>POC 3/3
```
**Price position — 50 points.** How many VWAP endpoints price is above, as a fraction of the drawn rungs, times 50.
**Stack — 50 points.** The adjacent-pair ordering, short over long. Each of the six adjacent pairs scores +1 when the shorter window sits above the longer, −1 when inverted, 0 when they are inside an equality tolerance. Raw range −6 to +6, rescaled to 0–50.
The dashboard shows the **signed raw total** (`+5/6`, `0/6`, `−4/6`) rather than a count of bullish pairs, because that signed number is literally what enters the score. Five bullish plus one tied and five bullish plus one inverted are different fans that a bullish-pair count would render identically.
The tolerance is normalised by the **anchor timeframe's** ATR, not the chart's — otherwise the same daily fan would classify two near-identical VWAPs as tied on a 130m chart and ordered on a 39m one, purely because the chart-TF ATR is smaller.
| Score | Bias |
|---:|---|
| 85–100 | Strong Bull |
| 70–84 | Bull |
| 55–69 | Bull Lean |
| 45–54 | Neutral |
| 31–44 | Bear Lean |
| 16–30 | Bear |
| 0–15 | Strong Bear |
`P>POC` is context only and does **not** enter the score. A volume concentration is a location, not a direction.
### What the score is not
Worth stating plainly, because a 0–100 number invites more confidence than this one has earned.
**The two components are not independent.** Price above every VWAP and a perfectly stacked fan are largely the same market condition seen twice — in a sustained one-way move both max out together, in chop both sit near their middles. Treat 0–100 as one structural reading measured two ways, not as a composite of separate evidence. The extremes are easier to reach than a two-component construction suggests.
**Stack ordering is partly mechanical.** These windows are nested — VW21's bars are a subset of VW63's, which are a subset of VW126's — so in any monotonic trend the ordering *follows* from the trend rather than confirming it independently. Where it earns its keep is at turns, when the short end inverts while price position is still high. That divergence between the two rows is more informative than the combined number.
**It is a step function.** With seven rungs, price position moves in jumps of 7.14 and stack in jumps of 4.17. The reading can cross the entire neutral band between two bars without ever printing a value inside it. Small changes are not drift.
**The score is withheld when horizons are missing.** Unless every enabled rung produced a VWAP and no two rungs share a lookback, STRUCT and BIAS print `—` and a `check` row names the reason. Normalising over whatever horizons happened to exist would let a two-horizon symbol print `STRUCT 100 / STRONG BULL`, indistinguishable at a glance from a seven-horizon reading.
Practical consequence: on a symbol without 756 anchor bars of history, the score stays blank until you turn VW756 off. That is deliberate. Disabling the rungs a symbol cannot support makes the reading an explicit statement about which horizons you are using.
### Confirmed Bars Only
With this off (default), windows extend through the current chart bar and update live.
With it on, **both ends** move to completed bars: lookbacks shift back one anchor bar, and all accumulation — VWAP, POC, the dashboard's reference price, and the stack tolerance's ATR — stops at the last chart bar of the last completed anchor candle. The fan then stops moving intraday entirely, which is what the switch should mean. Labels still sit at the chart's right edge while the values belong to the last completed candle; that gap is the point of the switch.
### Settings worth knowing
- **Anchor Timeframe** — the timeframe every lookback is counted in. Must be at or above the chart timeframe. Every anchor timeframe wants its own ladder; the defaults are a daily one.
- **Profile Bins** — maximum POC resolution, capped at one bin per tick.
- **Stored Chart Bars** — an origin must fall inside stored history or its rung is dropped, not approximated. Default 10,000 because 756 daily bars on a 39m chart is roughly 7,500 chart bars.
- **Dim rungs far from price** — optional, off by default. Fades a rung whose VWAP is beyond a set ATR distance. The whole rung dims together so a pair never splits into one bright line and one faint one. Try `scale.none` alone first.
- **Update Mode** — Live redraws every tick, which is necessary rather than wasteful: Pine destroys drawing objects created on an uncommitted tick, so on the forming bar a redraw every tick is the only way curves stay on screen. On Bar Close draws only on committed executions. Use it, or turn POCs off, if the profile passes trip the calculation time limit.
- **Show Diagnostics Panel** — full accounting of rungs, drawn objects and failure reasons. Off by default; anything genuinely wrong still surfaces on the dashboard's `check` row.
### Known properties
**Chart-timeframe sensitivity.** Origins come from the anchor timeframe, but accumulation uses chart bars, so the same daily setup gives slightly different values on a 39m chart than a 130m one. For the VWAPs this is second order — averaging washes out coarse bucketing. For the POC it is not: an argmax does not average, and a coarse bar spreads its volume uniformly across a range it never traded uniformly through. Expect the POC to shift by a bin or two between chart timeframes, more on symbols with frequent wide-range bars.
**Duplicate lookbacks are counted, never merged.** Two rungs set to the same number draw two identical curves in two colours, which looks like two horizons agreeing and is really one horizon entered twice. The dashboard flags it and withholds the score.
### Why VWAP and POC live in one script
They are computed from the same window definition. Splitting them would mean two indicators independently re-deriving identical origins, and would make it impossible to guarantee that P252 and VW252 cover exactly the same bars — which is the entire point of reading them as a pair. The dashboard reads only the VWAPs; the POC family is excluded from it precisely because it answers a non-directional question.
---
*This is a structural reference tool, not a signal generator. Nothing here produces entries, exits or alerts, and no part of it is a claim about future prices. Published open source so the calculations can be checked rather than taken on trust.*
指标

VWAP DeltaVWAP Delta is an oscillator that plots each bar's open, high, low and close as their distance from the volume-weighted average price, instead of showing price and VWAP side by side. It's built for anyone who wants to see how far, and how consistently, price is trading away from its volume-weighted average — for example to judge how stretched an intraday move already is, or how a recent push compares to the pace of previous ones — rather than only whether price sits above or below VWAP.
The delta of each bar is measured against an EMA baseline built from the delta close, and both can optionally be smoothed with a Hull moving average before that comparison. Because VWAP accumulates from the start of each session and depends on volume, it is an intraday tool and returns na on symbols or timeframes where volume data isn't available. The indicator can display this relationship as a filled area or as its own set of candles, with colors that adapt automatically to the current bias and, in candle style, to whether momentum is currently building or fading.
Calculation
VWAP Smoothing: applies a Hull moving average to the delta series before plotting, with an adjustable length.
Baseline Length: EMA length of the baseline that the delta is compared against.
Appearance
Graphic Style: visual style for the delta series: Area or Candle.
Bull / Bear Area Color: (Area style) fill color for when the delta line is above its baseline, and for when it's below.
Bull Candle Color: (Candle style) two colors for a bullish candle body — the left one while the body is expanding versus the previous bar, the right one while it's contracting.
Bear Candle Color: (Candle style) the same pair of colors for a bearish candle body.
In Area style, the delta close is plotted as a single line against its EMA baseline, and the space between them is filled — in Bull Area Color while the delta line is above the baseline, in Bear Area Color while it's below. Only the fill is visible; the delta and baseline lines themselves stay hidden. In Candle style, the fill disappears and the delta is drawn instead as its own set of candles, built from the delta's open, high, low and close relative to VWAP; when smoothing is enabled, the high and low are clamped to the smoothed open and close, so the smoothing itself can never invert a candle's body. Each candle is colored by comparing its own delta open and close: a candle whose delta close sits above its delta open takes a bull color, any other candle — including one where open and close are exactly equal — takes a bear color; within each of those two colors, the shade further distinguishes whether the current body is larger than the previous one (expanding) or smaller (contracting). A zero line marks where price and VWAP coincide.
This indicator is intended solely for market analysis and does not constitute investment advice or a guarantee of success. Use it at your own discretion and risk; past results are not indicative of future performance. 指标

Gypsy VWAP Map v0.30 Premium TradingView Req.Gypsy VWAP Map is a descriptive spatial map built around session-anchored VWAP. It is designed to show how price occupies and traverses recurring VWAP-relative displacement regions—not to generate buy/sell signals or predict reactions.
VWAP can reset at the Globex, London, and/or New York session anchors. I personally use all three, there is also an option for just NY + Globex.
The automatic map learns four independent relationships:
• Above VWAP — Adaptive
• Above VWAP — Persistent
• Below VWAP — Adaptive
• Below VWAP — Persistent
Adaptive relationships emphasize newer evidence and can migrate more quickly when recent excursion behavior changes. Persistent relationships retain more historical evidence and adjust more slowly. Adaptive does not necessarily mean nearer, and Persistent does not necessarily mean farther; the relationships may converge, diverge, overlap, or cross.
There are manual entries for static lines away from VWAP, I change these every once in a while to match current price action (like once a day maybe) but the defaults are a good starting point. Previously the top and bottom lines were locked into the same interval, but separating them allows mapping of nonidentical relationships relative to vwap.
Compare mode combines the automatic relationships with independently configured Manual boundaries. All available boundaries are sorted by their actual distance from VWAP. The colored fields represent fixed spatial intervals between those boundaries, rather than the identity of any particular line or a directional market opinion.
You can use only manual, only auto, or compare mode. Ironically Compare was made for testing, but I ended up liking both sets of lines so I use Compare exclusively.
Candle highs and lows determine which portions of the field have physically been reached. Automatic evidence is admitted only after its selected calculation bar closes. The indicator does not project future structures or complete shapes beyond observed price action.
The 1-second build uses a one-second main calculation stream, with Adaptive defaulting to 30-second evidence and Persistent defaulting to 1-minute evidence. It requires access to TradingView second-based data.
The 1-minute build requires no second-data access. Both Adaptive and Persistent relationships use confirmed one-minute evidence, producing a slower and more conservative map.
Changing indicator inputs causes TradingView to recalculate the loaded history using the new configuration. For consistent comparison, leave the native Calculation timeframe at the build’s designated value: 1 second for the 1S version or 1 minute for the 1M version. Personally I find 1s too busy, I generally use the 5s on a 5s and 5m chart.
This indicator is intended as a neutral framework for studying VWAP-relative market behavior alongside the user’s own structure and analysis.
v0.30
• Promoted the tested Adaptive/Persistent research model to the production 1S and 1M builds.
• Replaced the earlier Near/Far automatic model with four independently learned relationships.
• Added stable spatial color ranking in Compare mode.
• Overlapping boundaries now retain their ranking positions without recoloring or stretching farther zones.
• Added separate high-resolution 1S and broadly compatible 1M versions. 指标

Gypsy VWAP Map v0.30 1M NonPremium TV versionGypsy VWAP Map is a descriptive spatial map built around session-anchored VWAP. It is designed to show how price occupies and traverses recurring VWAP-relative displacement regions—not to generate buy/sell signals or predict reactions.
VWAP can reset at the Globex, London, and New York session anchors. I personally use all three, there is also an option for just NY + Globex.
The automatic map learns four independent relationships:
• Above VWAP — Adaptive
• Above VWAP — Persistent
• Below VWAP — Adaptive
• Below VWAP — Persistent
Adaptive relationships emphasize newer evidence and can migrate more quickly when recent excursion behavior changes. Persistent relationships retain more historical evidence and adjust more slowly. Adaptive does not necessarily mean nearer, and Persistent does not necessarily mean farther; the relationships may converge, diverge, overlap, or cross.
There are manual entries for static lines away from VWAP, I change these every once in a while to match current price action (like once a day maybe) but the defaults are a good starting point. Previously the top and bottom lines were locked into the same interval, but separating them allows mapping of nonidentical relationships relative to vwap.
Compare mode combines the automatic relationships with independently configured Manual boundaries. All available boundaries are sorted by their actual distance from VWAP. The colored fields represent fixed spatial intervals between those boundaries, rather than the identity of any particular line or a directional market opinion.
You can use only manual, only auto, or compare mode. Ironically Compare was made for testing, but I ended up liking both sets of lines so I use Compare exclusively.
Candle highs and lows determine which portions of the field have physically been reached. Automatic evidence is admitted only after its selected calculation bar closes. The indicator does not project future structures or complete shapes beyond observed price action.
The 1-second build uses a one-second main calculation stream, with Adaptive defaulting to 30-second evidence and Persistent defaulting to 1-minute evidence. It requires access to TradingView second-based data.
The 1-minute build requires no second-data access. Both Adaptive and Persistent relationships use confirmed one-minute evidence, producing a slower and more conservative map.
Changing indicator inputs causes TradingView to recalculate the loaded history using the new configuration. For consistent comparison, leave the native Calculation timeframe at the build’s designated value: 1 second for the 1S version or 1 minute for the 1M version. Personally I find 1s too busy, I generally use the 5s on a 5s and 5m chart.
This indicator is intended as a neutral framework for studying VWAP-relative market behavior alongside the user’s own structure and analysis. 指标

指标

VWAP Suite [vault]VWAP Suite
Most traders treat VWAP like a single line. This tool treats it the way Auction Market Theory treats it: as a developing value area with a center, an upper edge and a lower edge, tracked across every timeframe that matters, with the previous period frozen next to the current one so you always know where price sits relative to value.
Everything is inside one indicator. Session VWAPs from daily to yearly, standard deviation bands that form the value area, previous period levels, right side labels for every higher timeframe level, and rolling VWAPs over 7, 30, 90 and 365 days.
WHAT IT PLOTS
1. Session VWAPs (Daily, Weekly, Monthly, Quarterly, Yearly)
Each period has its own anchored VWAP that resets at the start of the period. The reset follows the exchange session of the symbol, not midnight UTC, so on CME futures a new daily VWAP starts at 18:00 New York, on OANDA gold at 17:00 New York, and so on. Weekly, monthly, quarterly and yearly resets follow the same logic.
You can enable any combination of these, each with its own color. By default the VWAP lines are drawn dotted so they do not compete visually with the bands and rolling lines. A "Dotted VWAP Lines" toggle switches them back to solid.
The lines break at the period change instead of drawing a vertical jump to the new starting level, so every session or week or month shows as its own clean block.
2. Standard Deviation Bands (Value Area)
Pick one period under "Anchored to Period" and the indicator draws its standard deviation bands around that VWAP:
- VWAP plus 1 SD = VAH (value area high)
- VWAP minus 1 SD = VAL (value area low)
- optional plus and minus 2 SD outer bands
The area between VAH and VAL is filled. Fill transparency is adjustable and defaults to a very subtle 95 so the band reads as a shadow behind price rather than a colored block.
The deviation is calculated with volume weighting from the same cumulative data as the VWAP itself, so VAH and VAL are the true volume weighted 1 SD edges of the developing value area. Bands also break at the period change.
3. Previous Period Levels
At the start of every new period the indicator freezes the VWAP and standard deviation of the period that just closed. Those frozen values are carried forward as flat lines through the current period:
- previous VWAP
- previous VAH and VAL (plus and minus 1 SD)
- optional previous plus and minus 2 SD
These are the levels that matter most from an Auction Market Theory point of view. Price opening inside the previous value area, above it, or below it tells you what kind of day or week you are likely dealing with. The previous value area can be filled as well, with a separate "Fill Prev Bands" toggle.
Each of the five periods keeps its own frozen values, so the previous weekly VAH is genuinely the VAH of last week, not of the last day.
4. HTF Labels (Weekly, Monthly, Quarterly, Yearly)
This is the part that keeps the chart clean. Instead of plotting eight or ten extra lines you get labels on the right side of the chart for the higher timeframe levels:
- current VWAP, VAH, VAL for each of W, M, Q, Y
- previous VWAP, VAH, VAL for each of W, M, Q, Y
Every single label has its own checkbox, so you can show exactly the ones you use and nothing else. Each period has its own color, and previous period labels are automatically dimmed so you can tell them apart at a glance. Two group switches, "Show Current Labels" and "Show Previous Labels", turn whole sets on and off.
Each label comes with a short horizontal tick line drawn at the price level, so you can see where the level sits even when the line itself is not plotted.
5. Rolling VWAPs (7, 30, 90, 365 day)
Rolling VWAPs do not reset. They always look back a fixed number of days and give you the volume weighted average of that whole window. They are calculated by time, not by bar count, so a 30 day rolling VWAP is the same 30 days whether you are on a 5 minute chart or a 4 hour chart. Each one has its own toggle, color and label.
Note on history: the 365 day line needs roughly a year of bars on your chart. On low timeframes with limited history it will be calculated from the first available bar. It is off by default for that reason.
LABEL CONTROLS
- Label Offset: how many bars to the right of the current bar the labels sit
- Label Size: tiny, small, normal or large
- Label Tick Length: length of the short line drawn in front of each label
- Show Right-Side Labels: one master switch that hides every label on the right in one click. Lines and fills stay. Useful when you want to screenshot a clean chart or when the labels start stacking up during a tight range.
HOW WE USE IT
The core idea is that VWAP is fair value for the period and the 1 SD bands are the edges of value. Price accepted inside the bands is balance. Price outside the bands is either an imbalance that will be faded back to value or the start of a trend that leaves the old value area behind.
A few things to watch for:
- Price opening the day or week outside the previous value area and holding there. That is acceptance away from old value and usually the start of a directional move.
- Price opening outside the previous value area and coming straight back inside. Failed breakout, look for a rotation to the other side of the value area.
- Daily VAH or VAL lining up with a weekly or monthly VWAP or value area edge. Stacked value edges from multiple timeframes are where the strongest reactions happen.
- Rolling 7D and 30D crossing or converging. That is medium term value shifting and it often precedes a larger move on the session timeframes.
The labels on the right are there so you never have to guess which level a line represents or scroll around to find the monthly VWAP.
CALCULATION NOTES
- Source is hlc3 by default and can be changed.
- VWAP is the volume weighted average of the source since the period start. Standard deviation is the volume weighted deviation of the source around that VWAP.
- Session boundaries come from the symbol's own exchange calendar.
- On symbols without volume (some CFDs and spot pairs), the indicator falls back to equal weighting so it still plots a time weighted average and bands rather than nothing.
- No repainting. Every value is computed from closed data and a period's frozen levels never change once the period has ended.
- Written in Pine Script v6.
INPUTS OVERVIEW
General: source, label offset, label size, label tick length, right side labels master switch
Session VWAPs: Daily / Weekly / Monthly / Quarterly / Yearly with colors, line width, dotted or solid
Standard Deviation Bands: on/off, anchored period, fill on/off, 2 SD bands on/off, colors, fill transparency
Previous Period Levels: prev 1 SD levels, prev 2 SD levels, prev labels, fill prev bands, color
HTF Labels: current / previous group switches, then per period color and six individual checkboxes (VWAP, VAH, VAL, pVWAP, pVAH, pVAL)
Rolling VWAPs: 7 / 30 / 90 / 365 day with colors
Works on any market and any timeframe. Built for futures and gold on intraday charts but the logic is the same on crypto, forex and stocks. 指标

Triple VWAP - Session Weekly MonthlyThis indicator as been tested in these assets
CAPITALCOM:GER40
CAPITALCOM:NAS100
CAPITALCOM:SPX500
Triple VWAP is a TradingView indicator that combines Session VWAP, Weekly VWAP and Monthly VWAP into one chart.
Each VWAP can be configured independently. The indicator supports standard deviation or percentage bands, with up to three customizable band levels. Source, offset, calculation timeframe, band visibility, fills and other settings can be adjusted separately for Session, Weekly and Monthly VWAP.
The 1 standard deviation bands can help identify areas of value, rotation and deviation from VWAP. Price holding around VWAP can indicate balance, while sustained movement outside the bands can provide context for momentum, acceptance and possible continuation.
The three VWAPs can also be used together to identify confluence between short-term and higher-timeframe value areas.
Example trade: GER40 5-minute chart.
In the example, price sold off into an area where the Weekly VWAP and Session VWAP were closely aligned. This created a higher-confluence support area.
Price reacted from the VWAP zone and began moving back above the levels. The long entry was taken after the bullish reaction and confirmation.
The setup was based on:
Price reaching the Weekly and Session VWAP confluence.
The area holding as support.
Price reclaiming the VWAP area.
Bullish confirmation before entering.
The VWAP itself is not treated as an automatic entry signal. The setup combines location, timeframe confluence, price reaction and confirmation.
This indicator is intended as a reference tool for market structure, value, mean reversion, support and resistance, and trend analysis. It should be used together with appropriate risk management and additional market analysis. 指标

Buyer vs Seller Control & Path of Least Resistance (MTF)Buyer vs Seller Control & Path of Least Resistance (MTF)
WHAT IT DOES
For every timeframe you care about (1 / 2 / 3 / 5 / 15 / 30 / 60 minutes by default) this overlay answers three questions on one comparable scale, right on your price chart:
• WHO is in control — buyers or sellers?
• HOW STRONGLY — a 0-100 strength meter per timeframe.
• Which way is the PATH OF LEAST RESISTANCE across all of them — UP, DOWN, or CHOP?
Your current chart timeframe is highlighted as "YOUR TF", so at a glance you see whether to be hunting longs or shorts on the exact screen you are trading — and the same read for every other timeframe beside it.
THE CONTROL SCORE — FIVE LENSES, ONE NUMBER
Each timeframe's control is a single signed value in (+ = buyers, − = sellers), fused from five independent lenses so no single measure dominates:
1. ORDER-FLOW DELTA (fast) — a Bulk-Volume-Classification (BVC) buy/sell split. Each bar's volume is divided into buying and selling using the standardized bar return through a normal CDF (Easley / López de Prado / O'Hara), then expressed as a net-over-gross balance ratio. Bounded, so it is comparable across symbols and timeframes.
2. CVD (slow) — the same signed-volume idea over a longer window, capturing persistent accumulation or distribution rather than the latest impulse.
3. VWAP — location of price relative to session VWAP (measured in ATR) plus the slope of VWAP.
4. MA STACK — the interrelation (stacking order) of a fast / mid / slow EMA plus the slope of the fast EMA.
5. VOLUME PRESSURE — close-location-weighted money flow (CMF-style).
Two microstructure adjustments then sharpen conviction:
• EFFORT vs RESULT (absorption) — when control is strong but price has barely progressed, the score is damped: the winning side is being absorbed.
• KYLE-λ IMPACT — a price-impact proxy (correlation of the size of the move with volume). Flow that actually moves price counts for more; volume that moves nothing counts for less.
STRENGTH — SELF-CALIBRATING, COMPARABLE ACROSS TIMEFRAMES
Strength (0-100) is the percentile rank of |control| within each timeframe's OWN recent history. A 1-minute chart and a 1-hour chart are therefore on the same scale: a high % means control is strong RELATIVE to what that timeframe normally does — not an absolute claim. This is what makes the seven rows directly comparable.
PATH OF LEAST RESISTANCE — A CALIBRATED, HONEST FUSION
The headline "PATH" is not a naïve vote count. It is built to avoid the classic multi-timeframe trap where several fast, highly-correlated timeframes all lean the same way and manufacture false confidence:
• LOG-ODDS FUSION — each timeframe's signed control, scaled by its own strength and by a √(timeframe-seconds) horizon weight, is combined as a weighted-mean in log-odds and mapped to a probability P↑ that buyers win the path. Because it is a mean, redundant timeframes form a consensus instead of stacking up.
• CORRELATION DISCOUNT — the average correlation between the timeframe control series is measured live; when the timeframes are merely echoing each other (highly correlated) rather than agreeing independently, the path conviction is shrunk.
• REGIME GATE — a Kaufman efficiency ratio on your chart measures trend vs chop; in a choppy, mean-reverting tape the path is gated toward CHOP so you are not handed a confident direction when the market has none.
The result is reported as ▲ UP / ▼ DOWN / = CHOP with a calibrated conviction %, how many timeframes agree, P↑ (probability up), ρ (inter-TF correlation) and the regime %.
FORWARD-TEST SELF-AUDIT (Pro table)
Turn on the "Pro" detail mode and the table shows a rolling HIT-RATE: how often the path direction from N bars ago was actually followed by price moving that way. It is computed only from confirmed PAST bars — no future leak — so it is an honest, symbol-and-settings-specific audit of the path, not a marketing number. Use it to sanity-check the settings on your instrument before you trust the signal.
REPAINT — READ THIS
• Default (live): higher-timeframe reads update intrabar as each higher-TF bar forms — the normal behaviour of any live multi-timeframe tool.
• "Freeze to last closed bar" (optional): every row shows the last CONFIRMED bar of its timeframe — non-repainting, but one bar behind.
• request.security is called with lookahead OFF (no future data is ever pulled back in time).
• Alerts evaluate on confirmed CHART bars; for fully non-repainting alerts (confirmed higher-TF reads), keep Freeze ON.
HOW TO USE IT
• Add it to any liquid, volume-bearing symbol and intraday timeframe.
• Read YOUR TF first — it is the actionable line for the screen you are on. BUY / SELL / WAIT with a strength meter.
• Then glance up at PATH: trade with the path, be cautious against it, stand aside on CHOP.
• Use AGREE (x/7) and the Pro ρ / regime / hit-rate stats to gauge how much to trust the read.
• Alerts: "Path flips UP", "Path flips DOWN", "Path goes CHOP".
Inputs are grouped: Score, Lenses & microstructure, Timeframes, Path fusion, Repaint, Display (Dark/Light theme, table position, Compact/Pro detail, background tint). All seven timeframes are user-selectable.
ORIGINALITY / WHY IT IS NOT A MASH-UP
The five lenses are deliberately chosen to measure control from independent angles (order flow, longer-horizon flow, value location, trend structure, money-flow pressure) and are fused with an absorption and price-impact overlay so that "loud but ineffective" pressure is discounted. The cross-timeframe path is a probabilistic log-odds consensus with an explicit correlation discount and a regime gate — specifically designed so that a cluster of correlated fast timeframes cannot fake a high-conviction reading, and so that chop is reported as chop. The built-in forward-test lets each user verify the behaviour on their own instrument.
LIMITATIONS / DISCLAIMER
This is an OHLCV-based study. The buy/sell split is a bar-level statistical estimate, not the true tape: it cannot see resting limit orders, the intrabar footprint, or off-book liquidity. Percentile strength is relative to recent history, not an absolute force. Multi-timeframe reads update intrabar unless Freeze is on. Works best on liquid, volume-bearing instruments; illiquid symbols or timeframes with little history may show "—".
This indicator is a decision-support study for context and education. It is NOT financial advice, NOT a signal service, and NOT a guarantee of future results. Markets involve risk; you are responsible for your own decisions and risk management.
指标

VWAP Regime AI [AxeAlgo]OVERVIEW
VWAP Regime AI is an anchored VWAP (Volume-Weighted Average Price) with
standard-deviation bands, enhanced by a native, from-scratch k-means
clustering engine that classifies recent market volatility into three
regimes — Low, Medium, and High — and adapts the indicator's behavior
based on which regime is currently active.
At its foundation this is the same tool institutional desks use every
day: a running volume-weighted average price with bands around it, used
to judge where "fair value" sits and how far price has stretched away
from it. What this script adds on top is a genuine unsupervised machine
learning step that reads the market's own volatility and lets that
reading drive three things: how wide the bands are, which signal logic
is active, and how much the indicator should trust its own regime call
before acting on it.
This script is free and open-source. All calculations happen natively in
Pine Script on your own chart data.
============================================================
FULL TRANSPARENCY ABOUT THE "AI" IN THIS SCRIPT
============================================================
Pine Script cannot call an LLM, a remote model, or any external AI
service — TradingView does not allow outbound network requests from
indicators, and this script makes none. There is no hidden API call,
no "black box," and nothing running outside of what you can read in the
source code.
What "AI" means here specifically: this script implements k-means
clustering — a well-established unsupervised machine learning algorithm
— entirely in native Pine Script math and arrays. It groups a rolling
window of recent ATR (volatility) readings into three clusters by
repeatedly assigning each reading to its nearest cluster center and then
recomputing each center as the mean of everything assigned to it. This
publication states plainly what is and is not happening so nobody
mistakes this for predictive AI, sentiment analysis, or anything that
consults external data or forecasts the future. It classifies what has
already happened; it does not predict what will happen next.
============================================================
HOW IT WORKS
============================================================
VWAP & Standard Deviation Bands
--------------------------------
The core VWAP resets at the start of each new anchor period (Session,
Week, Month, Quarter, or Year — configurable) and accumulates a running
volume-weighted average from there. Standard deviation is calculated
using the same volume-weighted variance formula TradingView's own
built-in VWAP-with-bands tool. Up to three bands can be shown,
each set at a configurable standard-deviation distance from VWAP.
AI Volatility Clustering (K-Means)
------------------------------------
A rolling window of recent ATR readings (length and window size are both
configurable) is periodically re-clustered into three groups — Low,
Medium, High — using k-means. Reclustering happens every N bars rather
than every single bar, purely for performance; the live classification
of the current bar still updates continuously between reclusters.
Alongside the classification, the script computes a Confidence score
(0-100%): how much closer the current reading sits to its nearest
cluster than to its second-nearest one. A reading sitting right on a
cluster's center scores near 100%; a reading sitting on the boundary
between two regimes — an effectively ambiguous call — scores near 0%.
A "Minimum Regime Confidence" input lets you require a minimum score
before the regime is allowed to influence anything else in the script,
so an unconfident, boundary-line classification doesn't silently drive
behavior.
Adaptive Band Width
----------------------
When enabled, the standard-deviation band multipliers are scaled by a
per-regime factor: tighter in Low volatility, wider in High volatility,
instead of one fixed multiplier that's too tight in some conditions and
too loose in others. This only engages once the AI is both ready
(its lookback window has filled and it has run at least once) and
confident, per the Minimum Regime Confidence setting above.
Signal Logic — Mean Reversion, Breakout, or Auto
----------------------------------------------------
Two independent signal styles are built in, both measured off Band 2:
Mean Reversion looks for price crossing back inside the band from
outside (betting an extreme move snaps back toward VWAP); Breakout looks
for price crossing outside the band (betting the move has momentum to
keep running). "Auto" mode lets the detected volatility regime decide
which logic applies bar by bar — Low/Medium volatility defaults to Mean
Reversion, High volatility defaults to Breakout — falling back to Mean
Reversion whenever the AI isn't ready or confident enough to trust.
Three independent, stackable filters reduce noise on top of the raw
band cross:
- Bar-Close Confirmation: a cross only counts once the bar has fully
closed, filtering out intrabar wicks that reverse before the close.
- Signal Cooldown: blocks a new signal, in either direction, for a
configurable number of bars after the last one — aimed directly at
whipsaw (price crossing back and forth across a band repeatedly).
- Band Cross Buffer (hysteresis): requires price to clear a band by a
small extra distance, in standard deviations, rather than an exact
touch, so noise sitting right on the line doesn't keep re-triggering
crosses back and forth.
AI Volume Confirmation Filter
---------------------------------
The same k-means engine used for volatility is optionally reused on raw
volume, classifying each bar's volume as Low, Normal, or High. When
enabled, signals are only allowed on Normal-or-above volume, filtering
out low-conviction moves.
Secondary VWAP
-----------------
An optional second VWAP anchored to a different (typically higher)
period can be plotted alongside the primary one — for example a Weekly
VWAP behind a Session VWAP — for confluence, since multiple VWAP anchors
are commonly watched together rather than trusting a single one in
isolation. It is a reference line only; no bands are drawn for it.
Signal Track Record
-----------------------
An on-chart scorecard tracks, in a simple and fully model-free way, how
the signals have actually performed: each signal opens a virtual
position at that bar's close, and the next opposite-direction signal
closes it out, scored as a win or a loss purely on which way price
moved in between. No target or stop-loss assumption is built into this
score — see the Limitations section below for exactly what this number
does and does not tell you.
Status Table
---------------
An optional on-chart table shows the current regime and its confidence,
the active band scale, the current VWAP value, a "Stretch Score" (see
below), and the Signal Track Record numbers, all in one place.
Stretch Score
----------------
A signed z-score of how many standard deviations price currently sits
from VWAP. Because it's measured in the same standard deviations the
bands are drawn in, it stays consistent with whatever the adaptive band
width currently has in effect — a reading of +2.00 always means "sitting
on Band 2," whether that band is currently tight or wide.
============================================================
HOW TO USE THIS INDICATOR
============================================================
1. Start with the default settings and watch the status table for a
while before changing anything. Let the AI Volatility Clustering
lookback window fill (the table will show "Calibrating..." until it
has enough data) so the regime classification is meaningful.
2. Decide whether you want Mean Reversion, Breakout, or Auto signal
logic. Auto is a reasonable starting point since it adapts to
detected conditions automatically.
3. Watch the Confidence score alongside the regime label. If confidence
is frequently low on your instrument/timeframe, consider raising the
Minimum Regime Confidence input so the indicator falls back to
neutral behavior more readily instead of acting on ambiguous calls.
4. Use the Stretch Score to judge how extended price currently is
relative to VWAP in a way that stays consistent even as band width
adapts.
5. Treat the Signal Track Record as a rough, ongoing sanity check on
signal quality — not a backtest and not a promise (see Limitations).
6. This is a visual/analytical tool, not an auto-trading system. It
does not place trades. Any alerts it can generate are notifications
only.
============================================================
INPUT GROUPS (SUMMARY)
============================================================
VWAP Settings
- Anchor Period (Session / Week / Month / Quarter / Year)
- Source price used for the VWAP calculation
Secondary VWAP (Confluence)
- Show/hide toggle, its own anchor period, and its own color
Standard Deviation Bands
- Independent show/hide and distance (in standard deviations) for
three bands, plus a toggle for the gradient fill shading around them
AI Volatility Clustering (K-Means)
- Enable/disable the clustering engine
- ATR length used as the raw volatility reading that gets clustered
- Clustering lookback window (bars) and reclustering frequency
- Number of k-means refinement iterations per reclustering
- Adaptive band width toggle and the three per-regime scale factors
- Minimum Regime Confidence threshold
Signals
- Show/hide signal markers
- Signal Mode (Mean Reversion / Breakout / Auto)
- Volume confirmation filter toggle
- Bar-close confirmation toggle
- Signal cooldown (bars)
- Band cross buffer (hysteresis, in standard deviations)
Visuals
- Regime background highlight toggle
- Status table toggle and Signal Track Record toggle
- Colors for VWAP, each band, each regime, and each signal direction
============================================================
REPAINTING & REAL-TIME BEHAVIOR
============================================================
This script does not use any higher-timeframe security() calls and does
not look ahead — every value at every historical bar is a function of
data available up to and including that bar. Once a historical bar is
confirmed, its VWAP, bands, regime classification, and signals do not
change on subsequent chart loads or reloads.
Like any real-time indicator, values on the currently forming (unclosed)
bar update as new price/volume ticks arrive, and will settle once that
bar closes — this is standard behavior for any live indicator, not
repainting of historical data. If you want signal markers to appear only
after a bar has fully closed rather than updating intrabar, keep the
"Require Bar Close Confirmation" input enabled (it is on by default).
============================================================
LIMITATIONS — PLEASE READ
============================================================
- The Signal Track Record is a simplified, model-free heuristic, not a
backtest. It ignores commissions, spread, slippage, position sizing,
and any stop-loss/take-profit logic, and it scores a "trade" purely by
whether price was above or below the entry price when the next
opposite signal fired. It exists to give a rough, ongoing sense of
signal direction quality — it is not a performance guarantee and
should not be relied on as one.
- K-means clustering, like any clustering method, can produce a
misleadingly high confidence score if recent volatility (or volume)
readings happen to be nearly constant for an extended window — a rare
condition, more likely on thinly-traded instruments, but worth being
aware of.
- Regime classification and adaptive behavior depend on the Clustering
Lookback window filling with data first; expect "Calibrating..." on a
freshly loaded chart or a short history until then.
- This is a discretionary analysis tool intended to support your own
judgment, not a mechanical, guaranteed-signal system. No combination
of settings eliminates false signals entirely, which is why several
independent, adjustable filters (bar-close confirmation, cooldown,
hysteresis buffer, volume confirmation, regime confidence threshold)
are provided rather than relied on individually.
============================================================
RISK DISCLAIMER
============================================================
This script is provided for educational and informational purposes
only. It is not financial advice, and it is not a recommendation to buy
or sell any security or instrument. Trading and investing involve
substantial risk of loss and are not suitable for every investor. Past
performance — whether real, simulated, or shown via the on-chart Signal
Track Record — is not indicative of future results. Always do your own
research and consider consulting a licensed financial advisor before
making trading decisions. Use this indicator, and any alerts it
generates, entirely at your own risk. 指标