Confluence Engine+Confluence Engine+
Maps the PD arrays taught by ICT. Instead of plotting a dozen isolated objects and leaving you to weigh them by eye, it reads the confluences present at price — a liquidity raid into a discount PD array, confirmed by a breaker, with SMT, inside a killzone — into the ICT directional bias, the current draw on liquidity, and a corner dashboard. It reports context and leaves the trade to you. It is not a signal generator: it does not fire buy or sell orders and it does not place entries or exits.
What it does
Six modules, each toggleable, built so later stages read the state the earlier ones capture.
1 · Killzones & Sessions. Time-gates the London, NY AM and NY PM killzones and marks the Asia, London and New York session highs and lows as unmitigated levels, plus the 00:00 New York Midnight Open — a core daily reference (below it leans the day bullish, above it bearish). Every time window here — the killzones included — is resolved on the session source timeframe rather than the chart's. A killzone is ninety minutes to three hours, narrower than a single higher-timeframe candle, so judged off the chart a candle merely overlapping one would report as fully inside it. The killzone is read at the candle's close, and the Midnight Open the same way, so it still resolves on charts whose own candles never open at 00:00.
2 · Structure & Dealing Range. Pivot highs and lows define the swing structure the arrays build on. The dealing range — the window whose midpoint separates premium from discount — is taken from a fixed higher-timeframe period: the weekly range on 1-hour-and-up charts, the daily range on anything intraday below that.
3 · Liquidity. Session highs and lows (Asia, London, New York) plus prior day and prior week highs and lows are drawn as reference liquidity, each anchored to the candle that formed it. Session extremes are measured on a lower timeframe rather than the chart's: a three-hour London window is shorter than a single 4-hour candle, so read off the chart it would collapse to the high of whichever candle happened to contain it. Sourcing them lower keeps session levels correct on any chart, and charts already at or below that timeframe track natively.
A level tracks the right edge while it rests; the instant price touches it, it is mitigated — the line stops extending at that candle, turns dotted and dims — so taken liquidity stays readable as history and can never be mistaken for a live level. Where levels land close together only the most significant is drawn, a weekly level outranking a prior-day level, which outranks a session level, so near-duplicates never stack. Each level then retires once it ages past its lookback window: the "back" settings are a window in days and weeks, so nothing lingers long after the session or period that formed it.
4 · PD Arrays. Fair Value Gaps (BISI / SIBI), Volume Imbalances, Order Blocks (the candle body before a displacement) and the Order-Block-to-Breaker lifecycle. A FVG registers only when the gap clears a height floor and its middle candle is a genuine displacement candle, so routine three-bar gaps are filtered out. A Volume Imbalance is the FVG's thinner cousin — a two-candle gap between the bodies that a wick still trades through, so the only volume in the gap changed hands in wicks; it carries its own sensitivity floor and lives under the same lifecycle as the FVGs. A new gap also removes any stale opposite-direction gap it overlaps: that range has since been delivered through the other way, so the old one-sided imbalance cannot stand.
An Order Block must earn its place with the full ICT sequence: the close that breaks the prior swing — a structure break grants that credit exactly once, so blocks sit at real breaks rather than printing mid-trend — and the leg must leave a Fair Value Gap behind it. The gap is the displacement evidence: a leg that never gaps did not really displace, and its block never registers. Only the order blocks that matter make the chart. A live block is the body of its origin candle, open to close. When price closes through it the block fails and flips into a Breaker — and a breaker takes the full candle, wick to wick: the displacement behind it is already proven, so the whole candle becomes the array. A percentage-fill mitigation decider governs each array: once price trades a chosen depth into it from the side it is approached from (default 50%, consequent encroachment), the array is mitigated — either faded and kept (dotted, faint, check mark) or removed, whichever you set. A largest-array-wins declutter keeps overlapping zones from stacking.
5 · SMT Divergence. A liquidity-sweep read against a correlated symbol — auto-paired (NQ to ES, ES to NQ, YM to ES, GC to SI, and their micros) or a symbol you set. When your chart takes a swing level but the peer holds its aligned level and refuses to follow, the move lacks participation: a SMT is drawn from the swept level to the sweep. Pooled swings age out after a set number of bars, so a divergence is only ever drawn between swings that were still contemporaries — never between two that are days apart.
6 · Dashboard. A pure confluence read-out of the state each module captures — the ICT bias, and the current draw on liquidity : the nearest unmitigated high above (the resting buyside) and the nearest unmitigated low below (the resting sellside), each named with its distance — where price is being drawn to, read straight from the level engine. When liquidity is taken, the sweep row names the level that was raided — PDH, PDL, a session high or low — rather than a generic flag. Below that, whichever confluences are live (a OB or Breaker tap, a SMT), the killzone, the Midnight Open and the dealing-range position — every row a decision input, nothing that is merely inventory. It reports context; the trade is left to you, and nothing fires.
Visual grammar
Order blocks and breakers draw as levels by default, the way a block is actually read: the proximal edge — the price that gets traded — a solid line in the direction colour, the distal edge dotted, the consequent encroachment dotted grey between them, and a small tag at the right end that renames itself from OB to Breaker when the block flips. Prefer the block as a region instead and one setting draws it as a see-through zone with a hard border. A live gap zone is solid with its label travelling at the live edge; once a zone is mitigated to the chosen fill depth it turns dotted, fades, and its name folds into the zone itself — a faint "✓ name" carried inside the frozen box, quiet by design, so worked zones read as history at a glance. A liquidity level extends while it rests and freezes into a dotted line the moment it is taken — full-strength black by default, with an optional dim. Purple marks bullish arrays, magenta bearish; liquidity and levels are neutral. Nearby level labels merge so the chart stays readable, and objects project a few bars past the last candle so labels sit in clear space, never on price.
Method & repainting
Every detection path — liquidity capture, PD-array formation, mitigation and SMT — evaluates only on closed bars, so nothing is drawn, moved or removed on the strength of an unfinished candle. Once a level, zone or SMT line is on the chart it stays where it was placed. Completed period levels fix at the rollover, and session extremes are read from the closed intrabars of the session source timeframe.
Two things update live, by design. The dashboard reads current price, so the bias and draw rows move during the forming candle and settle at its close; and the right-edge labels re-merge as levels are added or taken. Neither creates or moves a drawn object.
Swing-based features — the order-block structure break and SMT — depend on pivots, which confirm a set number of bars after the swing itself forms. That is a fixed delay, not a revision: a pivot never moves once printed. Session levels also rely on lower-timeframe data, which is available for a limited span of recent history, so they thin out far back on the chart.
Settings
Session timezone, session windows and the session source timeframe, per-array sensitivities and the mitigation decider, block drawing mode (levels or zone), the SMT peer and liquidity memory, and full dashboard controls are all exposed as inputs.
Disclaimer
This is a decision-support tool for discretionary ICT trading. It is not financial advice, and no market's past behaviour is indicative of future results. אינדיקטור

Fibonacci Path Profile [MantisAlgo]Fibonacci Path Profile is a historical swing-path analysis tool that compares the active market structure with similar Fibonacci swing patterns from the past and visualizes the historical distribution of the next D and E swing points.
The indicator combines the current A→B impulse, B→C retracement or extension, and live C→Now progress to continuously refine the historical sample.
🟢 ABC STRUCTURE
The indicator automatically detects alternating swing highs and swing lows and organizes them into an A-B-C structure.
Bullish ABC
A→B = upward impulse
B→C = downward retracement
The next D swing develops upward from C
Bearish ABC
A→B = downward impulse
B→C = upward retracement
The next D swing develops downward from C
A→B is used as the base swing for all subsequent Fibonacci measurements.
🟢 FIBONACCI MATCHING
The B→C movement is measured relative to the A→B impulse:
B→C Ratio = |B − C| / |A − B|
Historical cases are matched using:
Bullish or Bearish ABC direction
B→C Fibonacci range
Live C→Now progress
The B→C ranges are:
0–23.6%
23.6–38.2%
38.2–50%
50–61.8%
61.8–78.6%
78.6–100%
100–127.2%
127.2–161.8%
161.8%+
Up to 100% is classified as a Retrace, while values above 100% are classified as an Extension.
* To preserve a usable historical sample, all B→C values above 161.8% are grouped into a single 161.8%+ matching range rather than being divided into additional extension classes.
🟢 LIVE C→NOW MATCHING
The indicator also measures how far the active move has progressed from C relative to the B→C range.
C→Now = current progress from C relative to |B − C|
As price develops, this progress is used to filter historical cases that remained valid through a similar stage of the move.
🟢 D & E PATH
The profiles show the historical locations of the next two swing points:
D PathDistribution of the next swing point after C.
E PathDistribution of the following swing point after D.
Both D and E locations are normalized relative to the B→C range, allowing historical structures of different absolute sizes to be compared on the same basis.
The E Path is also separated into three structural outcomes:
🟥 B Break — E moves beyond the B level
🟨 No Break — E remains between B and C
🟦 C Break — E moves beyond the C level
The displayed percentages represent the weighted share of each outcome among the currently matched historical cases.
* For the D and E profiles, values beyond the displayed ±161.8% range are grouped into the outermost top or bottom bin rather than split into additional bins.
🟢 REAL-TIME PROFILE
The active profile is continuously recalculated as price develops.
This can update:
C→Now progress
matched historical cases
D Path distribution
E Path distribution
B Break / No Break / C Break probabilities
Because D and E represent the active forward path, both profile boxes are always displayed to the right of the current candle.
🟢 DYNAMIC C
Before a new D swing is confirmed, the B→C retracement may continue to a new extreme.
In that case, the active C point is updated:
Bullish ABC → C moves to a new lower low
Bearish ABC → C moves to a new higher high
This prevents an unfinished B→C leg from being treated as a completed swing.
🟢 WEIGHT
Two weighting methods are available:
Recent
More recent historical cases receive greater weight.
Weight = 1 / (1 + Age / 1500)
where Age is measured in bars.
Equal
Every matched historical case receives the same weight.
Use Recent to emphasize newer market behavior or Equal to view the unweighted historical distribution.
🟢 HOW TO USE
Use the indicator to evaluate how similar historical structures developed from the current setup.
D Path highlights where the next swing historically tended to form.
E Path shows how price developed after that D swing.
B Break / No Break / C Break summarizes the historical structural outcome.
C→Now continuously refines the sample as the active move progresses.
The profiles represent historical swing distributions, not traded volume.
They are designed to provide a probabilistic view of the active structure rather than a fixed Fibonacci price target.
🟢 DISCLAIMER
This indicator is provided for informational and educational purposes only and does not constitute financial or investment advice.
Historical patterns and probabilities do not guarantee future results. All trading and investment decisions remain the sole responsibility of the user. אינדיקטור

Reballo Hindenburg Omen - Breadth GateWhat it is
The classic four-condition Hindenburg Omen, computed live from NYSE internals, held active for a set number of bars after it fires, plus a weekly breadth-oversold override. The output is a simple three-state risk gate :
Red — Omen active. Internals are split and weakening under a still-rising index. Freeze new risk.
Green — Breadth washed out. Fewer than 30% of S&P 500 stocks above their 200-day. Historically a bad time to be cutting risk.
Nothing — Clear. Most of the time.
This is not a crash predictor. The Omen's track record as a standalone signal is genuinely mixed, and anyone who tells you otherwise is selling something. What it is good at: catching the specific moment when a market is making new highs while a growing number of stocks are quietly breaking down. That's worth knowing, and worth being able to verify line by line.
The four conditions
All computed daily from NYSE data, all shown in the table so you can see which ones are holding:
1. Split market: new 52-week highs AND new 52-week lows both >= 2.2% of issues traded. The core of the Omen. A healthy market doesn't do both at once.
2. Still in an uptrend: NYSE Composite higher than 50 bars ago. The Omen is about divergence, so it only fires while the index is still up.
3. Internals weakening: McClellan Oscillator below zero (19/39 EMA on ratio-adjusted net advances).
4. Highs not dominating: new highs / new lows < 2.
When all four hit on the same day, a triangle prints and the gate turns red for 30 bars. Consecutive fires just extend the window.
The override
A weekly read of S5TH (percent of S&P 500 stocks above their 200-day MA). Below 30, the gate flips green and beats the Omen. The logic: once breadth is that washed out, the "split market" story is over and you're in a different regime where adding risk into weakness has worked far more often than not.
The table
Top right. One row per condition with the live value, green if met, red if not. When the Omen isn't active you can still see how close it is, which is most of the value.
How I use it
As a gate on position sizing, not as an entry or exit. Red = don't add. Green = the floor is probably in, don't panic-cut. It sits alongside a slow Ehlers CG and a regime score; when two or three of them agree the picture is usually right. On its own, treat it as one opinion.
Three alerts: Omen fires, Omen expires, breadth goes oversold.
Data requirements (read this)
Pulls USI:ADV, USI:DECL, USI:UNCH.NY, INDEX:MAHN, INDEX:MALN, NYA and S5TH. Some of these are not visible on every plan. If the table shows n/a, that's a data access issue, not a script bug.
All inputs come from index data, so it runs on any chart symbol. Put it on SPY, BTC, whatever you trade. It's telling you about the US market either way.
US stocks only. It has nothing to say about EFA or EEM beyond the fact that US internals tend to lead.
Settings
New Highs AND New Lows >= — 2.2% — the split-market threshold
Index higher than N bars ago — 50 — the uptrend check
Highs / Lows < — 2.0 — condition 4
Keep Omen active for N bars — 30 — the hold window
Breadth Symbol / Oversold Below — S5TH / 30 — the override
Open source. Fork it, break it, tell me what you find. אינדיקטור

Reballo Ehlers CG - Two-SpeedWhat it is
John Ehlers' Center of Gravity oscillator, normalised to a ±1 range and run at two very different speeds at once. Most CG scripts run one length around 10-20 bars and use it for swing entries. This one runs 128 and 256 bars and averages them. That turns it from an entry tool into a "how deep in the hole are we" gauge .
How it's built
Center of Gravity = the weighted mean position of price inside the window. Price sitting near the recent highs pulls the CG one way, price near the lows pulls it the other.
The CG is rescaled against its own highest / lowest over the same window, so it lives in regardless of the instrument.
A short 4-bar FIR smooth (4, 3, 2, 1 weights) takes out the jitter, then it's mapped to .
Run that twice (fast and slow), then average. The white line is the average. The grey lines are the two inputs.
Reading it
Below -0.8 (red zone): both the medium and slow view agree that price is pinned to the bottom of its range. "Washed out."
Above +0.8 (green zone): the opposite. "Stretched."
In between: nothing to see. That's most of the time on purpose.
Because the two speeds have to agree , the zones fire rarely. On SPY daily you'll typically see a handful of red episodes per decade: 2008, Mar 2020, Oct 2022 and the like.
How I use it
Not for entries. As a risk gate : when the average is washed out and other breadth / internals are also ugly, that's a "stop adding risk" flag, not a "buy the אינדיקטור

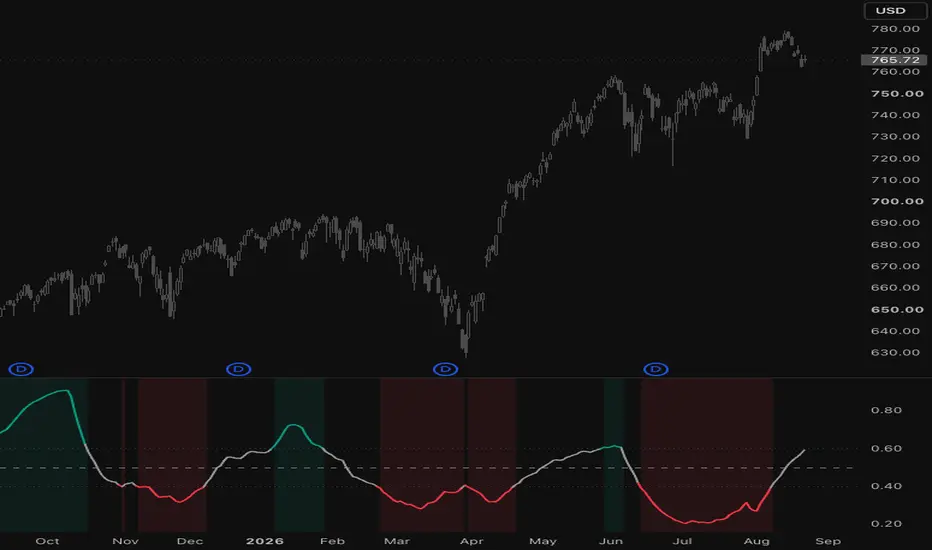
Reballo Regime Detector - ER + RelVol + AutocorrelationWhat it measures
Most indicators try to tell you which way price is going. This one asks a different question: is the market in a mood where trend-following works, or one where fading works?
You get one number, the Regime Score, from 0 (ranging / choppy) to 1 (trending). Under the hood it blends three different ways of looking at price, each measured at three speeds (16 / 32 / 64 bars by default).
The three components
1. Efficiency Ratio (Kaufman)
How straight is the path? Net distance ÷ total distance travelled. Move 10 points in 10 points of wiggle: score 1.0. Wander 50 points to end up 10 higher: score 0.2. High = directional, low = chop.
2. Relative Volatility
Short-window vol ÷ long-window vol (4× the short window). Quiet, compressing vol usually goes with clean trends. Expanding vol usually means transitions and churn. Capped at 2 and flipped so that "quiet" scores high.
3. Lag-1 Autocorrelation
Does today's move tend to follow yesterday's? Positive = follow-through (momentum-friendly). Negative = snap-back (mean-reversion-friendly).
Components 2 and 3 get averaged into one "RelVol+AC" number. Then both that and the ER get percentile-ranked over the last year , so a 0.8 on BTC means the same thing as a 0.8 on a sleepy utility stock, and 4H reads the same as daily.
Putting it together
Default mix is 40% Efficiency Ratio / 60% RelVol+AC, smoothed with a 16-bar EMA so it doesn't flip on every bar. Above 0.60 = trending (green). Below 0.40 = ranging (red). The middle is left grey on purpose: that's the "don't know, don't force it" zone.
What's hiding in the Data Window
Each component's rank on its own, so you can see what is actually moving the score.
Two derived weights, Divergence Multiplier and Convergence Multiplier (range 1 ± strength). If you run trend and mean-reversion signals side by side, these are meant to tilt between them: scale trend signals by Divergence, counter-trend signals by Convergence. At strength 0.5, a fully trending regime gives trend signals 1.5× weight and counter-trend signals 0.5×.
Ways to use it
As a filter: only take breakouts / momentum entries when it's green, only fade when it's red.
As a sizing knob: use the multipliers to lean in or out instead of switching strategies on and off.
As a sanity check: when it flips, peek at the Data Window to see whether vol, path efficiency or autocorrelation moved first.
Two alerts built in: regime → Trending and regime → Ranging.
Honest limitations
Needs about a year of bars (252 by default) before the ranking means anything.
It tells you what the regime is , not when it's going to change.
It doesn't care about direction. A clean crash scores as "trending" too.
Settings
Fast / Medium / Slow — 16 / 32 / 64 — speeds for all three measures
Weight: ER / RelVol+AC — 0.4 / 0.6 — how much each side counts
Percentile Rank Lookback — 252 — the "last year" window
Score Smoothing — 16 — EMA on the final score
Trending Above / Ranging Below — 0.60 / 0.40 — where the shading kicks in
Multiplier Strength — 0.5 — only touches the hidden multipliers
Open source. Fork it, break it, tell me what you find. אינדיקטור

אינדיקטור

Directional Bias, Flip & Continuation█ OVERVIEW
Directional Bias, Flip & Continuation is a single decision instrument that answers one question at a time — "which side, and is this a FLIP (reversal) or a CONTINUATION?" — and draws the exact levels that define the read: Trigger, stop, and two targets. Its loudest and most frequent output is STAND ASIDE: by design it spends most of its time telling you there is no clean read, rather than manufacturing one. It issues no buy/sell order and makes no promise; the confidence it shows is an in-script, past-only forward self-test with a Wilson lower bound on THIS chart, not a trained probability.
█ HOW IT WORKS
The tool resolves ONE of four states each confirmed bar, in strict priority order, so the states never contradict each other:
STAND ASIDE (checked first, fires most) — a chaos / extreme-volatility regime, a toxic-tape reading, or price sitting mid-range with no level nearby. This is the default; it is information, not a failure.
FLIP — a confirmed swing trend-flip that occurs AT a graded major level, with order flow not strongly opposed. The side is the flip direction.
CONTINUATION — a trending regime PLUS a confirmed structural break carrying strength PLUS higher-timeframe agreement PLUS price not already stretched into a level. The side is the trend.
CONFLICT — the engines disagree; shown transparently, with no side taken.
Each stage names the method it uses, and every calibrated block shares one scale rather than being independent indicators bolted together:
Regime brain — efficiency ratio (fast vs slow) + ADX with separate trend and strong-trend floors + a self-excitation / volatility-cluster gauge + a variance-ratio random-walk test + an Ornstein-Uhlenbeck mean-reversion read. A trend must clear BOTH persistence (ER) and strength (ADX) floors, so ordinary chop never reads as a strong trend.
Flip engine — a swing-structure trend flip scored by a composite (structure, momentum, location) with a kill state that vetoes flips in the wrong regime.
Continuation engine — a convex-hull channel break, validated for strength and for higher-timeframe alignment, with a stretch guard so a break into an opposing level is not chased.
Levels & targets — a multi-anchor VWAP / anchored-volume-profile ladder that snaps the Trigger, stop and two targets to real liquidity rather than fixed multiples.
Barriers & confidence — a volatility-scaled, regime-asymmetric profit-target / stop geometry, and a forward reject-vs-continue self-test (two-barrier race) that reports each mode's hit rate with a Wilson 95% lower bound and against a matched base rate; it stays "uncalibrated / warming" until the sample is large enough.
Flow proxy — a lower-timeframe signed-volume CVD estimate (Bulk-Volume-Classification fallback) used only to veto a side that fights strong opposing flow; it abstains on no-volume symbols.
█ HOW TO USE
Read the panel top-down: the state (STAND ASIDE / FLIP / CONTINUATION / CONFLICT) and side, then the confidence line, then the four levels. When a FLIP or CONTINUATION is live, the Trigger / SL / TP1 / TP2 are the levels that define it; when the state is STAND ASIDE they read "—" on purpose. The confidence line shows that mode's own forward-tested floor with its sample size, and says "uncalibrated" until there is enough history — treat a warming or low-confidence read as a reason to wait. The dashboard defaults to Compact (state, side, confidence and the four levels only); switch Dashboard detail to Pro to add the regime, engine-agreement, flow-toxicity and free-text detail rows, and enable the backtest strip to see each mode's forward win% and average R. STAND ASIDE dominating the tape is the tool working, not failing. Horizon and position sizing are yours; it places no orders.
█ INPUTS
00 · Data & Source — price source, borrow-volume symbol for volume-less instruments.
01 · Regime brain — ER fast/slow horizons, ADX length and trend / strong-trend floors, ER floors, volatility-cluster length.
02–05 · Flip / Continuation / Structure — swing length, break validation, HTF timeframe and agreement, stretch guard.
06 · Levels & targets — VWAP / AVP anchors, ladder, snap tolerance, barrier multiples.
07 · Confidence & calibration — reject/continue barrier size, horizon, minimum sample, edge-gate window.
08 · Flow proxy — LTF granularity, classifier, toxicity gate.
09 · Display — dashboard detail (Compact default / Pro), backtest strip, regime breakdown, markers, panel position.
10 · Style — Dark / Light theme.
█ HONESTY & LIMITATIONS
This is a study, not a strategy. The confidence figure is an in-sample, descriptive, forward self-test on visible history with fixed barriers and no costs or slippage — it is not a backtest and not a probability of your next trade working. Order-flow side is an OHLCV estimate and abstains on symbols without volume. Non-repaint by construction: all higher- and lower-timeframe reads use lookahead-off; pivots confirm several bars late; the verdict, its levels, and the outcome tracking all resolve on confirmed bars only, and prior-period levels use the standard non-repainting prior-bar idiom. When the sample is small the confidence is shown as uncalibrated and the read is discounted; when there is no clean setup the tool says STAND ASIDE rather than inventing one. No edge shown is honest, not broken.
█ ORIGINALITY
One coherent decision object, not a signal stack. The original contribution is the strict-priority four-state resolution — STAND ASIDE is evaluated first and dominates, so FLIP and CONTINUATION can only fire when the regime, structure, location and flow all agree — paired with a per-mode confidence that is measured on the chart by a Wilson-bounded forward self-test rather than asserted. Each block (regime, flip, continuation, levels, barriers, flow) exists only to feed that single verdict and its levels; none is presented as a standalone indicator. That combination — a location-aware, regime-gated flip-vs-continuation decision that grades and honestly discounts its own confidence, and whose default answer is "stand aside" — is what distinguishes it from a trend filter, a breakout signal, or a bundle of oscillators.
█ CREDITS
Efficiency ratio — Kaufman. ADX / DMI — Wilder. Variance-ratio random-walk test — Lo & MacKinlay. Mean reversion — Ornstein & Uhlenbeck. Self-exciting clustering — Hawkes. Volume-weighted average price / value-area concepts — Market Profile lineage. Bulk Volume Classification — Easley, López de Prado & O'Hara. Trade-side tick rule — Lee & Ready (1991). Two-barrier forward test — López de Prado. Wilson score interval — Wilson (1927). Code written from scratch; no external script reused.
This script is for analysis and education. It is not financial advice. אינדיקטור

Absorption Shelf Dwell-Coil Reversal Levels█ OVERVIEW
Absorption Shelf finds reversal LEVELS the opposite way round from a pivot or a profile POC: it starts from TIME. A price band becomes a "shelf" because price DWELT there — an anomalous amount of occupation time — while its range COILED (volatility compressed). Only then do orthogonal order-flow lenses CONFIRM whether that shelf is genuinely ABSORBING flow rather than merely balancing, and a confirmed close back out of the band is treated as the reversal. It asserts no signal and no win-rate; it shows, honestly and past-only, how often price has actually rejected off these shelves versus a matched base rate.
█ HOW IT WORKS
Substrate — one lower-timeframe stream (request.security_lower_tf) supplies a per-bar buy/sell split (BVC-Normal / Tick / Geometry) for delta and signed order flow; it falls back to the chart bar when no intrabar data exists. The method in force is shown (REAL / EST).
Dwell field (the level generator) — a rolling, fixed-tick OCCUPATION-TIME map: each confirmed bar adds time to every price level its range covers, and the bar leaving the window subtracts it exactly (a reversible ring buffer). Levels at or above a self-set percentile κ are "hot"; adjacent hot levels merge into candidate BANDS.
Coil + containment (the stall trigger) — a band is promoted to an ACTIVE shelf only when compression (1 − ATRfast/ATRslow) clears a threshold AND enough recent closes sat inside the band. Dwell + coil together are what make a quiet band a shelf — this is the part a pivot- or profile-based level does not have.
Confirmation lenses (on the band only) — Effort-vs-Result √-law residual (E: heavy volume, little price result = absorption), localized Kyle-λ collapse (K: price barely moves per unit signed flow), Dwell-decay (D: the band has stopped accreting time = primed to release), Rejection-wick clustering (W: Wilson-floored), and CVD divergence (V). Each abstains cleanly on missing data.
Fusion — the active lenses combine by correlation-aware Bayesian log-odds: each is reliability-shrunk by its own past edge and Kish-decorrelated so the absorption family (E, K, D) contributes about one lens' worth, not three, then squashed to P_abs → BALANCE / ABSORBING / PRIMED. Shelves are down-weighted in strong trend (a built-in efficiency-ratio regime gauge, or a consumed external one).
Flip + lifecycle — a confirmed close out of the band against the approach is the reversal (a ▲ bullish or ▼ bearish flip, coloured by direction). Shelves carry a lifecycle: forming → active → flipped → spent → naked (kept until retested).
Reject calibration (honesty layer) — when price first touches an active shelf, the script forward-tests whether it REJECTS (turns back by k·ATR) BEFORE it CONTINUES through by k·ATR, versus the matched unconditional reject-vs-continue base rate: reject% (n, Wilson 95% lower bound) vs base% → edge, broken out by tag (does PRIMED out-reject ABSORBING out-reject BALANCE?), split in-sample / out-of-sample, and Bonferroni-deflated. Past-only, non-repaint.
█ HOW TO USE
Read the shelves as context, not as entries. A teal band below price is a support shelf (price is being held from below); a red band above is a resistance shelf. Brightness tracks how strongly the band was dwelt. The tag tells you what the flow says about it — BALANCE is just a quiet level, ABSORBING and PRIMED mean the lenses agree a wall is soaking flow there. A ▲/▼ flip marks where price actually closed back out of a shelf against its approach. The calibration line is the honest part: it tells you, on this symbol and timeframe, how often tagging a shelf has preceded a real rejection versus random — and shows nothing when the sample is small. A flat read with no active shelf is a genuine "no location here", not a broken one. The dashboard defaults to Compact (shelf, tag, dwell %, flip); switch it to Pro for the lens-by-lens glyphs and the calibration breakout. Horizon and holding are yours to decide; it emits no orders.
█ INPUTS
01 · Data & Trade-Side — LTF granularity, classifier, BVC sharpness.
02 · Dwell Field — ticks-per-level, dwell window, hot-level percentile κ, band merge gap, min band width.
03 · Coil & Stall — fast/slow ATR, minimum coil to promote, containment lookback / fraction / buffer.
04 · Confirmation Lenses — enable E / K / D / W / V and their sensitivities.
05 · Fusion — Kish decorrelation, self-set tag percentiles (absorbing / primed).
06 · Flip & Lifecycle — flip distance (×ATR), ghost retention, max shelves tracked.
07 · Regime & Self-Cal — trend down-weight (built-in efficiency ratio, or consume an external regime).
08 · Calibration — reject size (×ATR), horizon, Bonferroni, in/out-of-sample split.
09 · Microstructure Links (optional) — consume external Toxicity or Kyle λ; never recomputed.
10 · Display — bands, how far back to draw, badge, lens glyphs, flip markers, naked shelves, dwell heat spine, dashboard detail (Compact default / Pro).
11 · Style — Auto / Dark / Light theme.
12 · Exports — shelf levels, tag, P_abs, dwell percentile, coil, flip direction, naked levels, reject edge, active lenses.
█ HONESTY & LIMITATIONS
Descriptive, not predictive. Order-flow side is an OHLCV ESTIMATE (BVC / tick / geometry), not a Level-2 book; on symbols with no volume the flow lenses (E, K, V) abstain and the shelf runs on dwell + coil + wick alone, stated in the dashboard. Coil is measured chart-wide (ATR ratio) while containment is per band. The reject calibration is a past-only, first-touch two-barrier (reject-vs-continue) forward test against a matched base rate with a Wilson lower bound, tag buckets, an in/out-of-sample split and a Bonferroni deflation; a small sample is discounted automatically and no edge shown means honest, not broken. Non-repaint by construction: dwell and coil accrue on confirmed bars, shelves promote from confirmed history, the flip fires on a confirmed close, calibration events resolve only after the horizon, and the render recomputes once per confirmed bar. For runtime the script processes the most recent ~5000 bars and gates the calibration engine behind its own toggle. It prints no verdict and no win-rate.
█ ORIGINALITY
One coherent object: a reversal level whose EXISTENCE comes from occupation time plus volatility compression, with order flow demoted to confirmation on that band. This is deliberately distinct from a volume/footprint profile (those build the level from volume-at-price and fire sweeps event-by-event), from pivot- or kernel-based support/resistance (those build the level from swing geometry), and from a potential-well or mean-reversion model (those are price-dynamics with no time-at-price). The dwell-time + coil "absorption shelf" as the level generator, the dwell-decay lens that only this occupation field makes possible, and the correlation-aware fusion that explicitly discounts absorption-lens redundancy are the specific original contributions. Every block was written from scratch for this tool; the lenses feed one decision (is this band absorbing?) rather than being independent indicators stapled together.
█ CREDITS
Occupation-time / TPO at price — Steidlmayer / Market Profile. Price-impact λ (delta-response) — Kyle (1985). Square-root market-impact law — Almgren; Tóth, Bouchaud et al. Bulk Volume Classification — Easley, López de Prado & O'Hara. Trade-side tick rule — Lee & Ready (1991). Two-barrier / triple-barrier forward test — López de Prado. Wilson score interval — Wilson (1927). Design-effect / effective sample — Kish (1965). Code written from scratch; no external script reused.
This script is for analysis and education. It is not financial advice. אינדיקטור

אינדיקטור

ChartlingCHARTLING
A tiny market-aware companion that lives on your chart.
Every day, a new Chartling can hatch on your chart with its own permanent identity: appearance, rarity, name, personality, traits and quirks. As the market moves, it reads those conditions, reacts to them, and gets on with its own little life. It might study the chart, grab a coffee, read, exercise, nap, or watch the market through a telescope.
Chartling experiences the market with you.
DAILY HATCH
At a configurable hatch time and timezone, each day brings a new deterministic Chartling that grows through a small lifecycle:
EGG → HATCH → YOUNG → ADULT
The HUD shows its current age, and its look develops as it grows.
THE CATALOGUE
Chartling contains a deterministic catalogue of 999,999,999 creatures, IDs #000000001 to #999999999 .
Every valid ID permanently maps to one canonical Chartling: a unique three-part name, rarity, palette, head, tail, markings, core, personality, dominant traits and two quirks.
Enter the same ID again and you get the same canonical Chartling.
The ID is its permanent genetic address.
RARITY
Six deterministic tiers, shown in the HUD in each tier's color:
COMMON — 599,999,999
UNCOMMON — 250,000,000
RARE — 100,000,000
VERY RARE — 40,000,000
MYSTICAL — 9,000,000
LEGENDARY — 1,000,000
Higher tiers unlock rarer cosmetic gene pools, up to the Golden palette and Halo core at Legendary.
PERSONALITY & QUIRKS
Traits like curiosity, laziness, confidence and drama combine into archetypes such as QUANT, GREMLIN, LOAF, HOTSHOT and SCOUT.
Each Chartling also carries two permanent quirks — COFFEE, NAPPER, WATCHER, FIT and more — that influence its behavior, so a coffee-lover and a napper can live noticeably different days.
MARKET SENSE
Chartling reads the market through a Flow + Wave system and wears that information:
Flow becomes belly color — reflecting direction and strength around a smoothed market reference.
Wave becomes a small flag — green when price is above the Wave, red when below, and no flag when price overlaps it.
A configurable Trend Timeframe can drive the Wave.
When it is higher than the chart timeframe, Chartling uses confirmed higher-timeframe data. When it is equal to or lower, Chartling uses the chart timeframe.
Repeated Flow changes, sustained trends and choppy stretches feed a small market memory that shifts its mood over time.
TRADING WISDOM
On by default: 500 trading-psychology reflections covering risk, patience, discipline, FOMO, drawdowns and more.
A reflection is selected deterministically from each Chartling's ID.
Turn Trading Wisdom off for the more whimsical Chartling Lore .
Either way, the creature's canonical identity stays the same.
COLLECTING
Add IDs to your Keeper List to remember favorites.
Use Show Chartling # to summon any catalogue ID. A summoned Chartling keeps the current day's age and lifecycle while displaying that ID's permanent identity.
A private Trainer Code personalizes your daily hatch sequence. Using the same Trainer Code with the same market, hatch settings and day reproduces the same hatch.
HUD & LAYOUT
A five-line identity card shows:
Name / rarity
ID / age
Personality / traits / quirks
DNA / collection status
Trading Wisdom or Chartling Lore
The HUD adapts to light and dark chart themes, while the Chartling's name, ID and DNA retain its rarity color.
Chartling and the HUD can be positioned independently across eight chart locations.
Static Chartling pauses animation and Market Sense for a quieter collectible view.
HOW TO USE
Add Chartling and set your hatch time and timezone.
Optionally enter a Trainer Code for a repeatable daily hatch sequence.
Let it hatch and watch personality and market conditions shape its behavior.
Keep the ones you like and revisit any ID with Show Chartling #.
Chartling is an informational, educational and entertainment-oriented market companion. Flow, Wave, volatility, volume and range drive its visuals and behavior; Trading Wisdom offers general reflection.
Market interpretation, trade selection and risk decisions remain with you.
Every chart has a story. Every day has a new Chartling.
Chartling experiences the market with you. אינדיקטור

Average RSI | TR🔍 OVERVIEW
The Average RSI is a next-generation momentum oscillator that goes beyond the standard Relative Strength Index. Instead of relying on a single timeframe, it calculates the RSI across three distinct daily cycles (1 Day, 2 Days, and 3 Days) and averages them into one smooth, highly responsive signal.
This multi-timeframe averaging drastically reduces market noise, filters out false divergences, and provides a holistic view of the short-to-medium term momentum structure. Combined with a dedicated dynamic moving average, it acts as both a trend filter and an early entry/exit system.
⚙️ HOW IT WORKS
1. RSI Computation:
The script calculates the classic RSI of your chosen source (default: Close) for the 1D, 2D, and 3D timeframes.
2. The Average (AVG_RSI):
It takes the arithmetic mean of these three values. This "composite RSI" is the core line you see plotted on the chart.
3. The Trend Filter (MA_AVG_RSI):
A fully customizable Moving Average (default: EMA, Length: 275) is applied to the AVG_RSI. This acts as the "Zero Line" of the indicator:
• AVG_RSI > MA_AVG_RSI → Bullish Bias
• AVG_RSI < MA_AVG_RSI → Bearish Bias
🎨 VISUAL FEATURES & SIGNALS
• Dynamic Trend Coloring:
The main line, candles, and chart background dynamically shift colors based on a normalized gradient of the AVG_RSI, making trend strength instantly recognizable.
• Smart Gradient Fills:
Ribbon Fill: The area between the AVG_RSI and its Moving Average is filled with the trend color. Its transparency adjusts automatically based on price momentum—more opaque during strong trends and faint during consolidation.
Overbought/Sold Zones: Gradient fills between the AVG_RSI and the 50-level are activated only when the AVG_RSI extends beyond the Moving Average. This unique logic prevents misleading extreme-zone signals during trend reversals.
• Entry/Exit Signals (Triangles):
LONG (⬆️): A green triangle appears below the bar when AVG_RSI crosses ABOVE the MA_AVG_RSI.
SHORT (⬇️): A red triangle appears above the bar when AVG_RSI crosses BELOW the MA_AVG_RSI.
• Heads-Up Display (HUD):
At the last bar, a large table displays the current market bias (Bullish/Bearish), and a floating label shows the precise AVG_RSI value.
🎛️ INPUT CONFIGURATIONS
• RSI Length: Adjust the sensitivity of the RSI calculation (Default: 44).
• Source: Choose the base source for the RSI (Default: Close).
• Moving Average Engine: Select from 12 different MA types, including EMA, SMA, WMA, HMA, DEMA, TEMA, TRIMA, FRAMA, SWMA, and T3 (with adjustable T3 Factor).
• MA Length: Set the smoothing period for the trend filter (Default: 275).
• Color Palettes: Choose from 9 distinct visual themes—Classic, Modern, Heat, Robust, Accented, Monochrome, Moderate, Aqua, or Cosmic—to match your charting style.
🚨 ALERTS
Built-in alert conditions are ready to use:
• LONG: Triggered on a Bullish crossover.
• SHORT: Triggered on a Bearish crossunder.
💡 BEST USE CASES
• Swing Trading: Identify shifts in mid-term momentum.
• Trend Confirmation: Use the MA filter to avoid entering trades against the dominant flow.
• Divergence Spotting: The smoothed nature of AVG_RSI makes chart patterns and divergences much clearer than with standard RSI.
📌 Note: This indicator works on any asset (Crypto, Forex, Stocks, Commodities) and any timeframe, as the underlying MTF logic is anchored to the daily RSI structure. אינדיקטור

Adaptive MA Ribbon [StrixEDGE]📊 WHAT IT DOES
StrixEDGE Adaptive MA Ribbon plots three of the most advanced low-lag moving averages — Hull MA, Arnaud Legoux MA, and Kaufman Adaptive MA — with automatic period adjustment based on current volatility. A consensus score (0-6) instantly shows whether all three agree on trend direction.
🔬 WHY IT'S DIFFERENT
Traditional MA ribbons use fixed periods that work in one market condition and fail in another. This ribbon automatically shortens its period when volatility spikes (for faster reaction) and lengthens it when markets are calm (to avoid whipsaws). The three MAs used — HMA, ALMA, and KAMA — are specifically chosen because each adapts to the market differently, so their agreement carries more weight than three similar MAs agreeing.
⚙️ HOW IT WORKS
The volatility ratio (current ATR / 50-period average ATR) dynamically adjusts the base period. This adjusted period feeds into all three MAs simultaneously. The consensus score counts two things: how many MAs are below price (0-3 points) and how many are rising (0-3 points). A score of 6 means all three MAs are below price AND rising — the strongest possible bullish configuration.
📈 HOW TO USE
• Consensus 5-6 (green fill): Strong uptrend — buy pullbacks to the ribbon
• Consensus 0-1 (red fill): Strong downtrend — sell rallies to the ribbon
• Consensus 2-4 (gray fill): Mixed — avoid trend strategies
• Diamond markers at consensus flips = key entry/exit signals
• Ribbon twist (MAs crossing) = early warning of trend change
• Works best on 4H and Daily timeframes
🎛️ INPUTS & DEFAULTS
Base Period: 21 | Min: 8, Max: 55 | ALMA Offset: 0.85, Sigma: 6.0
═══════════════════════════════════════════════════════
🔧 CUSTOMIZATION
All parameters are fully adjustable through the indicator settings panel. Inputs are grouped logically:
• ⚙️ Core Parameters — main calculation settings
• 📊 Table Settings — table size (Tiny to Huge), position (4 corners), visibility toggle
• 🎨 Visual Settings — colors, show/hide elements
• 🔔 Alert Settings — threshold values for notifications
📊 DATA TABLE
A built-in data table displays all key metrics in real-time. Adjust the table size from Tiny to Huge to match your chart layout. Position it in any corner. Toggle visibility on/off.
🔔 ALERTS
Pre-built alert conditions for all major signals. Set up alerts via TradingView's alert dialog — select this indicator and choose from the available conditions.
⏱️ RECOMMENDED TIMEFRAMES
Works on all timeframes. Recommended: 1H, 4H, Daily for best signal quality. Lower timeframes produce more signals but with higher noise. Weekly/Monthly for position trading context.
✅ COMPLIANCE
• No repainting — all signals based on confirmed bar close data
• No future data references
• Open-source code — verify the logic yourself
⚠️ DISCLAIMER
This indicator is a technical analysis tool, not financial advice. It does not predict future price movements. Past patterns and signals do not guarantee future results. Trading involves substantial risk of loss. Always use proper risk management, including stop losses and appropriate position sizing. Never risk more than you can afford to lose. אינדיקטור

VWAP MTF Adaptive Levels
VWAP MTF Adaptive Levels
DESCRIPTION
VWAP MTF Adaptive Levels is a multi-timeframe VWAP indicator designed to provide clear volume-weighted reference levels without covering the candles.
Instead of plotting complete VWAP curves across historical price action, the indicator displays the current levels as short horizontal lines positioned to the right of the latest candle. This keeps the chart clean while preserving the most important VWAP information.
MAIN FEATURES
• Adaptive main VWAP based on the active chart timeframe
• Daily, Weekly and Monthly VWAP reference levels
• Optional ±1, ±2 and ±3 standard-deviation levels
• Short horizontal lines displayed only on the right side
• Exact price displayed next to every level
• BULL/BEAR dashboard
• Fully customizable colors, line width, line length and text size
• Adjustable distance from the latest candle
• Built-in crossover alerts
• America/New_York timezone with automatic daylight-saving adjustment
AUTO ANCHOR MODE
When “Auto” is selected, the VWAP anchor changes automatically:
• Intraday charts → Daily VWAP
• Daily chart → Monthly VWAP
• Weekly chart → Quarterly VWAP
• Monthly chart → Yearly VWAP
BULL/BEAR DASHBOARD
The dashboard provides a simple directional context:
• BULL: price is above the main VWAP
• BEAR: price is below the main VWAP
The dashboard also displays the active chart timeframe, current VWAP anchor and main VWAP price.
The BULL/BEAR status is a market-bias filter and should not be considered a standalone entry signal.
CUSTOMIZATION
Users can independently configure:
• Visible VWAP levels
• Standard-deviation multipliers
• Distance from the latest candle
• Horizontal-line length and thickness
• Solid, dashed or dotted line style
• Price-label size
• Dashboard position and size
• BULL and BEAR colors
• Individual colors for every VWAP level
NOTES
The script does not use request.security() lookahead logic. VWAP values on the open candle update in real time as price and volume change; confirmed historical values remain stable after the candle closes.
VWAP requires volume information. On Forex and CFD symbols, results can vary between brokers because these markets may use tick volume instead of centralized exchange volume.
This indicator was created primarily for XAUUSD analysis, but it can be used on other instruments and timeframes that provide volume data.
Suggested workflow:
• H4/H1 for directional context
• M15/M5 for execution analysis
• Combine VWAP with market structure, liquidity sweeps, PDH/PDL, PWH/PWL, FVG and confirmed break/retest setups
DISCLAIMER
This indicator is intended for educational and analytical purposes only. It does not constitute financial advice or guarantee future results. Always apply independent analysis and appropriate risk management.
TAGS
VWAP, Multi-Timeframe, MTF, Volume, Standard Deviation, XAUUSD, Gold, Intraday, Dashboard, Support and Resistance
אינדיקטור

The Ultimate 50 EMA @JustinPerezTradesUltimate Day Trader — NQ/MNQ Multi-Timeframe 50 EMA Stack
A precision pullback/breakout indicator for NQ and MNQ that only signals when five timeframes of 50 EMAs are stacked in trend order.
Overview
This indicator looks for a specific structural setup on NQ and MNQ futures: a short-term pullback (or push) away from the 1-minute 50 EMA that occurs while the 50 EMA is climbing or falling in a clean, ordered stack across five timeframes (1m, 5m, 10m, 15m, 30m). The idea is to only trade pullbacks that are happening inside a confirmed multi-timeframe trend, rather than reacting to the 1-minute chart in isolation.
It's a signal/alert tool — it plots the EMA stack, marks entries and the exit target on the chart, and can fire alerts. It does not place trades for you.
How it works
Long setup — all of the following must be true at once:
Price is 50–100 points below the 1-minute 50 EMA (a pullback into value, not a full trend break)
5-minute 50 EMA is above the 1-minute 50 EMA
10-minute 50 EMA is above the 5-minute 50 EMA
15-minute 50 EMA is above the 10-minute 50 EMA
30-minute 50 EMA is above the 15-minute 50 EMA
When all five conditions align, the script marks a long entry. The exit target is the 30-minute 50 EMA — the trade is considered closed once price trades up to reach it.
Short setup is the mirror image: price 50–100 points above the 1-minute 50 EMA, with each higher timeframe's 50 EMA stacked below the one before it (5m < 1m, 10m < 5m, 15m < 10m, 30m < 15m). Exit target is the same 30-minute 50 EMA, reached from above.
Entries are edge-triggered — you get one signal per fresh setup, not a repeated marker on every bar the condition happens to remain true.
How to use it
Apply the indicator to a 1-minute chart on NQ or MNQ (front-month continuous contract or a dated expiry). The script checks both conditions and shows a warning label if either isn't met.
Watch the on-chart status table for a live read of: chart/symbol validity, current position state (flat / in long / in short), whether the MTF stack is bullish, bearish, or unaligned, the price's distance from the 1m EMA, and the current exit target level.
Green up-triangles mark long entries, red down-triangles mark short entries; a background tint confirms when the broader EMA stack is aligned even before price reaches the entry zone.
Right-click the chart → Add Alert to get notified on Long Entry, Short Entry, Long Exit, or Short Exit independently.
Inputs
EMA Length — default 50, applies to all five timeframes
Min / Max entry distance from the 1m EMA (points) — default 50 / 100, tuned for NQ/MNQ's typical point range
Restrict signals to NQ/MNQ only — on by default; disable to experiment with the same logic on other instruments
Higher timeframe overrides — 5m/10m/15m/30m are adjustable if you want to test alternate spacing
Display toggles for the EMA plots, stack-aligned background highlight, and the status table
Notes
This script is built BY @JustinPerezTrades specifically around NQ and MNQ's point behavior — the 50–100 point entry zone will not translate directly to instruments with different average ranges. It is a rules-based signal tool, not a guaranteed-profit system, and past alignment of these conditions does not predict future results. Backtest and paper-trade before using it with real capital, and use it alongside your own risk management. אינדיקטור

RC Tools - CUSUM Drift Detector────────────────────────────────────────────────────────────────────
█ OVERVIEW
Most trend tools measure a single bar or a moving-average deviation, so a slow, persistent drift that never produces one dramatic bar can slip under their radar. This tool applies CUSUM — Cumulative Sum Control Chart, a classical statistical process control technique — to detect exactly that: a sustained departure from "no drift" that accumulates over many small moves rather than one large one.
█ WHAT IT DOES
Tracks two running sums of log returns — one for upward drift, one for downward — and flags a directional regime once the accumulated drift breaches a volatility-scaled threshold. Colours the chart background Bullish or Bearish Drift accordingly, plots the two accumulating sums against their threshold lines in a dedicated pane, and shows a table with the current state, how long price has been in it, and historical base rates (average forward return and win rate) for each state.
█ THE THEORY BEHIND IT
CUSUM was developed by E.S. Page in 1954 for detecting a persistent shift in a manufacturing process mean — the same statistical question as "has this market started drifting in a new direction," just applied to price instead of a factory line. The key property that separates it from a moving average or a single-bar threshold: CUSUM accumulates. A string of small, consistent moves in one direction builds up and eventually crosses the detection threshold, even if no individual bar looks remarkable. Pure noise — moves that cancel out — never accumulates at all, because a small "allowance" is subtracted from every observation before it's added to the running sum.
Critically, the reference point CUSUM measures departure from is fixed at zero, not a rolling average of the same series. A rolling mean would chase the trend and cancel out the very drift being measured — anchoring at a fixed "no drift" baseline is what makes the classical test work.
█ HOW IT IS CALCULATED
1. Compute log returns of the selected source.
2. Estimate sigma — the rolling standard deviation of those log returns over the Window Length — as the local noise scale.
3. Two running sums accumulate each bar:
S+ = max(0, S+ prev + (log return − k)) — accumulates upward drift
S− = min(0, S− prev + (log return + k)) — accumulates downward drift
where k (the Drift Allowance) is a small multiple of sigma, subtracted out so ordinary noise never builds a signal.
4. When S+ crosses above the threshold h (a larger multiple of sigma), a sustained upward drift is declared, the background flips Bullish, and S+ resets to zero to begin monitoring fresh. S− works symmetrically for downward drift.
5. Between detections, the classification holds — this is deliberate persistence, not a bug: CUSUM is built to answer "has the regime changed," not to flicker every bar.
Classification occurs ONLY on confirmed bar close — the plotted sums, the background colour and the table all update together, so nothing here can disagree mid-bar or flip back and forth as the current bar forms.
█ SETTINGS & CONFIGURATION
• Source (default close)
• Window Length (default 14) — rolling window for the sigma (noise-scale) estimate
• Decision Threshold h (default 2.0σ) — how much accumulated drift is required before a regime shift is declared
• Drift Allowance k (default 0.2σ) — moves smaller than this are subtracted out and never accumulate
• Forward Return Window (default 20 bars) — the horizon used for the base-rate table
• Table position and colours are fully configurable; the main-chart background painting can be toggled off if you only want the CUSUM pane
█ HOW TO USE IT
Use it as a slow-drift filter alongside faster tools, not as a standalone entry trigger. Because CUSUM only flips after drift has genuinely accumulated, it tends to confirm a regime later than a fast oscillator but with fewer false starts in choppy conditions — the trade-off is lag for reliability. Check the base-rate table's sample count before treating any single state as meaningfully predictive.
Works on any asset and timeframe with sufficient history for the Window Length.
█ LIMITATIONS
• CUSUM detects a PERSISTENT departure from zero drift, not a magnitude or overbought/oversold level. Any use of it as a precise reversal forecast is a misuse.
• The fixed zero reference is directional-agnostic to any trend that existed before the current accumulation window began — it only measures drift accumulated since the last reset.
• h and k are both expressed in sigma multiples; a poorly-fit Window Length will misclassify ordinary volatility as drift, or vice versa.
• Resets on trigger mean the tool can flip again quickly after one large accumulation event, then need to rebuild before flipping a second time.
• Historical base-rate stats need a meaningful sample count (check N) before being trusted, especially in a low-frequency-flip regime or on a short history.
• This script does NOT repaint. All classification updates on confirmed bar close only.
█ DISCLAIMER
For educational and informational purposes only. Nothing here is financial advice. Past behaviour of any drift state does not indicate future results. Trade at your own risk.
אינדיקטור

TURKS Engine - Tiered Unit Risk KernelMost position-sizing tools tell you what to hold after the move. This one tells you the price at which it changes, before price gets there.
TURKS Engine decides how much of a long position to hold. Exposure is a graded function of where the close sits against four moving averages, so it moves in rungs rather than switching on and off. That function is monotone in price, which means it inverts: every rung has exactly one price. The panel solves for those prices and prints them today — a ladder of levels at which the position gets larger or smaller, readable now.
Long only, 0 to 1. No shorting, no leverage, nothing resting at a broker.
This is the indicator build of TURKS. Same engine, no orders — it sizes, you execute.
📊 WHAT THE LADDER DID
Twelve symbols, shipped defaults, 4-hour charts, full available history. Commission $1.50 per order, slippage 0.01xATR per side, idle cash credited nothing. b&h is buy-and-hold over the identical bars, charged nothing at all. The comparison is deliberately rigged against the engine.
SCOREBOARD 12 symbols, 4h, full history, net of costs
maximum drawdown cut versus buy and hold .......... 12 of 12
CAGR / maxDD better than buy and hold .......... 7 of 12
CAGR better than buy and hold .......... 3 of 12
TURKS versus BUY AND HOLD, sorted by CAGR
CAGR MAX DRAWDOWN CAGR / maxDD
symbol sample TURKS b&h TURKS b&h TURKS b&h
SNDK 1.3y +1406.3% +1899.0% -37.2% -56.8% 37.82 33.43
ETH 9.5y +117.3% +71.9% -54.4% -94.1% 2.16 0.76
BTC 9.5y +70.0% +54.2% -62.3% -83.9% 1.12 0.65
ARM 2.7y +62.5% +72.9% -39.8% -55.8% 1.57 1.31
TSLA 15.9y +32.7% +41.7% -57.0% -74.9% 0.57 0.56
NVDA 22.4y +25.3% +36.4% -77.0% -85.2% 0.33 0.43
AMD 21.4y +20.2% +17.3% -69.3% -96.1% 0.29 0.18
AVGO 16.8y +16.9% +39.0% -36.9% -50.3% 0.46 0.78
MU 22.4y +9.3% +19.7% -81.4% -90.9% 0.11 0.22
GOLD 13.5y +7.2% +7.7% -20.0% -35.0% 0.36 0.22
SPY 20.4y +4.4% +9.1% -40.5% -56.7% 0.11 0.16
INTC 20.4y +2.2% +8.5% -73.3% -74.2% 0.03 0.11
CAGR / maxDD is the column that settles it — return earned per unit of drawdown suffered. On that measure the engine wins on 7 of 12. It cut maximum drawdown on 12 of 12, and beat buy-and-hold on raw return on 3.
▸ ETH — 117.3% against 71.9%, at −54.4% drawdown against −94.1%. Nearly double the return on barely half the pain.
▸ BTC — 70.0% against 54.2%, at −62.3% against −83.9%.
▸ AMD — 20.2% against 17.3%, turning a −96.1% hole into −69.3% across 21.4 years.
These are assets that spent their entire sample inside a historic bull market, measured against a benchmark paying no commission and no slippage. Halving a drawdown is ordinary. Halving it and finishing ahead is not.
Every one of those numbers comes from the BOOK panel in this script. There is no separate research harness behind them and no second, gross set of figures anywhere in the build. Load it on your own symbol and the whole table regenerates for that instrument in one bar, net of the costs you typed in.
The table was measured on 16 August 2026. A live chart keeps adding bars, so the panel will not read exactly these numbers — at the time of writing ETH has drifted to 122.3% against 76.1%. Read the panel, not the table, for what the engine is doing on your instrument today.
📖 HOW TO USE IT
1 — Set your costs first. Commission ($ per order) and Typical position size ($) are the only two numbers the cost model needs; every other cost figure is a rate derived from them. A flat $1.50 is 1.9bp on an $8,000 position and 7.5bp on a $2,000 one. Leave these wrong and the panel lies to you.
2 — Pick the instrument. Single names and crypto whose drawdowns are violent relative to their drift. The table above is the guide, including the four rows that say don't.
3 — Read the ladder, not the arrows. The SELL / BUY ENGINE block prints three live numbers:
▸ Sell next above — the price at which the next rung comes off
▸ Buy back below — the price at which it goes back on
▸ Rungs sold — how much the envelope has already taken off, e.g. *12 of 20*
Both prices exist now, before the move. They are not marks that appeared after one.
4 — Read the dial. THE RULE prints Target weight — what the rule says you should be holding at this instant — and Dial c / f. POSITION prints the modelled book: weight held, average cost, open return, and the round-trip cost that position is carrying, so the gap between intention and position is always visible.
5 — Size it with c and f, not by fighting the rungs. c scales the whole position down. f is the floor you keep while the rule is off; raising it walks the book continuously toward buy-and-hold. Both tooltips print the measured frontier — the whole curve of what each step costs in return and buys in drawdown, including the region where the rule loses to simply holding less.
6 — Check it on your own symbol before trusting any of it. BOOK prints Sample, CAGR against b&h, Max drawdown against b&h, CAGR/maxDD, Sharpe, Exposure and Turnover. BOOK LEDGER, bottom right, prints the same book in money: book value against buy-and-hold from the same start, spells closed, profit factor, worst run, open position.
🔔 ALERTS
Five named conditions in the alert dialog — Target weight changed, Weight added, Weight cut, Gate on, Gate off — plus a rich alert() message carrying the weight it moved from, the weight it moved to, and both envelope prices. Flip one checkbox and the same payload arrives as JSON for a webhook.
🪜 HOW THE EXPOSURE IS SET
Exposure Shape picks the weighting rule. *Ensemble 20/50/100/200 (graded)* is the default. Each of the four SMAs contributes its own 0-to-1 ramp as price clears it, scaled in ATR and widened for the longer means so a 200-day cross is not treated like a 20-day one. The four ramps are averaged, then rounded to the nearest third:
SMA 20 ramp 0..1 ---+
SMA 50 ramp 0..1 ---+
SMA 100 ramp 0..1 ---+-- average -- round to thirds -- 0 / 33% / 67% / 100%
SMA 200 ramp 0..1 ---+
Four reachable weights, three thresholds, and the panel prints the price of all three. *Graded (continuous)* uses one mean with an ATR ramp instead. *Binary gate (legacy)* is the original all-or-nothing rule, kept so the graded version has something to be measured against.
Risk dial c scales the entire position down. Risk dial f is how much you keep while the rule is off. These two are the real levers, and nothing about their trade-off is hidden — the full measured frontier is printed in the settings dialog, the losing region included.
Quantise Steps rounds the target to N reachable weights and requires price to clear 75% of a step before acting, so the weight does not twitch every bar. Ramp Width (xATR) sets how far above the mean price must travel to earn full size.
✂️ THE NADARAYA-WATSON SELL ENGINE
A trend weight cuts into weakness by construction, so it sells low: 59% of every unit the dial sells goes out below its own average cost, at 12.4 round trips a year. That is the flaw this block exists to fix. It replaces or constrains the sell side with a Gaussian kernel-regression envelope that only sells into genuine extension.
Sell Engine Mode — *Dial, NWE-gated* (default) keeps the dial's targets but forbids cutting while price sits below the smoother; it may still add. *NWE band only* turns the dial's sells off entirely. *Dial + NWE (both cut)* lets either one sell. *Dial only* leaves the envelope drawn but inert.
Sell Rungs is how much leaves on each upper-band cross: 1/N of the position. Going from 3 to 10 halved turnover, cut the share sold below basis from 16.7% to 8.9%, and pulled out-of-sample drawdown from −32.6% to −18.3%. It ships at 20, one step further along the same gradient; 10 is the last value with a formal table behind it.
Band Multiplier (3.0) and Buy-back Multiplier (2.5) set the upper and lower halfwidths in mean-absolute-deviation units. The asymmetry is the point: buying back nearer the mean than you sold restores the position before price has fully round-tripped, which is what keeps the overlay from bleeding in a chop. Bandwidth h widens and slows the smoother; it ships at 5.
🔬 HOW THIS WAS BUILT
Nine candidate signal families were tested against a matched-exposure control across 140 markets and 8,793 sessions: moving-average and momentum structure, cross-sectional relative strength, short-horizon mean reversion, volatility-of-volatility and regime transitions, drawdown state, volume, range compression, multi-timeframe agreement, and calendar seasonality. Not one was positive both in and out of sample. All nine were deleted from the codebase rather than left in as decoration.
The cleanest demonstration: take the original engine's own weight path and fire it 60 trading days late — same trades, same sizes, same turnover, same average exposure, only the dates broken. It scores better late than on time. Block-shuffling the path also beats it. A rule whose dates carry information cannot survive having them destroyed, so that engine was removed and what remains is geometry.
The stretch-proportional alternative to fixed rungs was then built and measured across 44 configurations. None beat rungs = 10. The project's pre-registered five-clause acceptance test passed all 20 graded cells — but a constant weight of 1.0 also passes three of five clauses, exactly one cell of twenty reaches p < 0.05 uncorrected (the null expectation for twenty tests), that p fails Bonferroni, and the cells are 0.985-correlated. It was reported as a failed test.
Everything left in this script survived a process designed to kill it. What remains is a sizing rule with no forecast in it: it does not predict the retest, it tells you at a price you can read now exactly what happens when one arrives.
⚙️ COSTS, AND THE SETTINGS THAT DECIDE THEM
Sell Engine Mode *Dial, NWE-gated*, Exposure Shape *Ensemble 20/50/100/200 (graded)*, c = 1.00, f = 0.00, Quantise Steps 3, Ramp 1.0 ATR, Trend Mean 200, Cash Yield 0.00%. Envelope: bandwidth 5, multiplier 3.0, buy-back 2.5, MAE window 499, Sell Rungs 20. Book notional 150,000, commission $1.50 cash per order, slippage 0.01xATR per side.
Slippage is charged in ATR units rather than ticks, because a tick is an absolute price and one tick count cannot be simultaneously correct for a $20 stock and a $1,600 one, nor for the same stock at $0.21 and at $224. A fraction of the instrument's own range travels between symbols; a tick count does not.
Cash Yield ships at 0.00%. The rule spends much of its life partly in cash, so any yield credited lands straight on the CAGR, and one constant cannot represent a twenty-year sample where real cash paid about 0.1% for eight years and about 5% for two. Every figure in the table above was measured with it at zero.
Exits are close-only by construction. The printed ladder is the memoryless level; the live quantiser is hysteretic, so the executed switch can sit up to 0.75 steps from the printed one.
🔁 THE STRATEGY BUILD
The same engine with orders attached is published separately as TURKS — Tiered Unit Risk Kernel Strategy, for anyone who wants the Strategy Tester's own accounting as a second opinion on the panel. Both builds compute the ladder, the envelope and the BOOK ledger from identical code.
© CREDIT
The envelope is a port of "Nadaraya-Watson Envelope " by LuxAlgo (www.tradingview.com), published open source under CC BY-NC-SA 4.0. The kernel, the MAE band construction and the crossover logic are theirs. This script is published under the same licence.
Only the non-repainting, one-sided causal branch was ported. LuxAlgo's script defaults to the repainting branch, which rebuilds its curve inside barstate.islast with a two-sided kernel, so the value at bar i averages bars on both sides of i — including bars that had not happened when i closed. That branch is deliberately absent here. The measured gap between the two is about 21% of the band halfwidth, which is why the repainting version's arrows look cleaner than any live rule can be. The sizing, the rung logic and the position accounting are new.
Open source, Pine v6.
אינדיקטור

Auction Scalper | GainzAlgo
Auction Scalper is built specifically for intraday scalpers. It uses Auction Market Theory to identify two high-quality setups: failed auctions that reverse back toward value and accepted breaks that continue after a retest.
THE TWO SETUPS
Reversal — Failed Auction
Price pushes outside yesterday's value area, fails to hold there, and closes back inside. The setup targets a return toward value, with the POC as TP1 and the stop placed beyond the full sweep with an ATR buffer.
Squeeze — Break & Retest
Price accepts outside value with a strong body close. The broken level is retested and must hold with sufficient participation before a continuation signal fires. Targets use meaningful prior-day levels, with a runner for extended moves.
EVERY SETUP GETS A 0–100 SCORE
Every setup is scored using:
Volume percentile
Buy/sell pressure
Rejection quality
Trade location
Higher-timeframe alignment
Volatility
Reward-to-risk
Time of day
Display the result as stars, a numerical score, or a letter grade.
Two additional rules come from testing: reversals against the higher-timeframe direction require a higher score, and setups requiring a stop wider than 4 ATR are skipped.
KNOW WHY YOU'RE FLAT
The dashboard shows your current trading window and system status.
It tells you whether the market is OPEN, LATE, CLOSED or in lockout, and whether the system is SCANNING, waiting for a higher score because of CHOP, MANAGING A TRADE, or DONE FOR TODAY.
No guessing why the indicator isn't giving you a signal.
BUILT FOR DISCIPLINED SCALPING
Includes:
Session filter & opening lockout
Late-entry cutoff
Chop detection
Signal cooldown
One active trade at a time
One long and one short setup per day
TP1 → break-even management
TP2 runner
Maximum stop-distance filter
Optional slippage-aware stops
Every trade is tracked directly on the chart with Entry, SL, TP1, TP2 and R multiples, including stop-outs.
VALIDATION
A companion strategy uses the same core logic so you can test it on your own market, timeframe, commission and slippage settings.
An earlier engine build tested on AAPL 5-minute data over one year produced a profit factor around 1.3 with drawdown near 2% using realistic costs. The engine has since been updated, so run the current strategy yourself for current results.
Settings were tuned on US stocks. Crypto and FX are supported but were not specifically calibrated.
HOW TO USE
Designed for liquid markets on 1–5 minute charts during active sessions.
Choose a preset, set your session, and wait for qualified setups. Alerts fire once per confirmed bar close with direction, setup type, score, entry, stop and both targets.
HONEST NOTES
Signals confirm on bar close and do not repaint. Higher-timeframe analysis uses only the last confirmed HTF bar.
Buy/sell pressure is estimated from candle structure, not exchange bid/ask data, and no lower-timeframe requests are required. The indicator therefore works across TradingView plans and in Bar Replay.
Some FX feeds have no usable volume, so the volume gate automatically steps aside when volume is unavailable.
This is an analytical tool, not financial advice. Past performance does not guarantee future results. אינדיקטור

Volume-Weighted Order Block Zones [BigBeluga]🔵 OVERVIEW
The Volume-Weighted Order Block Zones is an advanced technical indicator created by BigBeluga to identify and map institutional order blocks using pivot points and price displacement. Traditional order block indicators often highlight every single pivot zone, resulting in chart clutter and low-probability setups. In order to provide a solution to this problem, this indicator integrates volume-weighted strength calculations and ATR-based displacement triggers, ensuring that only high-momentum structural zones backed by significant volume are plotted.
The indicator aims to visualize institutional order-building and subsequent market expansions. The core element of its calculation involves tracking volume-weighted metrics against moving averages alongside a dynamic displacement formula defined as:
bearLevel = bearObHigh - atr * displacement
bullLevel = bullObLow + atr * displacement
where atr is the standard Average True Range of period 100, and displacement is the sensitivity multiplier. Higher values of displacement and minVolStrength allow the indicator to filter out weak market noise and focus exclusively on major institutional footprints.
🔵 FEATURES
The system utilizes a multi-layered matrix structure to provide actionable market intelligence:
1 — Swing & Volume-Weighted Detection Engine
Pivot Identification: Automatically tracks structural pivot highs and lows using a customizable swing length via pHigh = ta.pivothigh(high, swLen, swLen) and pLow = ta.pivotlow(low, swLen, swLen) .
Volume Strength Filtering: Calculates volume intensity percentages via f_getVolumeColor(vol, sma, baseColor) to filter out blocks falling below the minVolStrength threshold.
2 — Displacement Triggers & Order Block Mapping
Dynamic Trigger Lines: Projects live dashed trigger lines using line.new(bullObBar, bullLevel, bar_index, bullLevel, style=line.style_dashed) that extend dynamically until price achieves the required ATR displacement threshold.
Zone Visualization & Peak Labels: Plots high-precision order block boxes with volume percentage text alongside structural pivot high ( PH ) and pivot low ( PL ) labels.
3 — Active Zone Management & Retest Signals
Mitigation & Invalidation: Continuously monitors active zones inside the loop structure, automatically deleting order blocks when price breaches opposite boundaries or gets fully mitigated.
Retest Signals ( B / S ): Generates clear B (Bullish OB bounce) and S (Bearish OB rejection) signal labels when price retests active institutional zones.
🔵 HOW TO USE
Apart from the basic visualization of institutional market zones, this tool can also act in alternative ways to support decision-making:
Identify High-Volume Order Blocks: Look for newly formed order block boxes displaying strong volume percentages (e.g., above 20%+) to locate institutional liquidity entry points.
Manage Risk with Retest Labels: Monitor B and S retest signal labels to guide entries and manage stop losses as price interacts with active institutional zones.
🔵 NOTES
Why this implementation is unique:
It combines volume profile weighting directly with order block detection, filtering out low-volume traps automatically.
The dynamic live trigger line engine adapts seamlessly to real-time price action without cluttering historical chart data.
The script is fully optimized for Pine Script version 6, integrating robust array management var OB obBoxes = array.new() and dynamic box rendering for maximum performance.
אינדיקטור

אינדיקטור

Smart Entry Zones [StrixEDGE]█ OVERVIEW
StrixEDGE Smart Entry Zones is a multi-layered trend-following indicator that generates clearly defined trade setups with automatic Entry, Take Profit (TP 1–3), and Stop Loss (SL) levels — all plotted directly on the chart with exact prices and percentage targets.
The indicator is built on three independent analytical layers that work together to assess both timing and conviction:
• Supertrend — determines trend direction and triggers trade levels on each confirmed flip
• Fisher Transform — identifies overbought/oversold extremes for timing quality
• Chaikin Money Flow (CMF) — confirms whether volume supports the directional move
Trade levels appear the moment the Supertrend changes direction. The Fisher Transform and CMF score the quality of each setup on a scale of 1/3 to 3/3 conditions, so you always know how much confirmation backs the signal.
█ HOW IT WORKS
When the Supertrend flips from bearish to bullish, the indicator draws a LONG setup:
• Entry — at the close of the flip candle
• TP 1, TP 2, TP 3 — calculated as multiples of the risk (SL distance), based on your chosen Risk:Reward ratios
• SL — placed below entry at a distance of ATR × your chosen multiplier
When the Supertrend flips from bullish to bearish, a SHORT setup is drawn with the same structure, mirrored.
Each level displays the exact price and the percentage distance from entry (e.g., +4.12%, −2.27%), so you can instantly assess the reward-to-risk profile of every trade.
█ LIVE HIT DETECTION
The indicator tracks price in real time against active levels:
• ✓ appears on the chart when price reaches TP 1, TP 2, or TP 3
• ✕ appears when price hits the Stop Loss
• Once SL is hit, the trade is considered closed — no further TP checks
• Hit status is also reflected in the data table (✓ or ✕ next to each level)
This gives you a clear visual record of how each setup performed without leaving the chart.
█ THE THREE CONFIRMATION LAYERS
1. Supertrend (Direction)
Uses ATR-based dynamic support/resistance to define the prevailing trend. A flip in direction is the primary trigger for new trade levels. Configurable via ATR Period and Multiplier.
2. Fisher Transform (Timing)
A manually calculated oscillator that normalizes price position within its recent range and applies a logarithmic transformation to amplify extremes. When the Fisher value crosses its signal line at overbought or oversold levels, it confirms favorable entry timing. The threshold is adjustable.
3. Chaikin Money Flow (Volume)
Measures the accumulation/distribution pressure over a configurable period. Positive CMF above the threshold confirms buying pressure (for longs); negative CMF below the threshold confirms selling pressure (for shorts).
The Conditions counter in the data table shows how many of the three layers support the current setup (1/3, 2/3, or 3/3). A 3/3 reading means trend, timing, and volume are all aligned — the highest-conviction scenario.
█ SETTINGS
Core Parameters:
• Supertrend ATR Period (default: 10) — lookback for trend calculation
• Supertrend Multiplier (default: 3.0) — band width; lower = more signals, higher = fewer but stronger
• Fisher Transform Lookback (default: 10) — normalization window
• Fisher Extreme Threshold (default: 1.0) — defines overbought/oversold boundary
• CMF Period (default: 20) — volume pressure measurement window
• Minimum CMF Threshold (default: 0.05) — minimum reading for volume confirmation
Trade Levels:
• ATR Period for Levels (default: 14) — ATR used to calculate TP/SL distances
• SL Distance in ATR multiples (default: 1.5×) — how far the stop is placed
• TP1 / TP2 / TP3 Risk:Reward (defaults: 1.0 / 2.0 / 3.0) — each TP as a multiple of the SL distance
• Line Length in bars (default: 30) — how far the level lines extend on chart
• Show Trade Levels — toggle lines and labels on/off
Table Settings:
• Size (Tiny to Huge) and Position (any corner) — fully customizable
• Show/Hide toggle
█ DATA TABLE
A dark-header Style A panel displays all key metrics at a glance:
• Trend direction and current Fisher/CMF readings
• Conditions score (1/3, 2/3, or 3/3)
• Active trade direction (LONG ▲ or SHORT ▼)
• Entry price, TP 1–3 with percentage targets, and SL with percentage risk
• Live hit status: ✓ next to reached TPs, ✕ next to triggered SL
█ NOTES
• No repainting — all signals are based on confirmed bar closes. The Supertrend flip and Fisher Transform are calculated on closed data only.
• The Fisher Transform is manually implemented (not a built-in function) to ensure full transparency and consistency.
• This indicator is an analytical tool, not financial advice. Always use proper risk management and confirm setups with your own analysis.
█ ALERTS
Two built-in alert conditions:
• Supertrend Long — fires when Supertrend flips bullish
• Supertrend Short — fires when Supertrend flips bearish
Set alerts on any timeframe to receive notifications when new trade setups appear. אינדיקטור

Darvas Box Ladder [ITA]🟠 OVERVIEW
Darvas Box Ladder plots the rectangle Nicolas Darvas traded, and then keeps plotting the ones that follow it. Darvas did not buy a box and sell it - he rode a ladder of them, staying in as each breakout built a new box higher and lifting his stop to the floor of the newest one. He got out when a box finally broke down.
The script builds each box the way Darvas built it, as a sequence of confirmations rather than a rectangle fitted after the fact, and keeps the completed rungs on the chart so the whole run stays visible.
🟠 CONCEPTS
A Darvas box has an order to it. The ceiling comes first: price makes a new high, and that high has to survive a set number of bars unbeaten before it counts. Only then does the floor form, from the lowest low printed since the ceiling, and it has to survive the same test.
That order matters. A rectangle drawn around any quiet stretch of price is just a consolidation range. A Darvas box is a leader pausing after a run to new highs, and the ceiling-then-floor sequence is what separates the two.
Because both levels come from confirmed structure, they are fixed once drawn and do not move afterwards.
🟠 FEATURES
🔹 The full ladder, not one box - completed rungs stay on the chart so you can see the whole advance rather than the current pause in isolation
🔹 Stop line under the active box - a dashed line at the floor, which is where Darvas kept his
🔹 Measured-move target - one box height projected above the ceiling
🔹 Volume-confirmed breakouts - a close above the ceiling only counts when volume beats its 20-bar average by your chosen multiple
🔹 Box under construction - a dashed ceiling shows while the box is still forming, so you can see one coming before it completes
🔹 New-high filter - boxes may only start from a high that is the highest of the lookback window, keeping the script on leaders instead of drawing rectangles inside downtrends
🔹 Height limits - boxes outside your minimum and maximum are discarded
🔹 Alerts on both the breakout and the box breaking down
🟠 HOW TO USE
Add it to a daily chart of a stock that has been making new highs - that is the setup Darvas was looking for, and the new-high filter will keep the script quiet on anything else.
Watch for the dashed ceiling. That is a box forming. When the floor confirms, the box turns solid and the stop line appears underneath it.
A green box with a triangle below the bar is a confirmed breakout on volume, and the next box begins from there. Each new rung is a chance to lift the stop to the newer, higher floor.
A red box marks the end of the run - price closed below the floor.
Confirmation Bars is the main setting. Darvas used 3. Higher values give fewer, cleaner boxes; lower values react faster and produce more of them.
🟠 CONCLUSION
The box is the easy part. The ladder is what Darvas actually traded, and it is what tells you whether a breakout is the start of a run or the end of one. אינדיקטור

Liquidity Ladder+ (M1D)OVERVIEW
MTF Liquidity Ladder maps where resting orders sit above and below price, read from six timeframes at once — 1H, 4H, 7H, 1D, 3D and 1W — and draws only the closest few from each. Nothing else goes on the chart.
A level here is a SWING: a candle whose high dominated the candles either side of it on its own timeframe. That high is where buy stops rest, so it is buyside liquidity (BSL). A swing low is where sell stops rest, so it is sellside liquidity (SSL). A level comes off the chart the moment price trades through it, because liquidity that has been taken is not liquidity any more.
Every line is black and solid, because a pool carries no direction — it is neither bullish nor bearish, it is simply somewhere price may go to fill orders, and colouring it would imply a bias the level does not hold. Weight is the only ranking: the weekly is the widest line on the chart and the hourly the thinnest, so you know which timeframe a level belongs to before you have read its name.
Everything is evaluated on bar close. Confirmed levels do not repaint.
WHAT IT PLOTS
Swing levels from six timeframes. Buyside (swing highs) above price and sellside (swing lows) below it, for 1H, 4H, 7H, 1D, 3D and 1W. Each timeframe has its own on/off switch, its own line weight and its own right-hand runway.
Only the closest 1-10 per timeframe, per side. A pool forty handles away is not a decision you are about to make, and it costs exactly as much ink as the one you are. The default is two per timeframe per side. Levels further out stay tracked and appear the moment a nearer one is taken.
One label per level, at the right end of its own line. The name sits level with the price, no box behind it, in monospace. The line's right edge and the label's x are the same number used twice, so a name can never end up somewhere its line is not.
Six label columns. Each timeframe stops at its own distance past the live candle — by default 4, 7, 10, 15, 17 and 20 bars from 1H up to 1W — and parks its name there. The families land in six columns instead of contesting one patch of screen, and the column itself tells you the rank.
Dates on daily and above, prices on 4H and above. A daily or weekly level is worth dating, because which day made it changes what it means: the label reads 1D 19/07. An hourly level carries the tag alone. From 4H up, the label also carries the price, since a pool that size is one you plan around.
WHAT SEPARATES IT FROM A PREVIOUS-HIGH / PREVIOUS-LOW SCRIPT
Levels that share a price become ONE level. Two swings resting within a few ticks of each other are one pool, not two. Drawn separately they produce two lines at the same height and two names fighting for the same space. Here they merge into a single line in the senior timeframe's column, at its weight, carrying every tag that sits there — 4H·1H. A candidate is tested against the whole group's envelope rather than just its first member, so a chain of near-misses cannot walk a group away from where it started. Never two names for one price, and never a name nudged off the level it belongs to.
Lines anchor to the exact bar that made the swing. A higher-timeframe pivot only knows which CANDLE made it. Anchor the line at that candle's open and a 4H level begins up to four hours to the left of the high it is named after — visibly adrift from the swing it describes. This script follows each timeframe's candle as it forms, records the exact chart bar its high and its low printed on, and anchors there instead. The date in the label names that same bar. A level older than the chart's loaded history has no bar to anchor to; it falls back to the candle's open, and its origin is off the left edge regardless.
A distance gate, because lines pull the price scale. A weekly pool six hundred points away on a one-minute chart does not sit quietly off-screen. The pane stretches to include it and every candle you were actually reading is flattened into a band. With six timeframes drawing at once that is a chart you cannot trade from. So nothing draws further from price than a multiple of the recent range — the last 300 bars, high to low, which tracks the instrument and the chart timeframe on its own. It gates DRAWING only: the level stays tracked, stays swept, stays alerted, and reappears as soon as price comes back within reach.
SETTINGS
Timeframes
One row per timeframe: draw it, how many bars past the live candle it runs, and how heavy its line is. Defaults 1H 4/1, 4H 7/1, 7H 10/1, 1D 15/2, 3D 17/2, 1W 20/3.
The weekly is always the heaviest line and never thinner than 2. If another timeframe is set wider, the weekly is lifted to match rather than the other being cut — no setting is discarded, but the hierarchy holds.
A timeframe hides itself when the chart timeframe reaches or passes it. A 1H level on a 4H chart is not a level, it is the bar you are standing on.
Levels
Levels per timeframe: 1-10, default 2.
Buyside and Sellside toggles, both on.
Swing strength — bars either side a candle must dominate to count as a swing, default 3.
Merge tolerance in ticks, default 4. Zero merges only prices that match exactly.
Distance gate, as a multiple of the recent range, default 1.5. Zero switches it off.
Labels
Text size, default small.
Date on 1D, 3D and 1W labels, on.
The words BSL and SSL, off by default — a level above price is Buyside and one below is Sellside, so the words repeat what the chart already says.
Price: Off, 4H and above (default), or Every level.
Alerts
Announce a sweep from this timeframe up, default 4H.
ALERTS
Sweeps below the chosen floor stay silent. A 1H pool gets tickled all session, and an alert on every one is an alert you stop reading.
A dynamic alert, at most one per bar, naming the most senior pool taken and the price it went at — for example: 4H BSL taken · 29750.00 · MNQ1!. To use it, choose "Any alert() function call" in the alert dialog.
Two fixed conditions, BSL taken and SSL taken, for anyone who prefers a plain trigger. Both respect the same floor.
NOTES
Dates are read in New York time on every instrument. An exchange's own timezone would date a CME swing in Chicago, putting a late-evening level on a different day to the rest of a New-York-based workflow.
Toggles and the distance gate affect drawing only. Detection keeps running underneath, so tidying the chart never quietly loses the analysis behind it.
Line and label objects are created once and reused rather than deleted and rebuilt each bar, so the chart does not flicker as price moves between levels.
Six request.security() calls, one per timeframe, all with lookahead off.
Disclaimer
This is an analysis tool. It marks where liquidity rests and when it is taken; it does not generate entries, exits or signals, and it makes no claim about what price will do next. אינדיקטור

אינדיקטור