Tech Leadership Map+ [Herman]Tech Leadership Map
Tech Leadership Map is a relative-market leadership indicator designed to show whether technology-focused market activity is currently leading, lagging, or moving without a clear advantage relative to the broader US equity market.
The indicator does not generate traditional buy or sell signals. Instead, it provides an additional market-context layer that can help traders evaluate whether current market participation supports or conflicts with the directional move they are analyzing.
It includes two selectable and independent leadership models:
* **Price**
* **Volume Pressure**
Both models convert several measurements into a standardized four-component composite score.
---
Why Tech Leadership Matters
Technology shares represent an important component of US equity index activity, particularly for Nasdaq-related instruments.
When technology is outperforming the broader market, Nasdaq-focused markets may be receiving stronger relative participation. When technology is underperforming, broader-market strength may not be confirmed by technology leadership.
This indicator attempts to make that relationship easier to observe directly on the chart.
It should be treated as a **relative-market context tool**, not as a standalone forecasting system.
---
Leadership States
The indicator evaluates four separate components.
Each component contributes:
**+1** = favors the selected technology leader
**0** = neutral / unavailable confirmation
**-1** = favors the benchmark
The resulting Composite Score can therefore range from:
**+4 to -4**
The default classification is:
** GREEN — Tech Leading**
Composite Score of +2 or higher.
Technology-oriented activity is showing stronger relative leadership than the selected benchmark.
** YELLOW — No Clear Edge**
Composite Score between -1 and +1.
The measurements are mixed and neither side has sufficient agreement to establish a clear leadership state.
** RED — Tech Lagging**
Composite Score of -2 or lower.
Technology-oriented activity is showing weaker relative leadership than the selected benchmark.
These colors describe the current relative-leadership condition. They do not represent predictions of future price direction.
---
# 1. PRICE MODE
The default Price model compares:
**QQQ — Price Leader**
with
**SPY — Price Benchmark**
Both symbols can be changed in the indicator settings.
The model evaluates four components.
### 1. Performance From RTH Open
The indicator measures the percentage performance of QQQ and SPY from the beginning of the configured US Regular Trading Hours session.
It then compares those performances.
If QQQ has performed better from the RTH open, the component favors the leader.
If SPY has performed better, it favors the benchmark.
---
### 2. Relative-Strength Ratio Slope
The indicator calculates the relative-strength relationship:
**QQQ / SPY**
The logarithm of this ratio is evaluated using a linear-regression slope.
A rising relative-strength relationship indicates improving technology leadership.
A falling relationship indicates weakening technology leadership relative to the benchmark.
---
### 3. Short-Term Momentum Difference
The model compares short-term rate-of-change momentum between the leader and benchmark.
By default, this component uses a 5-bar momentum comparison.
This allows the indicator to identify situations where both markets may be moving in the same direction while one is accelerating more strongly than the other.
---
### 4. Correlation-Break Confirmation
QQQ and SPY normally exhibit a relatively high degree of correlation.
The indicator measures correlation between their logarithmic returns.
When correlation falls below the model's internal threshold, the short-term momentum difference receives an additional confirmation vote.
The purpose of this component is to emphasize periods where relative movement becomes more meaningful because the two markets are no longer behaving as closely together.
---
# 2. VOLUME PRESSURE MODE
Volume Pressure provides an alternative model that does **not use QQQ/SPY price movement to determine leadership**.
The default market-internal sources are:
**NASDAQ: VOLDQ**
versus
**Broad Market / NYSE: VOLD**
These represent net up-volume minus down-volume market internals.
The symbols are editable because VOLDQ and VOLD represent different market universes and should not be interpreted as literal constituent-by-constituent equivalents of QQQ and SPY.
---
## Normalization
NASDAQ and broad-market internal series can operate on substantially different numerical scales.
For that reason, the indicator first normalizes each series independently before comparing them.
This prevents the raw numerical magnitude of one internal from automatically dominating the comparison.
---
## Volume Pressure Components
The model then evaluates four measurements.
### 1. Pressure Level
Compares the current normalized leader pressure with the normalized benchmark pressure.
---
### 2. Fast Pressure
Applies short-term smoothing to both normalized internal series and compares their relative position.
This helps reduce some bar-to-bar noise while preserving short-term changes in leadership.
---
### 3. Pressure Momentum
Measures the change in normalized internal pressure over the selected momentum lookback.
This identifies which market internal is currently improving or deteriorating faster.
---
### 4. Pressure Impulse
Each normalized internal is compared with its own slower baseline.
The difference between those impulses determines which market is showing the stronger deviation from its recent baseline.
---
# Chart Display
The default visualization uses colored dots placed along the chart.
The colors correspond directly to the current leadership state:
**Green = Tech Leading**
**Yellow = No Clear Edge**
**Red = Tech Lagging**
Optional chart-bar coloring can also be enabled.
By default, leadership dots are displayed only during the configured US Regular Trading Hours session:
**09:30–16:00 New York time**
This behavior can be changed in the settings.
---
# Statistics Table
The optional statistics table provides additional information about the active model.
Depending on the selected source, it displays:
* active leadership source
* current leadership state
* Composite Score
* individual component votes
* correlation in Price mode
* normalized internal gap in Volume Pressure mode
The table is intended to make the calculation transparent rather than displaying only the final color.
---
# How to Use It
The indicator is primarily intended as a **confirmation and market-context tool**.
For example, when analyzing a Nasdaq-related market, a trader may compare the current directional setup with the technology leadership state.
A bullish market setup occurring while technology is leading represents a different relative-market environment from the same setup occurring while technology is lagging.
Similarly, a bearish setup occurring while technology leadership is weakening may provide different contextual information from one occurring during strong technology leadership.
The indicator does not determine whether a trade should be entered. Entry, exit, risk management, market structure, liquidity, volatility, news conditions, and other factors remain separate trading decisions.
---
# Alerts
Three state-change alerts are available:
* Technology leadership becomes positive
* Technology leadership becomes negative
* Leadership becomes mixed
Alerts trigger when the composite state transitions into the corresponding condition.
---
# Repainting / Realtime Behavior
The indicator is designed without future-data references.
All external symbol requests use `lookahead_off`, and the script does not reference future bars or negative offsets.
However, values on the **currently forming realtime bar can change until that bar closes**, because the underlying markets and market internals are still updating.
Historical completed bars represent the final calculated state for those completed chart bars.
Users who require confirmed information should therefore evaluate the state after the relevant bar has closed.
---
# Data Availability
The indicator depends on external TradingView symbols.
Price mode requires valid data for the selected Price Leader and Price Benchmark.
Volume Pressure mode requires valid data for the selected market-internal symbols.
Availability of individual symbols can vary depending on TradingView data access, exchange coverage, account configuration, or symbol availability.
If the required data is unavailable, the indicator reports that state rather than attempting to substitute another source automatically.
---
# Originality
Tech Leadership Map combines two distinct approaches to relative-market analysis inside one standardized leadership framework.
Rather than displaying QQQ/SPY relative strength or market internals as isolated raw series, the indicator evaluates several independent characteristics of leadership and converts them into a transparent four-vote Composite Score.
The Price model evaluates:
* session-relative performance
* relative-strength trend
* relative momentum
* correlation-based confirmation
The Volume Pressure model independently evaluates:
* normalized internal pressure
* smoothed pressure leadership
* internal momentum
* pressure impulse
Both engines produce the same standardized leadership states, allowing users to compare price-based leadership with non-price market-internal participation using a consistent visual framework.
The complete Pine Script source code is published openly so users can inspect the calculations and understand exactly how each state is derived.
---
## Important Notes
This indicator is an analytical tool and is not intended to provide investment advice or guarantee future market performance.
Leadership describes a relative condition between the selected markets or market internals. It should not be interpreted as a prediction that the charted instrument must rise or fall.
Users should evaluate the indicator together with their own analysis, trading methodology, and risk-management process. Gösterge

Gösterge

Gösterge

Intraday Master ProHere is a comprehensive customer-facing explanation and guide for your Intraday Master Pro indicator, written in clear, professional English, complete with a concise legal disclaimer at the end.
Welcome to Intraday Master Pro
Intraday Master Pro is a high-precision trading script engineered to identify high-probability intraday opportunities by filtering momentum, volume, and multi-timeframe alignment into automated trade setups.
Key Features
Multi-Timeframe Trend Dashboard: Real-time alignment checks across the 1m, 5m, and 15m timeframes.
Dynamic Trend Flow Band: Visual volatility channels indicating overall market bias.
Precision Entry Signals: Volume-filtered entries based on EMA crossovers and RSI constraints.
Automated Risk Management: Dynamic Stop Loss (SL) and 3 Take Profit targets (TP1, TP2, TP3) anchored directly to active signal bars.
Setup Rating Score (1–100): Real-time setup scoring algorithm based on multi-timeframe concordance and volume strength.
How It Works
1. High-Precision Signals & Entry Conditions
The indicator issues BUY or SELL labels only when multiple conditions align:
Trend & Momentum: Fast and Slow EMA crossovers filtered by RSI.
Volume Confirmation: Spikes exceeding 1.25x the 20-period volume average.
Cooldown Guard: Built-in bar cooldown filters to prevent whipsaws during choppy consolidated markets.
2. Multi-Timeframe Dashboard & Setup Rating
Located on the right side of your chart, the dashboard updates live:
1m / 5m / 15m Trend Status: Green (BULL) or Red (BEAR) depending on price position relative to core moving averages.
Setup Rating (1 to 100): A live score grading the quality of the current setup.
80–100 (Green): High-confluence setup across all timeframes and volume.
60–79 (Orange): Moderate setup; proceed with standard risk.
Below 60 (Gray): Low confluence or weak trend.
3. Dynamic Stop Loss & Take Profit Levels
When a valid signal triggers, the indicator projects extended level lines onto your chart:
SL (Orange Line): Calculated dynamically using ATR based on recent market volatility.
TP1 (1.5x R:R): Partial profits / initial target.
TP2 (2.8x R:R): Main target.
TP3 (4.5x R:R): Extended runner target for strong trending days.
How to Use Intraday Master Pro
Wait for a Signal: Look for a clear BUY or SELL label on the chart.
Check Confluence: Glance at the Dashboard. Look for Setup Ratings of 80/100 or higher and alignment across 1m, 5m, and 15m timeframes for maximum statistical edge.
Set Orders: Place your Stop Loss at the SL line and split your position across TP1, TP2, and TP3.
Manage Risk: Once price reaches TP1, consider moving your Stop Loss to entry (Breakeven) to lock in a risk-free trade while riding the position to TP2 and TP3.
Settings & Configuration
Risk Management Inputs: Adjust Core Sensitivity or Volatility Factor to widen or tighten stop-loss distances based on the asset’s volatility.
Visuals: Toggle the Dashboard or Flow Band visibility on/off and customize accent colors to fit dark or light charts.
Disclaimer
The Intraday Master Pro indicator is designed strictly for educational and informational purposes and does not constitute financial, investment, or trading advice. Past performance is not indicative of future results. Trading equities, options, forex, and cryptocurrencies involves significant financial risk and can result in the loss of your capital. Always practice proper risk management and consult a licensed financial advisor before executing trades. Gösterge

Volatility RegimeVolatility Regime
OVERVIEW
This indicator classifies the current market into one of three volatility regimes — Low, Medium, or High — and displays them in a separate panel below the price chart. Rather than measuring volatility in absolute terms, it evaluates how current volatility compares to its own recent history, so the classification adapts automatically to any instrument and timeframe without needing manual recalibration.
METHODOLOGY
Volatility is calculated as the standard deviation of logarithmic returns over a user-defined lookback period. That value is then compared to its own distribution over a longer historical window using a percentile rank calculation. The result is a 0-100 reading showing where current volatility stands relative to its own recent history, rather than relying on a fixed, one-size-fits-all threshold that would behave differently across instruments.
COMPONENTS
- Volatility Percentile Rank line: plots the 0-100 percentile reading of current volatility, colored according to the active regime.
- Threshold lines: two dashed horizontal lines mark the Low and High volatility thresholds (default 33 and 66), both adjustable.
- Panel background shading: the background of the indicator panel is tinted according to the active regime for quick visual reference.
- Regime label: a label on the most recent bar displays the current regime as text (LOW / MEDIUM / HIGH).
REGIMES
- Low Volatility Regime: percentile rank at or below the low threshold. Current volatility is compressed relative to its recent history.
- Medium Volatility Regime: percentile rank between the two thresholds. A transitional or average volatility state.
- High Volatility Regime: percentile rank at or above the high threshold. Current volatility is expanded relative to its recent history.
PURPOSE
This tool adds volatility context to trading decisions rather than generating direct buy or sell signals. Market behavior tends to differ meaningfully across volatility regimes, and being aware of the active regime can help with position sizing, stop placement, and identifying which type of setups are more likely to be relevant at a given time.
HOW TO USE IT
- Check the current regime shown in the panel before evaluating a setup on the main chart.
- Consider adjusting position size and stop-loss distance according to the active regime — wider stops and smaller size are generally more appropriate in high volatility conditions, and the opposite in low volatility conditions.
- A prolonged Low Volatility Regime can indicate the market is compressing and may be approaching an expansion phase.
- Volatility Length, Percentile Rank Lookback, and both threshold levels are adjustable in the settings to fit different instruments and timeframes.
NOTES
This indicator is a contextual tool intended to support discretionary or systematic analysis. It does not predict market direction and should be used alongside a broader trading methodology and proper risk management. Gösterge

Gösterge

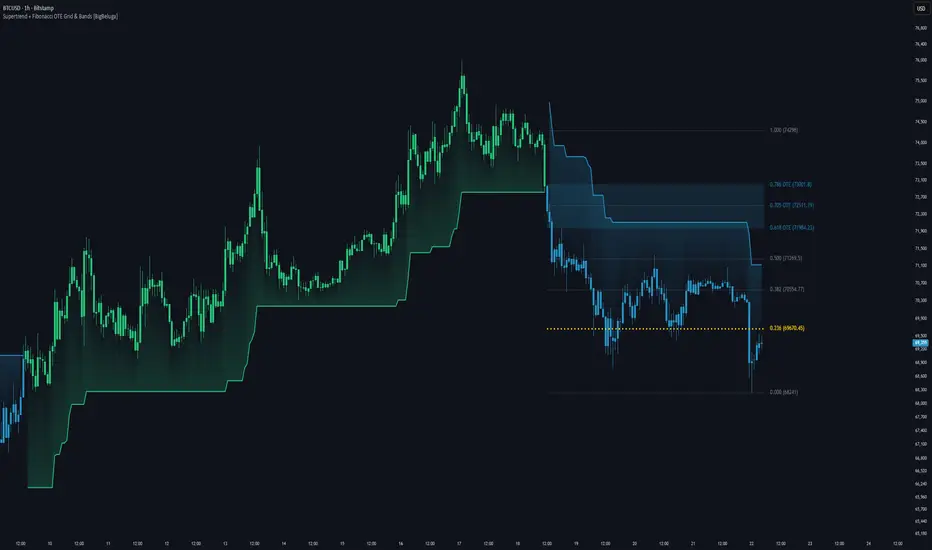
Supertrend + Fibonacci OTE Grid & Bands [BigBeluga]🔵 OVERVIEW
The Supertrend + Fibonacci OTE Grid & Bands is an advanced technical analysis indicator designed by BigBeluga to combine trend-following Supertrend mechanics with dynamic Fibonacci retracement grids and volatility-based channel bands directly on the chart. Traditional Supertrend systems rely solely on stop lines, often missing optimal retracement zones (OTE) during trend pullbacks. To solve this limitation, this script integrates dual operating modes—anchored OTE grids that project Fibonacci levels across active trend swings, and continuous Fibonacci channel bands scaled by Average True Range (ATR).
The indicator visualizes trend direction, dynamic stop losses, shaded OTE zones, and proximity-highlighted grid levels. The core calculations track trend swings using customizable ATR lookbacks, compute proportional Fibonacci levels (0.0 to 1.0), and dynamically adjust line widths and colors when price approaches specific thresholds. Custom color palettes, bar/candle color toggles, and label configurations allow traders to fine-tune visual settings across various timeframes and asset classes.
🔵 HOW IT WORKS
The system operates through an integrated architecture where each component dynamically influences chart behavior:
1 — Supertrend Trend & Swing Engine
Stop Loss Line & Fills: Computes volatility-scaled Supertrend lines using ATR parameters, plotting colored stop-loss streams with gradient area fills.
Trend Extreme Tracking: Automatically tracks trend highs and lows upon trend direction flips to anchor structural Fibonacci calculations.
2 — Dual Fibonacci Modes (OTE Grid & Bands)
OTE Grid Mode: Projects an anchored Fibonacci retracement grid (0.0, 0.236, 0.382, 0.500, 0.618, 0.705, 0.786, 1.000) across the active trend swing, complete with a shaded Optimal Trade Entry (OTE) zone between the 0.618 and 0.786 levels.
Fibonacci Bands Mode: Plots continuous, ATR-scaled channel bands extending outward from the Supertrend line using proportional ratio offsets.
3 — Proximity Highlight & Styling Engine
Price Proximity Detection: Measures distance between price and individual grid levels using ATR multipliers to dynamically highlight active levels with distinct colors and thicker line widths.
Visual Customization: Supports bar and custom candle coloring by trend, adjustable line styles (Solid, Dotted, Dashed), and dynamic right-edge price labels.
🔵 HOW TO USE
Apart from serving as a comprehensive trend and retracement mapping tool, the indicator can be applied in several ways:
Follow Trend Momentum: Stay aligned with prevailing market direction by monitoring the Supertrend line color and trend-colored candles/bars.
Identify OTE Retracement Zones: In OTE Grid mode, monitor the shaded zone between the 0.618 and 0.786 Fibonacci levels for potential trend continuation entries during pullbacks.
Track Key Level Interactions: Watch for automatic color highlights and width changes on grid levels as price approaches critical Fibonacci thresholds.
🔵 SETTINGS
The indicator includes several customizable configuration groups to tailor calculations and visual styling to your trading style:
General Settings: Select between OTE Grid and Fibonacci Bands modes, toggle right-edge price/ratio labels, choose grid line styles (Solid, Dotted, Dashed), adjust grid highlight distance thresholds via ATR multipliers, and enable dimming for non-OTE levels.
Supertrend Parameters: Configure the ATR Period and Multiplier to adjust the sensitivity and distance of the core stop-loss line.
Fibonacci Bands Parameters: Define the ATR period and outer band multiplier specifically used when operating in Fibonacci Bands mode.
Main Styling & Colors: Set bullish and active price highlight colors, and toggle bar/candle coloring based on the active trend direction.
Fibonacci Level Settings: Enable or disable individual Fibonacci ratios (0.000, 0.236, 0.382, 0.500, 0.618, 0.705, 0.786, 1.000) and customize their individual display colors.
🔵 NOTES
Why this implementation is unique:
It merges classic Supertrend stop mechanics with both anchored OTE grids and continuous Fibonacci channel bands.
Features dynamic price proximity highlighting and custom linefill engines optimized for Pine Script version 6.
Provides extensive modular inputs for styling, level visibility, and operational mode switching.
Gösterge

DNSE VN301!, BB-SMA Trend Following "Bollinger Bands Breakout with SMA Trend Filter" is a volatility-based trend-following strategy designed to capture strong directional price movements when price breaks beyond its recent volatility range. The strategy uses Bollinger Bands with a default SMA(20) basis and 2.0 standard deviations to identify bullish breakouts above the upper band and bearish breakouts below the lower band.
To improve signal quality, the strategy combines Bollinger Band breakouts with a mandatory SMA(200) trend filter, allowing Long trades only when the SMA is rising and Short trades only when it is falling. By combining volatility expansion with broader trend confirmation, the strategy seeks to reduce counter-trend and false breakout signals while participating in stronger intraday movements. It also includes configurable stop loss, take profit, trading session, trade direction, and automatic end-of-session position closure for disciplined risk management.
Strategy settings and configuration:
Chart timeframe: recommended 5-minute chart
Position size: 3 contracts
Bollinger Bands length: 20
Bollinger Bands multiplier: 2.0
SMA length: 200
Stop loss: 10 points
Take profit: 20 points
SMA trend filter: always enabled
Take profit: On / Off
Time filter: On / Off
Trading session: 09:00 – 14:30
Trade direction: Long / Short / Both
Default script settings:
The strategy calculates Bollinger Bands using the SMA(20) of the closing price. The upper and lower bands are created by adding or subtracting two standard deviations around the middle line.
When the closing price breaks above the upper Bollinger Band, buying pressure may be taking control. When the closing price breaks below the lower Bollinger Band, selling pressure may be taking control.
SMA(200) is used as the main trend filter. When SMA(200) is rising, the script only allows Long trades. When SMA(200) is falling, the script only allows Short trades.
In CNPS 04, the SMA(200) filter is always enabled. This helps the bot filter out breakout signals that go against the longer-term trend.
Users can add the built-in Bollinger Bands indicator on TradingView with Length 20 and Multiplier 2.0 to visually monitor the signal on the price chart.
Entry and exit rules:
Long entry:
Closing price > upper Bollinger Band
AND SMA(200) is rising
AND the signal appears during the trading session
AND trade direction allows Long entries
Long exit:
Stop loss: 10 points from entry price
Take profit: 20 points from entry price, if enabled
Opposite breakout signal appears
Reversal when a valid Short signal appears
Automatic position close at the end of the trading session
Short entry:
Closing price < lower Bollinger Band
AND SMA(200) is falling
AND the signal appears during the trading session
AND trade direction allows Short entries
Short exit:
Stop loss: 10 points from entry price
Take profit: 20 points from entry price, if enabled
Opposite breakout signal appears
Reversal when a valid Long signal appears
Automatic position close at the end of the trading session
Risk disclaimer:
Futures trading involves a high level of risk and prices can move sharply. This script is provided for reference, research, and backtesting purposes only. Users should fully understand derivatives trading, their own risk tolerance, and the strategy logic before applying it to live trading.
All investment decisions are the responsibility of the user. phaisinh.online is not responsible for any losses arising from the use of this strategy in real trading. Past performance does not guarantee future results.
_________________________________________________________________
"Bollinger Bands Breakout với Bộ lọc Xu hướng SMA" là một chiến lược giao dịch theo xu hướng dựa trên biến động, được thiết kế nhằm nắm bắt các chuyển động giá mạnh theo một hướng khi giá phá vỡ khỏi vùng biến động gần nhất. Chiến lược sử dụng Bollinger Bands với đường cơ sở mặc định là SMA(20) và 2,0 độ lệch chuẩn để xác định tín hiệu bứt phá tăng khi giá vượt lên trên dải trên và tín hiệu bứt phá giảm khi giá xuống dưới dải dưới.
Để nâng cao chất lượng tín hiệu, chiến lược kết hợp tín hiệu bứt phá Bollinger Bands với bộ lọc xu hướng SMA(200) bắt buộc, chỉ cho phép giao dịch Long khi SMA đang dốc lên và giao dịch Short khi SMA đang dốc xuống. Bằng cách kết hợp sự mở rộng của biến động với xác nhận xu hướng tổng thể, chiến lược hướng tới việc giảm thiểu các tín hiệu giao dịch ngược xu hướng và các tín hiệu phá vỡ giả, đồng thời tận dụng các chuyển động intraday mạnh hơn. Chiến lược cũng bao gồm các tùy chọn Stop Loss, Take Profit, khung thời gian giao dịch, hướng giao dịch và cơ chế tự động đóng vị thế khi kết thúc phiên, nhằm đảm bảo quản trị rủi ro một cách chặt chẽ và có kỷ luật.
Cài đặt & cấu hình chiến lược:
Biểu đồ: khuyến nghị khung 5 phút
Khối lượng giao dịch: 3 hợp đồng
Chu kỳ Bollinger Bands: 20
Hệ số nhân Bollinger Bands: 2.0
Chu kỳ SMA: 200
Cắt lỗ: 10 điểm
Chốt lời: 20 điểm
Bộ lọc xu hướng SMA: luôn bật
Dùng chốt lời: Bật / Tắt
Bộ lọc giờ: Bật / Tắt
Khung giờ giao dịch: 09:00 – 14:30
Chiều giao dịch: Mua / Bán / Cả hai
Cài đặt mặc định của script:
Chiến lược tính toán Bollinger Bands dựa trên đường SMA(20) của giá đóng cửa. Dải trên và dải dưới được tạo bằng cách cộng hoặc trừ hai độ lệch chuẩn quanh đường giữa.
Khi giá đóng cửa vượt lên trên dải trên Bollinger Bands, lực mua có thể đang chiếm ưu thế. Khi giá đóng cửa phá xuống dưới dải dưới Bollinger Bands, lực bán có thể đang chiếm ưu thế.
SMA(200) được dùng làm bộ lọc xu hướng chính. Khi SMA(200) dốc lên, script chỉ cho phép lệnh Mua. Khi SMA(200) dốc xuống, script chỉ cho phép lệnh Bán.
Trong CNPS 04, bộ lọc SMA(200) luôn bật. Điều này giúp bot loại bỏ bớt các tín hiệu breakout đi ngược xu hướng dài hạn.
Người dùng có thể thêm chỉ báo Bollinger Bands có sẵn trên TradingView với tham số Length 20 và Multiplier 2.0 để quan sát tín hiệu trực quan trên biểu đồ giá.
Điều kiện vào và thoát lệnh:
Vào lệnh Mua:
Giá đóng cửa > dải trên Bollinger Bands
VÀ SMA(200) dốc lên
VÀ tín hiệu xuất hiện trong khung giờ giao dịch
VÀ chiều giao dịch cho phép lệnh Mua
Thoát lệnh Mua:
Cắt lỗ: 10 điểm từ giá vào lệnh
Chốt lời: 20 điểm từ giá vào lệnh, nếu bật
Có tín hiệu breakout ngược chiều
Đảo chiều khi xuất hiện tín hiệu Bán hợp lệ
Tự động đóng lệnh khi hết khung giờ giao dịch
Vào lệnh Bán:
Giá đóng cửa < dải dưới Bollinger Bands
VÀ SMA(200) dốc xuống
VÀ tín hiệu xuất hiện trong khung giờ giao dịch
VÀ chiều giao dịch cho phép lệnh Bán
Thoát lệnh Bán:
Cắt lỗ: 10 điểm từ giá vào lệnh
Chốt lời: 20 điểm từ giá vào lệnh, nếu bật
Có tín hiệu breakout ngược chiều
Đảo chiều khi xuất hiện tín hiệu Mua hợp lệ
Tự động đóng lệnh khi hết khung giờ giao dịch
Tuyên bố rủi ro:
Giao dịch hợp đồng tương lai có mức độ rủi ro cao và giá có thể biến động mạnh. Script này chỉ phục vụ mục đích tham khảo, nghiên cứu và kiểm thử. Người dùng cần hiểu rõ giao dịch phái sinh, khẩu vị rủi ro cá nhân và logic của chiến lược trước khi áp dụng vào giao dịch thực tế.
Mọi quyết định đầu tư thuộc trách nhiệm của người dùng. phaisinh.online không chịu trách nhiệm cho bất kỳ khoản lỗ nào phát sinh từ việc sử dụng chiến lược này trong giao dịch thực tế. Hiệu quả trong quá khứ không đảm bảo kết quả trong tương lai.
Strateji

JFX Structure FibJFX Structure Fib
ENGLISH
JFX Structure Fib is a multi-timeframe market-structure and automatic Fibonacci retracement framework designed for discretionary traders. It does not generate BUY/SELL signals or manage trades. Its purpose is to organize higher-timeframe directional context, confirmed chart-timeframe structure breaks, and retracement levels into one clean workflow.
HOW IT WORKS
1. Adaptive bias timeframe
By default, the script automatically assigns a higher bias timeframe according to the active chart timeframe. Examples include M5 -> H1 and M15 -> H4. A Custom mode is also available for users who prefer a different higher-timeframe relationship.
2. Confirmed higher-timeframe bias
The bias engine reads confirmed higher-timeframe structure. An optional Structure + EMA mode can require both structural direction and EMA alignment. The higher-timeframe values are based on completed higher-timeframe bars to reduce discrepancies between historical and realtime behavior.
3. Valid chart-timeframe BOS
The script displays only BOS events that meet its structural rules. A valid BOS requires a confirmed close through a confirmed swing that has not already been counted as broken, alignment with the active higher-timeframe bias, and a valid opposite structural swing after the broken swing to serve as the impulse origin.
4. BOS-origin impulse tracking
After a valid BOS, the script tracks the continuing impulse rather than fixing the Fibonacci endpoint immediately. The impulse extreme remains dynamic until price produces the configured confirmed retracement. This reduces arbitrary Fibonacci anchoring while an impulse is still extending.
5. Automatic Fibonacci lock
When the retracement threshold is confirmed, the impulse is locked and the script plots four configurable Fibonacci retracement levels. Defaults are 0.618, 0.705, 0.790, and 0.886. The chart displays ratio values only, without prices.
6. Fibonacci history
Completed or superseded Fibonacci structures can be retained as bounded historical references. Users can choose how many recent Fibonacci structures remain visible. Historical levels are visually muted so the active structure remains easy to identify.
7. Compact dashboard
The dashboard summarizes the chart-to-bias timeframe mapping, confirmed higher-timeframe bias, current structural direction, Fibonacci state, and retained Fibonacci history.
HOW TO USE IT
- Apply the indicator to the timeframe on which you want to analyze structure.
- Leave Bias timeframe mode on Auto for the default multi-timeframe mapping, or select Custom if your framework uses a different higher timeframe.
- A bullish or bearish BOS is displayed only when the script's validity conditions are satisfied.
- After the post-BOS impulse retraces by the configured lock threshold, the Fibonacci structure becomes fixed and its retracement levels are displayed.
- Use the Fibonacci levels as location/context within your own trading plan. The script intentionally does not define entries, stop losses, take profits, or expected performance.
KEY SETTINGS
- Bias timeframe mode: Auto or Custom.
- Bias method: Structure or Structure + EMA.
- Bias and chart-structure pivot sensitivity.
- Use newest valid BOS: allows a newer valid BOS to supersede the current structure.
- Structure invalidation: close or wick beyond the impulse origin.
- Fibonacci lock retracement.
- Four customizable Fibonacci ratios.
- Optional minimum impulse size measured in ATR.
- Fibonacci history count.
- Optional bias/chart swing reference levels.
- BOS, Fibonacci, dashboard, and alert visibility controls.
ORIGINALITY AND PROTECTED-SOURCE RATIONALE
BOS, market structure, and Fibonacci retracement are established concepts and are not claimed as original inventions. The original contribution of this script is the specific workflow and implementation that connects adaptive higher-timeframe bias, valid BOS filtering, post-break structural-origin selection, dynamic impulse tracking, confirmed retracement locking, bounded Fibonacci lifecycle/history, and a chart-focused visual state model. The source is protected to preserve this implementation while allowing the community to use the indicator freely.
LIMITATIONS
- Confirmed pivots require right-side bars before a swing is known. This means structure detection intentionally has confirmation delay.
- The higher-timeframe bias uses completed higher-timeframe information, so it will react more slowly than an indicator using an unfinished higher-timeframe candle.
- The automatic timeframe mapping is a practical default, not a universal rule. Different instruments or trading plans may require Custom mode.
- BOS validity depends on the selected pivot sensitivities. Very low settings can identify more minor structure; higher settings can identify fewer but broader swings.
- Fibonacci levels describe retracement location only. They do not establish that price will reverse from a level.
- The script does not calculate trade entries, stop losses, take profits, win rate, profit factor, or profitability.
- A newer valid BOS can replace the active structure when that option is enabled.
- Market behavior varies by instrument, timeframe, volatility regime, session, data feed, and execution environment.
Use the indicator as an analytical framework and validate its behavior on the instruments and timeframes relevant to your own process before relying on it for live decisions.
BAHASA INDONESIA
JFX Structure Fib adalah framework market structure multi-timeframe dan automatic Fibonacci retracement untuk discretionary trader. Indikator ini tidak memberikan sinyal BUY/SELL dan tidak mengatur posisi trading. Tujuannya adalah menyusun higher-timeframe bias, valid chart-timeframe BOS, dan retracement Fibonacci dalam satu workflow yang bersih dan mudah dibaca.
CARA KERJA
1. Adaptive bias timeframe
Secara default indikator memilih bias timeframe yang lebih tinggi berdasarkan timeframe chart aktif. Contohnya M5 -> H1 dan M15 -> H4. Mode Custom tetap tersedia jika pengguna ingin menggunakan hubungan timeframe yang berbeda.
2. Confirmed higher-timeframe bias
Bias membaca structure dari higher timeframe yang sudah confirmed. Mode Structure + EMA dapat digunakan untuk meminta alignment tambahan dari EMA. Data higher timeframe berasal dari candle yang sudah selesai agar perilaku historical dan realtime lebih konsisten.
3. Valid chart-timeframe BOS
Indikator hanya menampilkan BOS yang memenuhi aturan structure. BOS harus terjadi melalui confirmed close pada confirmed swing yang belum pernah dihitung sebagai broken, searah dengan higher-timeframe bias, serta memiliki opposite structural swing yang valid setelah swing yang di-break untuk menjadi origin impulse.
4. BOS-origin impulse tracking
Setelah valid BOS, indikator tetap mengikuti extreme impulse selama impulse masih berkembang. Endpoint Fibonacci belum langsung dikunci. Extreme baru dikunci setelah terjadi confirmed retracement sesuai threshold yang dipilih.
5. Automatic Fibonacci lock
Setelah retracement threshold terkonfirmasi, Fibonacci dikunci dan empat retracement level ditampilkan. Default: 0.618, 0.705, 0.790, dan 0.886. Chart hanya menampilkan angka ratio Fibonacci tanpa harga.
6. Fibonacci history
Fibonacci yang telah selesai atau digantikan dapat disimpan sebagai historical reference. Jumlah history dapat diatur oleh pengguna dan tampilannya dibuat lebih redup daripada Fibonacci aktif.
7. Compact dashboard
Dashboard menampilkan mapping chart timeframe ke bias timeframe, confirmed HTF bias, current structure, status Fibonacci, dan jumlah history yang sedang disimpan.
PENGGUNAAN
- Pasang indikator pada timeframe yang ingin digunakan untuk membaca structure.
- Gunakan Auto untuk mapping timeframe default, atau Custom jika menggunakan framework multi-timeframe sendiri.
- BOS bullish/bearish hanya muncul jika seluruh aturan validasinya terpenuhi.
- Setelah impulse pasca-BOS mengalami retracement sesuai threshold, Fibonacci dikunci dan level retracement ditampilkan.
- Gunakan Fibonacci sebagai area location/context dalam trading plan Anda sendiri. Indikator sengaja tidak menentukan entry, stop loss, take profit, atau ekspektasi hasil trading.
ORIGINALITAS DAN ALASAN SOURCE DILINDUNGI
BOS, market structure, dan Fibonacci retracement merupakan konsep yang sudah umum dan tidak diklaim sebagai penemuan baru. Nilai original script ini terletak pada workflow dan implementasinya: adaptive HTF bias, valid BOS filtering, pemilihan structural origin setelah break, dynamic impulse tracking, confirmed retracement lock, bounded Fibonacci history, serta visual state yang dibangun menjadi satu framework. Source dilindungi untuk menjaga implementasi tersebut sementara indikator tetap dapat digunakan gratis oleh komunitas.
KETERBATASAN
- Confirmed pivot membutuhkan sejumlah candle di sisi kanan sehingga swing diketahui dengan delay yang disengaja.
- Bias HTF menggunakan candle HTF yang sudah selesai sehingga lebih lambat dibandingkan metode yang membaca unfinished HTF candle.
- Auto timeframe mapping adalah default praktis dan bukan aturan universal.
- Sensitivitas BOS tergantung pada pivot settings yang digunakan.
- Fibonacci hanya menunjukkan lokasi retracement dan tidak menjamin reversal.
- Indikator tidak menghitung entry, SL, TP, win rate, Profit Factor, atau profitabilitas.
- Valid BOS yang lebih baru dapat menggantikan active structure jika opsi tersebut diaktifkan.
- Hasil visual dan perilaku structure dapat berbeda menurut instrument, timeframe, volatility regime, session, dan data feed.
Gunakan indikator sebagai analytical framework dan lakukan validasi pada instrument serta timeframe yang sesuai dengan proses trading Anda sebelum menggunakannya dalam keputusan live.
Gösterge

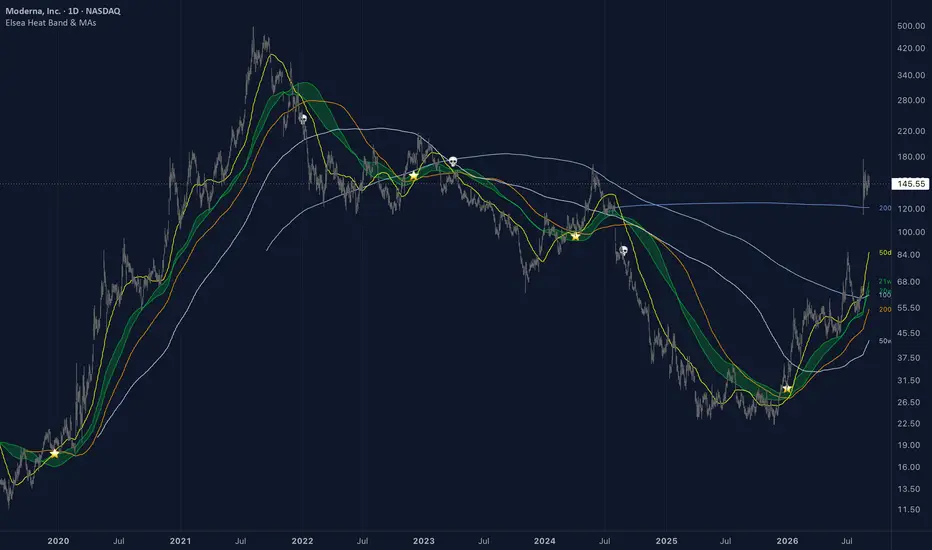
Elsea Heat Band & MAsElsea Heat Band & MAs is a moving-average utility: it draws the medium-term band (also known as the Bull Market Support Band / Bear Market Resistance Band, credit: Benjamin Cowen) alongside a set of conventional daily and weekly moving averages, on a single overlay with independent toggles for each group.
There is nothing novel in the calculations here. Every line is a standard SMA or EMA at a conventional length, and the cross detection is the standard 50/200 golden and death cross. The script exists to put a specific combination on one chart with consistent colouring, per-group toggles and end-of-series labels, rather than to introduce a new method. It is open-source for that reason.
WHAT IT DRAWS
Heat Band — a 140-day SMA and a 147-day EMA (roughly twenty and twenty-one weeks of trading days) with a shaded fill between them. Using both an SMA and an EMA at slightly offset lengths gives a band rather than a line, blending flat-window and recency weighting.
Daily MAs — 50-day and 200-day SMAs, with star and skull markers where the 50 crosses the 200 in either direction.
Weekly MAs — 50, 100, 200 and 300-week SMAs, computed as 350, 700, 1400 and 2100 daily bars, coloured on a single blue ramp so the ordering is readable at a glance.
Labels — at the right edge of the series, each visible average is labelled with its length.
HOW TO USE IT
Each of the three groups toggles independently, so the script can serve as a Heat Band overlay alone, a conventional MA set alone, or all of it together.
The band is medium-term structure: price above it has been above its twenty-week baseline, price below it has not. The weekly averages are long-horizon reference levels, most useful on instruments with many years of history. The 50/200 cross is included because it is widely watched, not because it is predictive — it is a lagging construction by definition, and the markers are there to locate the event on the chart rather than to endorse it.
LIMITATIONS
All averages are computed from daily closes regardless of chart timeframe, so they are stepped on intraday charts and update once per day.
Weekly averages are approximated as multiples of seven daily bars, not calendar weeks. On instruments that do not trade seven days a week the effective calendar period is longer than the label suggests. This is intended for consistency with the daily series, but the labels are approximate.
The longest average needs roughly 2100 daily bars before it produces a value. On instruments with less history it will not plot.
Moving averages lag by construction, and the longer ones lag substantially. Nothing here identifies a turn as it happens.
The 50/200 cross is a widely known lagging signal with no edge implied by its inclusion.
This is an analysis tool. It does not predict direction and produces no buy or sell recommendations.
Gösterge

Adaptive Market Regime MapAdaptive Market Regime Map is a chart-overlay context tool that separates directional conditions from volatility conditions. It is designed to help traders describe the current market environment without presenting buy or sell signals.
WHAT IT SHOWS
The indicator organizes market context into two layers:
• Directional regime: Bullish, Bearish, or Neutral
• Volatility state: Compressed, Normal, or Expanding
A layered corridor is plotted around an adaptive equilibrium line. Its width responds to ATR, while its color and intensity reflect the current directional regime and measured trend strength.
In bullish conditions, the lower half of the corridor is emphasized as support context. In bearish conditions, the upper half is emphasized as resistance context. These areas are descriptive context zones, not fixed support or resistance levels and not trade-entry signals.
HOW IT WORKS
The directional engine combines:
• the distance between a fast EMA and the equilibrium EMA, normalized by ATR;
• the slope of the equilibrium EMA, also normalized by ATR;
• path efficiency, calculated from net movement relative to total movement over the selected window.
The resulting directional score is bounded and compared with the Trend Threshold to classify the market as Bullish, Bearish, or Neutral.
The volatility engine compares current ATR with a moving baseline of ATR:
• below the Compression Ratio: Compressed
• above the Expansion Ratio: Expanding
• between both thresholds: Normal
The dashboard displays the current regime, normalized strength, volatility state, and the number of bars spent in the current directional regime.
HOW TO USE IT
Use the map as a context filter alongside your own analysis:
• Bullish indicates persistent positive directional structure.
• Bearish indicates persistent negative directional structure.
• Neutral indicates that directional strength is below the selected threshold.
• Compressed indicates volatility below its recent baseline.
• Expanding indicates volatility above its recent baseline.
The corridor can also provide visual context around the equilibrium line. Price moving outside the corridor does not, by itself, constitute a breakout or reversal signal.
INPUTS
Regime Engine
• Fast Length: Period of the faster EMA used in directional separation.
• Equilibrium Length: Period of the central EMA used for the corridor.
• Slope Lookback: Bars used to measure the equilibrium slope.
• Efficiency Length: Window used to compare net movement with total path movement.
• ATR Length: ATR period used for normalization and corridor width.
• Volatility Baseline: Window used for the rolling ATR baseline.
• Spread Weight and Slope Weight: Relative contribution of both directional components.
Classification
• Trend Threshold: Minimum absolute directional score required for a bullish or bearish regime.
• Compression Ratio: ATR-to-baseline ratio below which volatility is classified as compressed.
• Expansion Ratio: ATR-to-baseline ratio above which volatility is classified as expanding.
Regime Corridor
• Inner Zone ATR and Outer Zone ATR: Width of the two corridor layers.
• Show Outer Context Zone: Displays or hides the lighter outer layer.
• Show Equilibrium Line: Displays or hides the central line.
• Color Transition Bars: Controls how quickly a new regime color reaches full intensity. This affects presentation only.
• Tint Candles By Regime and Tint Chart Background: Optional visual context, disabled by default.
State Changes
• Label Confirmation Bars: Number of persistent state bars required before a label is displayed.
• Same-Label Minimum Distance: Minimum distance between labels of the same type.
• Neutral labels are optional and disabled by default.
ALERTS
The script provides five alert conditions:
• Market Regime Changed
• Bullish Regime Started
• Bearish Regime Started
• Compression Started
• Expansion Started
Alerts are confirmed on bar close by default. Label confirmation is separate from alert timing, so the optional label delay does not delay the corresponding regime alert.
REALTIME AND REPAINTING BEHAVIOR
The script does not use higher-timeframe requests, future data, offsets into the future, or lookahead logic. Historical classifications are calculated from information available on each bar.
On an open realtime bar, price, ATR, the corridor, and the displayed regime can change as new ticks arrive. With Confirm Alerts On Bar Close enabled, alerts trigger only after the bar is confirmed. This is the recommended setting for stable alert behavior.
LIMITATIONS
• This is an indicator, not a strategy or automated trading system.
• It does not predict future price movement.
• Bullish and bearish states are contextual classifications, not trade recommendations.
• The corridor provides volatility-scaled context and does not define fixed support or resistance levels.
• Results depend on symbol, timeframe, data quality, and selected parameters.
• Very short history can produce a warmup state until all calculations are available.
• Non-standard chart types use synthetic chart prices and may behave differently from standard OHLC charts.
ORIGINALITY
This script is an original implementation. Its distinctive contribution is the combination of an ATR-normalized directional engine, path-efficiency weighting, separate volatility classification, asymmetric regime-context zones, and a compact state dashboard in one causal chart overlay. Gösterge

ATR + True RTH Day RangeRTH Range & Daily ATR Monitor
Track the regular trading session’s price range and compare it with the daily Average True Range (ATR), using a compact panel on your chart.
Panel Values
• ATR(D): Daily ATR with a configurable lookback, set to 14 periods by default.
• Range RTH: The difference between the highest and lowest prices recorded during the regular session.
• Used: The RTH range expressed as a percentage of daily ATR.
Used = RTH Range ÷ Daily ATR × 100
For example, a session range of 3.87 and a daily ATR of 6.22 produces approximately 62.23%. The calculation uses unrounded values.
Regular Session Only
The session range uses standard one-minute candles from the regular-session data feed, filtered to 9:30 a.m.–4:00 p.m., Monday through Friday, in America/New_York time. Daylight saving time is handled automatically.
Premarket and after-hours prices are excluded from the range calculation, whether extended hours are visible on the chart or hidden.
The daily ATR also uses an explicitly selected regular-session feed.
Session Tracking
At the first available RTH candle of each new session, the indicator saves the preceding session’s high and low, then resets the current range.
During RTH, the range expands as new highs or lows form. Outside RTH, the panel retains the latest available regular-session values until the next session begins.
Panel Colors
The background compares the latest RTH price with the preceding RTH session’s range:
• Green: Above the previous session’s high.
• Red: Below the previous session’s low.
• Gray: Inside the previous session’s range, equal to either boundary, or without sufficient previous-session data.
Extended-hours price movements do not change this directional comparison.
Display Options
• Always: Displays the latest available RTH information, including after the session ends.
• Only Today: Displays the panel only when its RTH data belongs to the current New York calendar date. Before today’s RTH session begins, the panel remains hidden.
Understanding the ATR Percentage
The percentage compares the session’s high-to-low range with daily ATR. It does not measure the total distance traveled by price or predict how much movement remains.
Values above 100% are possible when the session range exceeds the ATR.
ATR uses True Range, which accounts for gaps relative to the previous daily close. Range RTH measures only the session’s high minus its low. These are related but different measurements.
Timeframes and Updates
Designed for intraday charts, the indicator calculates the session range from one-minute data rather than the visible chart candles. Update timing depends on the chart timeframe and available data.
The daily ATR includes the developing daily candle and can change during the regular session. It is not a fixed previous-day ATR reference.
Purpose
A compact tool for monitoring regular-session range expansion, daily volatility, and price position relative to the previous RTH session. It does not generate trade entries, execute orders, or provide backtest results. Gösterge

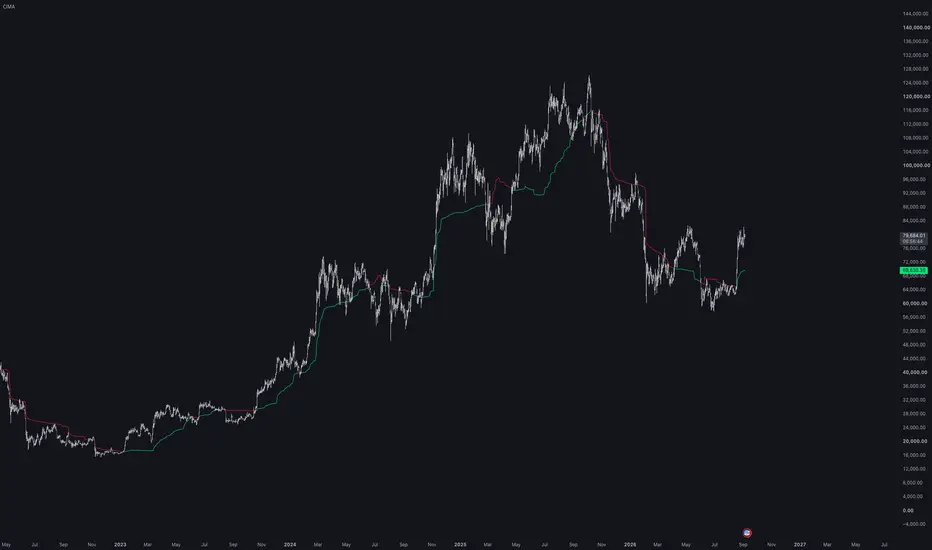
Composite Institutional Moving Average (CIMA)Composite Institutional Moving Average (CIMA)
Overview
The Composite Institutional Moving Average (CIMA) is a high-conviction cost-basis anchor designed to replace primitive volume-weighted indicators. Standard VWMAs treat every volume tick identically regardless of intent. CIMA evaluates the quality and composition of institutional order flow behind each bar.
By anchoring price action to a macro 126-period lookback, CIMA constructs a dynamic baseline weighted by intrabar cumulative volume delta (CVD) and stealth limit-order absorption.
Core Formula & Architecture
Rather than relying on raw volume alone, CIMA calculates a dynamic Composite Weight for every single candle using three distinct market mechanics:
$$\text{Composite Weight} = \vert{}\text{CVD Factor}\vert{} \times \text{Absorption Weight} \times \text{Volume}$$
* Order Flow Delta Proxy (cvdFactor): Measures intrabar buying versus selling pressure based on close position relative to high/low wicks. Directional imbalances pull the baseline toward true aggressive market orders.
* Stealth Absorption Efficiency (absorptionWeight): Measures total volume relative to candle range ($\text{volume} / \text{spread}$). Heavy volume printed inside narrow candle ranges highlights passive limit-order absorption (smart money accumulating or distributing without letting price move).
* 126-Period Macro Baseline Anchor: Applies the Composite Weight across a 126-period lookback using double-weighted VWMA logic ($\text{close} \times \text{compositeWeight}$). The 126-period setting represents exactly two quarters (6 months / semi-annual) of trading data on daily charts—the core timeframe used by institutional fund managers and execution algorithms to track semi-annual cost basis. On intraday charts, 126 bars provides a deep structural sample size that filters out high-frequency noise, ensuring the line only shifts when major institutional volume shelves are formed.
How to Read the Raw Baseline
Because CIMA remains un-smoothed, the indicator creates sharp vertical steps and flat horizontal shelves:
* Vertical Steps: Highlight points where sudden institutional volume injections or aggressive order sweeps occurred.
* Flat Horizontal Shelves: Function as dynamic Institutional Support & Resistance Floors. Expect smart money to defend these cost-basis shelves on the first retest.
* Trend Bias:
* Price > CIMA (Bright Green): Institutional buyers control the macro cost basis. Look for long continuation setups off CIMA shelf retests.
* Price < CIMA (Bright Red): Institutional sellers control the macro cost basis. Look for short continuation setups off CIMA shelf retests.
Key Features & Toggle Options
* Enable Volatility Bands ($\pm\sigma$): Displays optional standard deviation channels derived from the CIMA baseline to identify objective overbought/oversold value area extremes (Disabled by default for a clean chart).
* Multi-Timeframe (MTF) Engine: Toggle higher timeframe execution (e.g., Daily CIMA overlaid on a 15m chart) without code lag or repainting errors.
Default Inputs
* Institutional Lookback Length: 126 (Optimized for semi-annual structural anchoring).
* Enable Order Flow Delta Factor: True
* Enable Stealth Absorption Factor: True
* Best Applied To: Equities, Crypto, Futures, and Forex across any timeframe.
Disclaimer
This indicator is designed for educational and informational purposes only and does not constitute financial or investment advice. Past performance is no guarantee of future results. Financial market trading involves substantial risk of loss, and traders should perform their own independent technical analysis and manage their risk strictly before executing trades. Gösterge

Oleg AlgoWelcome to Oleg Algo, a heavy-duty, multi-layered statistical mean-reversion and trend-following strategy designed for traders who like to scale into volatility like a crazy. This script allows you to harvest profits from market extremes using dynamic gap thresholds, aggressive scale-in martingale sizing, and built-in risk boundaries.
Key Features
Dual Strategy Modes: Switch effortlessly between Reversal Mode (catching extreme overextended moves by fading the gap) and Trending Mode (riding the momentum wave).
Flexible Band Calculations: Measure market boundaries using either ATR (Average True Range) for pure volatility-based distance or Bollinger Bands (Standard Deviations) for statistical dispersion.
Scale-In Martingale System: Automatically scale into positions as the market moves against you. Choose between an exponential Multiplier or a linear Quantity Step to average down like a true strategist.
Win/Loss Outcome Sizing: Optionally adjust your base position size up or down following a win or loss to dynamically manage your exposure streak.
Time Windows: Built-in EST market-session filters that strictly lock your trading window and automatically flatten all open positions before the closing bell rings.
Max Dollar Loss Circuit Breaker: An absolute safety switch that liquidates everything if unrealized open drawdowns cross your predefined dollar risk threshold.
Input Guide
Strategy Execution Mode: Choose whether we hunt the reversal when price crashes hard away from the line, or follow the big bear/bull wave.
Trade Direction: What kind of hunt we do—go both ways like a smart trader, or stick strictly to long-only or short-only.
Moving Average Type & Length: Pick your line flavor (SMA, EMA, HMA).
Band Calculation & Initial Gap: Define how far price must run away from the baseline before enter trade.
Scale-In Step & Martingale Settings: Control how deep price must drop before adding more size, and how aggressively each stacked layer grows.
Take Profit & Stop Loss Multipliers: Set your distance for collecting big feasts when the average entry price bounces back, alongside the emergency parachute stop loss.
Prop Mode & Start/End Times: Lock your trading strictly inside capitalist working hours so you never violate risk rules or hold overnight risk. Strateji

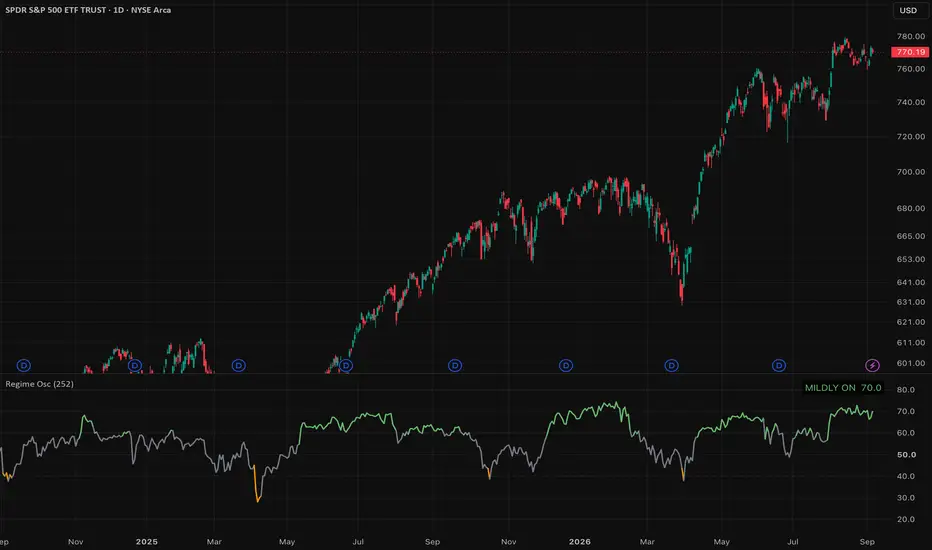
Cross-Asset Regime OscillatorA daily 0–100 gauge of US market risk appetite, built from five cross-asset
signals rather than price alone. It answers one question: is the broader
tape leaning risk-on or risk-off right now?
METHOD
Each signal is z-scored against its own trailing distribution on daily bars
("Lookback (bars)" input, default 252 ≈ one trading year, range 60–1000),
clamped to ±3 so no single blown-out signal dominates, averaged with equal
weight, then mapped linearly onto 0–100. The lookback always counts daily
bars, whatever the chart timeframe.
SIGNALS (all free-tier data, no premium feeds)
1. Credit — HYG/IEF: high yield vs. Treasuries. Higher = risk-on.
2. Equity volatility — VIX, inverted. Lower vol = risk-on.
3. Cyclical vs. defensive — XLI/XLU: industrials vs. utilities. Higher = risk-on.
4. Yield curve — US10Y minus US03MY (10-year minus 3-month). Steeper = risk-on.
5. US dollar — DXY, inverted. Weaker dollar = risk-on.
READING IT
0–20 RISK-OFF · 20–40 MILDLY OFF · 40–60 NEUTRAL · 60–80 MILDLY ON · 80–100 RISK-ON
The line is colored by band, with dotted guides at 20/40/60/80, and the
corner readout shows the current band and score. Enable "Show signal
breakdown" to see each signal's clamped z-score and the composite in the
corner table — useful for seeing WHICH channel is driving a move (e.g. credit
still positive while vol and cyclicals roll over). "Color chart bars by
regime" paints the price bars with the band color.
MISSING DATA
A signal that has not loaded, has fewer daily bars than the lookback, or is
flat over the lookback is skipped, and the composite averages the rest. The
readout warns when fewer than 3 of the 5 signals have data.
NON-REPAINTING
Every value is the clamped z-score of the last CONFIRMED daily bar, computed
inside the daily security context. The one-bar offset makes the request
confirmed-only, so the forming daily bar never leaks in and values never
change on refresh. Each day's value is aligned to the start of the daily
period, so the reading is identical on every supported chart timeframe.
During a live session the reading reflects the prior session's close.
SUPPORTED TIMEFRAMES
Daily and intraday charts. On any chart timeframe above daily (weekly,
monthly, multi-day) the script stops with a runtime error by design:
"Cross-Asset Regime Oscillator is a daily indicator. Use a 1D or lower
chart timeframe." It is a daily oscillator, and above-daily requests cannot
be pinned reliably to the same confirmed session.
LIMITATIONS
This is a deliberately simple, transparent construction: equal weights, one
lookback, five signals. It describes current conditions; it does not
forecast. Short lookbacks react fast and can whipsaw. Not investment advice. Gösterge

ATK / DEF Multi-Session Volatility DynamicsATK / DEF — Multi-Session Volatility Dynamics is a multi-session market analysis framework built around three market sessions:
**Asia, Europe, and America**
The framework separates market activity by session and combines session identification, price structure, volume-based conditions, liquidity classification, volatility state, and visual reference areas within a unified chart interface.
## Core Features
* Asia Session
* Europe Session
* America Session
* Independent session configuration
* Configurable session start and end times
* Multiple timezone options
* Session-specific visual identification
* Volume-based market condition classification
* Liquidity level classification
* Volatility state classification
* Candle body-to-range measurement
* Session-based Order Block reference areas
* Session-specific Order Block labels
* Adjustable Swing detection parameters
* Configurable display range
* Progress and status table
* Chart status-line measurements
## Multi-Session Framework
The indicator separates three configurable market sessions:
**Asia → Europe → America**
Each session maintains its own identity on the chart, allowing the displayed structures and calculated conditions to remain associated with their corresponding session.
Session settings can be independently enabled or disabled, with configurable opening and closing times.
## Session-Based Market Analysis
Market conditions are evaluated within the configured session environment using a combination of internal calculations based on:
* Volume
* Price position
* Candle body size
* Total candle range
* ATR
* Historical volume averages
* Historical ATR averages
The framework displays calculated states directly on the chart without converting them into trading signals.
## Liquidity Classification
The indicator includes a volume-based liquidity classification using relative volume conditions.
The displayed states are:
* **High Liquidity**
* **Medium Liquidity**
* **Low Liquidity**
These classifications are generated from the indicator's internal volume-ratio calculation and are provided as analytical reference values.
They do not represent a definitive measurement of market liquidity or capital flow.
## Volatility State
Volatility conditions are classified through an ATR-based comparison with its historical average.
The displayed states are:
* **Expanding**
* **Ranging**
* **Contracting**
These states represent the calculated volatility condition of the current data relative to the configured historical reference.
## Market Condition Classification
The framework includes internal classifications such as:
* **Accumulation**
* **Distribution**
* **Shakeout**
* **Normal**
These labels are generated from the indicator's defined combinations of relative volume, candle position, and candle-body conditions.
They are calculation-based analytical classifications and should not be interpreted as definitive identification of institutional activity or market intent.
## Session-Based Order Block Reference
The indicator provides visual reference areas associated with the currently identified market session.
Session labels include:
* **ASIAN**
* **LONDON**
* **NEWYORK**
The session identity is displayed together with the corresponding reference area.
The component is provided strictly for analytical reference. Displayed areas are generated by the indicator's internal calculation framework and do not represent confirmed, absolute, or universally valid classifications.
## Visual Analysis
The chart interface combines session information and calculated market conditions into a visual structure.
## Parameters
Different instruments, chart timeframes, session definitions, timezones, and parameter settings may produce different calculated results. The framework is therefore designed with configurable parameters rather than a single fixed configuration.
## Analytical Purpose
ATK / DEF — Multi-Session Volatility Dynamics is designed **solely for market observation and analysis**.
The indicator does not provide guince, or tra recommendations.
All displayed classifications, session references, measurements, and visual structures are generated from the indicator's internal calculation logic and the user's current parameter settings.
The displayed information is intended for analytical reference only.
**Market analysis only.**
Gösterge

Compression Clock (Axiom Multi-TF Adaptive)**Compression Clock (Axiom Multi-TF Adaptive) — Volatility Regime & State Age**
---
### **Description**
#### **Overview**
The **Compression Clock** is a non-directional volatility regime indicator based on the **Axiom quantitative research framework**. Instead of attempting to forecast market direction, it isolates the temporal dimension (**WHEN**) by measuring the duration and depth of volatility compression across any resolution.
Markets do not transition from quiet to expansion instantaneously; they exhibit a survival-rate decay where prolonged low-volatility states exponentially elevate the baseline probability of large physical displacement. The Compression Clock standardizes this process by normalizing rolling volatility and volume percentiles against a physical-time benchmark.
---
#### **Mathematical & Architectural Core**
1. **Dual-Feature Quiet Filter**:
* Evaluates rolling True Range ($\text{ATR}_{24}$) and Traded Volume ($\text{SMA}_{24}$) scaled against an intraday 24-hour physical window:
$$\text{ATR}_{\text{rolling}} = \text{SMA}(\text{TR}, N_{\text{bars}}), \quad \text{Vol}_{\text{rolling}} = \text{SMA}(\text{Volume}, N_{\text{bars}})$$
* Computes the rolling percentile rank of both features across a rolling 180-day baseline distribution.
* A bar qualifies as **Quiet** if and only if both features sit simultaneously in the lower tercile:
$$\text{Quiet}_t = \mathbb{I}\left(\text{Rank}(\text{ATR}_t) \le 33.33\%\right) \land \mathbb{I}\left(\text{Rank}(\text{Vol}_t) \le 33.33\%\right)$$
2. **Physical-Time Normalization**:
* TradingView indicators often suffer from timescale distortion when hardcoding bar-based periods across multiple resolutions.
* This script dynamically translates resolution minutes ($M_{\text{tf}}$) into actual **physical hours**. Whether applied to a 5-minute, 30-minute, or 4-hour chart, the Y-axis consistently represents **elapsed physical hours of continuous compression**.
3. **Regime State Categorization**:
* **S0 (ACTIVE)**: Market is expanding or fluctuating outside the quiet threshold. Compression age resets to 0.
* **S1 (QUIET, < 24 Hours)**: Early-stage compression. Natural volatility dampening without statistical hazard elevation.
* **S2 (MATURE, 24 – 72 Hours)**: Statistically mature compression. Historical survival analysis indicates a significant elevation in large-displacement probability.
* **S3 (DEEP, > 72 Hours)**: Extreme volatility exhaustion. Persistent absence of dispersion indicating imminent volatility expansion.
---
#### **How to Use (Methodological Discipline)**
* **Decoupled Architecture**:
* The Clock dictates **WHEN** (volatility environment), not **WHAT** (direction) or **HOW** (execution).
* Never treat an S2/S3 state as a directional trade signal. A compression state is directionally agnostic—it warns of imminent displacement hazard, but the direction must be governed by external momentum or structural acceptance/rejection models.
* **Multi-Timeframe Scope**:
* Low-scale compression (e.g., 5m/15m entering S3) reflects localized intraday order book exhaustion. It does **not** override a higher-timeframe S0 state. For macro regime filtering, monitor higher physical resolutions (such as 4H).
* **Buffer Safety**:
* Includes a built-in 4,900-bar memory clamp to prevent buffer overflow exceptions on ultra-low timeframes while maintaining valid causal percentile rankings.
---
#### **Inputs**
* **Rolling Feature Duration (Hours)**: Physical length of the short-term smoothing window (Default: 24h).
* **Lookback Days (Days)**: Historical distribution window for empirical percentile rankings (Default: 180 days).
* **Quantile Rank Threshold (%)**: Cutoff for the quiet regime (Default: 33.333% — bottom tercile). Gösterge

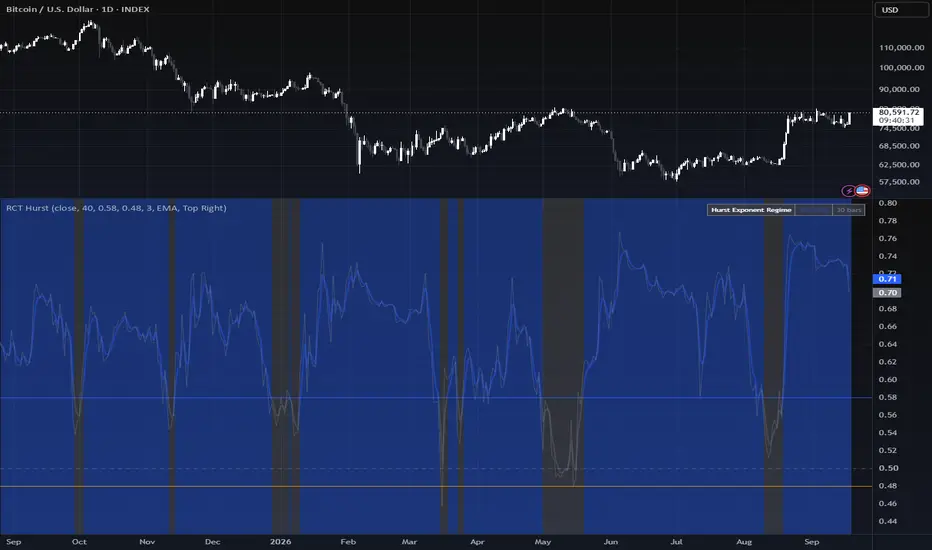
Hurst Exponent Regime [RC Tools]RC Tools — Hurst Exponent Regime
────────────────────────────────────────────────────────────────────
█ OVERVIEW
Most regime tools ask "is price trending right now." This one asks a more fundamental question: does this market's statistical character currently reward trend-following or mean-reversion? It applies the Hurst Exponent — a statistic originally developed to study Nile river flood records — via rescaled-range analysis, to classify the market into one of three long-memory regimes.
█ WHAT IT DOES
Estimates the Hurst Exponent (H) over a rolling window and classifies each confirmed bar as Trending (persistent), Mean-Reverting (anti-persistent), or Random Walk (no memory). Colours the chart background accordingly, plots both the smoothed and raw H line in a dedicated pane against static threshold lines and the 0.5 "true random walk" reference, and shows a table with the current state, how long price has been in it, and historical base rates (average forward return and win rate) for each state.
█ THE THEORY BEHIND IT
H.E. Hurst developed this statistic in the 1950s while studying how to size reservoirs for the Nile, where flood years tended to cluster rather than arrive randomly — a property he needed to measure and design around. The same statistic applies to any time series: it measures whether large values tend to be followed by more large values of the same sign (persistence, H > 0.5), whether they tend to reverse (anti-persistence, H < 0.5), or whether the series has no memory at all (H = 0.5, a true random walk).
Applied to price, this is a genuinely different question from "is this asset trending." A trend-following indicator can flag a trend within a market whose underlying character is actually mean-reverting — in which case that trend is more likely to be a temporary deviation that reverses. Knowing which regime you're in tells you which family of tools (trend-following vs. mean-reversion) is statistically better suited to current conditions, independent of what any single trend or oscillator reading says right now.
█ HOW IT IS CALCULATED
1. Take log returns over the window.
2. Build the cumulative deviation-from-mean series within the window, in chronological order, and take its range (maximum minus minimum) — this is R.
3. Compute S, the window's standard deviation of returns.
4. Apply Hurst's classic empirical relation: R/S is approximately equal to (window length / 2) raised to the power H. Rearranging gives H = ln(R/S) / ln(window length / 2).
5. Optionally smooth H (the raw rescaled-range estimate is noisy bar-to-bar by construction).
6. Classify: H above the Trending threshold (default 0.55) → Trending. H below the Mean-Reverting threshold (default 0.45) → Mean-Reverting. Otherwise → Random Walk.
Classification occurs ONLY on confirmed bar close — the plotted H, the background colour and the table all update together, so nothing here can disagree mid-bar or flip back and forth as the current bar forms.
Note: this is a single-scale rescaled-range estimate using Hurst's classic empirical formula, not a full multi-scale regression across many window sizes. It is a practical, computationally efficient approximation, not a research-grade estimator — treat it as a useful compass, not a precise measurement.
█ SETTINGS & CONFIGURATION
• Source (default close)
• Window Length (default 100) — longer windows give a more stable estimate but react slower to a genuine regime change
• Trending / Mean-Reverting Thresholds (default 0.55 / 0.45) — the H values beyond which a regime is declared; the gap between them is the "Random Walk" zone
• Smoothing Length and Type (default 5-period EMA) — reduces the raw estimate's bar-to-bar noise
• Forward Return Window (default 20 bars) — the horizon used for the base-rate table
• Table visibility, position and colours are fully configurable; the main-chart background painting can be toggled off if you only want the statistics pane
█ HOW TO USE IT
Use it to decide which family of tools to trust right now, not as a standalone entry signal. Example: if you run a mean-reversion system, check whether it has historically performed better when this tool reads Mean-Reverting than when it reads Trending; a trend-following system should show the opposite pattern. Check the base-rate table's sample count before treating any single state as meaningfully predictive.
Works on any asset and timeframe with sufficient history for the Window Length. Best used on daily and above, where regime persistence is greatest and the R/S window has enough independent observations to be meaningful.
█ LIMITATIONS
• This is a SINGLE-SCALE rescaled-range estimate, not a full multi-scale regression across many window sizes — a practical approximation, not a research-grade estimator.
• H describes the market's statistical character over the window — it does NOT identify direction. A "Trending" reading means persistence is likely, not which way.
• The R/S statistic assumes no major structural breaks within the window; a sudden regime shift partway through the window can distort the estimate until it fully rolls off.
• Shorter windows react faster but produce noisier, less reliable H estimates; longer windows are more stable but slower to reflect a genuine regime change.
• Historical base-rate stats need a meaningful sample count (check N) before being trusted, especially for the less common states.
• This script does NOT repaint. All classification updates on confirmed bar close only.
█ DISCLAIMER
For educational and informational purposes only. Nothing here is financial advice. Past behaviour of any regime state does not indicate future results. Trade at your own risk.
Gösterge

VIX Term StructureVIX at 14 does not tell you whether volatility is cheap. The curve does.
A single VIX print is one number on one horizon. What actually tells you something is the shape across horizons: whether the market is asking more for protection next week than for protection in three months, or less. That shape is where the information is, and it is free public data that almost nobody puts on a chart.
This plots the four CBOE volatility indices as a curve you can read at a glance -- 9-day, 30-day, 3-month and 6-month -- and reduces it to the one ratio that matters, 30-day over 3-month.
Below 1, the curve is in contango. Near-dated volatility is cheaper than deferred, which is the normal state and roughly two thirds of all trading days. The lower the ratio, the steeper the curve, and the calmer the market thinks the next month will be relative to the next quarter.
Above 1, the curve is inverted, or in backwardation. Near-dated volatility is bid over deferred, which means the market is paying up for protection it needs soon rather than eventually. That is a stress reading and it does not persist for long.
The dashboard shows each tenor, both ratios, and a plain verdict: STEEP CONTANGO, CONTANGO, or BACKWARDATION. The 9-day over 30-day ratio sits alongside it as the very front of the curve, which moves first and moves hardest.
What the shape is actually telling an option seller. A rich premium reading and a steep contango curve are the same market saying two things that agree: insurance is expensive relative to what has happened, and the market does not expect that to change soon. A rich premium reading against an inverted curve is a different animal. The premium is rich because something is coming, and selling into it is selling insurance to somebody who knows they need it. The IV-minus-RV gap looks identical in both cases. The curve is what separates them.
There is a trap on the other side too, and it is the more common one. The urge to sell premium is strongest when the tape is calm, and a calm tape is exactly what a steep contango curve looks like from the inside. Steep contango means the front is cheap, and cheap is the least you will ever be paid to take the risk. The moment selling feels safest is the moment it pays least.
Pairing. This answers a question my other two volatility scripts do not. Vol Premium Gauge answers whether you are paid, by comparing implied against realized. Expected Move Bands answers which strike, by drawing the one-standard-deviation range. Term structure answers whether the premium is there for a good reason or a bad one. Paid, why, where -- three different questions, three different reads.
Scope. Equity indices only. There is no term structure for crypto volatility, because DVOL publishes a single tenor rather than a curve, so unlike the other two this script does not auto-detect crypto. On a crypto chart the dashboard will read NO CURVE, which is honest rather than broken.
Alerts fire on the flip in each direction: into backwardation, and back into contango.
The thresholds are inputs, defaulting to 0.90 for steep and 1.00 for the inversion. The symbols are inputs too, so if CBOE changes a ticker the script keeps working.
Gösterge

LDO-PVSRA-Vol [1.2]Volume bars coloured by PVSRA classification instead of plain up/down, so a
volume spike tells you its direction and its size at a glance.
── Reading it ──
Bright green / bright cyan — 200% "climax" volume. The big ones.
Mid green / blue — 150% "rising" volume. Above average, worth noting.
Faded — normal volume. Deliberately recessed so it sits
in the background and the vector bars pop.
Green is a bar that closed up, blue/cyan a bar that closed down. Brightness is
the size of the volume, hue is the direction. (Averages are taken from the ten
candles BEFORE the current one, which is the standard PVSRA calculation.)
── Changing the colours ──
All colour settings are in the INPUTS tab, not the Style tab. TradingView's
Style tab cannot recolour this plot and its picker there will appear to do
nothing — use Inputs.
There are three colour groups, each with an Up and a Down picker:
"200% volume — climax" the bright pair
"150% volume — rising" the mid pair
"Normal volume — faded" the background pair
Normal volume also has two extras:
Colour mode — "By direction" keeps the green/blue split. "Single colour"
paints every normal bar the same neutral shade, so the pane
reads as spike-vs-background rather than up-vs-down. Useful if
your candles already show you direction.
Fade % — how recessed normal volume looks. 0 is solid, 65 is the
default, higher pushes it further back.
Match these to whatever candle colouring you already run and the two panes will
agree by eye as well as by logic.
── Using Binance volume ──
"Use volume of the equivalent BINANCE PERP chart" is ON by default, and on
crypto symbols it pulls volume from the matching Binance perpetual rather than
whatever exchange your chart is on. That is where the volume actually trades,
so the classification is far more meaningful than volume from a thin venue.
The feed it settled on is printed in the small label at the bottom right of the
pane. If the perpetual does not exist it quietly falls back to your chart's own
volume — and that label will say so, so you always know what you are looking at.
Want a specific feed instead? Tick "Force override symbol" and type it in. On
non-crypto symbols the setting does nothing and your chart volume is used.
── Setting alerts ──
Two alerts are built in:
"Vector volume (150% or 200%)" — any above-average bar
"Climax volume (200%)" — the big ones only
To set one: click the alert clock (or right-click the chart, Add alert), set
Condition to LDO-PVSRA-Vol, then pick one of the two from the dropdown
underneath. Set the trigger to "Once per bar close" unless you want to be
pinged mid-candle by a spike that fades before the bar finishes.
Alerts fire off the same volume feed the bars are drawn from, so a Binance-perp
alert on a non-Binance chart works as you would expect.
── The rest of the settings ──
Thresholds — the 2.0x and 1.5x multipliers. The defaults are the standard
PVSRA values; raise them for fewer, more selective bars.
Volume MA — optional average line over the histogram, off by default.
Price pane — optionally colour your candles with the same classification.
Leave it off if you already run a PVSRA candle script.
Version label — the small bottom-right box. Turn it off if it is in your way.
── Credits ──
Derived from the open-source PVSRA volume work of infernix and peshocore,
under the Mozilla Public License 2.0. Independent derivative; not affiliated
with, and not named in reference to, Traders Reality or Pattern Watchers. Gösterge

Cost-to-Range Gauge [BSL]Before asking whether a method works on this chart, there is an earlier
question that almost nobody asks: can a result exist here at all?
Cost-to-Range Gauge answers it with one drawing. A twenty-cell bar
represents the typical range of the last 500 confirmed bars. The filled part
of it is your round-trip cost. If the fill takes up a quarter of the bar, the
typical bar is four round trips wide. If it fills the whole thing, the typical
bar cannot pay for a single trade.
Under the drawing sits the number that goes with it: how many bars in the
window could not have covered one round turn at all.
WHY THE COST IS DRAWN AND NOT DESCRIBED
"Your cost is 3 ticks and the typical range is 12.6 ticks" is a sentence you
have to do arithmetic on. A bar with a quarter of it filled is a picture you
have already understood.
The ratio is printed as well, and it goes range divided by cost: above 1, the
typical bar covers a round turn. At or below 1 the drawing fills completely
and turns red, and the panel adds that the cost exceeds the typical range,
because a full bar on its own could be read as the drawing running out of room
rather than as the answer.
A bar whose entire range is smaller than the cost could not have paid for a
trade taken inside it, whichever direction that trade went. That is what the
count underneath is counting.
BOTH INPUTS ARE IN TICKS, ON PURPOSE
Every instrument on TradingView has a tick size, so ticks convert to price
everywhere. Not every instrument has a currency value per point. That figure
is missing for whole classes of symbol.
If the commission were entered in currency, the entire gauge would go dark on
any symbol without one. Taking both inputs in ticks means the price-space
reading always works, and the currency line is the only thing ever withheld.
It is withheld rather than guessed, and the panel says so where it would
otherwise have appeared.
If you have a figure in currency, divide it by the currency value of one tick.
The commission field is the WHOLE ROUND TURN, not one side. Enter one side and
you have halved your own cost; the script cannot detect it and will faithfully
report a flattering number.
The cost is your declaration. Nothing here can verify it.
A total cost of zero is refused. A ratio against zero is not a large number,
it is not a number, and the panel asks for a cost instead of printing
infinity.
WHAT THE RATIO LOOKS LIKE ON A DAILY CHART
Large. A daily bar is worth many round trips on any liquid instrument, so the
drawing fills a sliver and the ratio runs into the hundreds or thousands. That
is the correct answer to the question, and it is the answer you want before
committing to a timeframe. The gauge earns its keep further down, on the
intraday charts where a bar and a round trip are comparable and the fill is no
longer a sliver.
WHAT IS IN THE WINDOW
Confirmed bars only. The bar still forming is left out and named as pending.
Every reading on this panel is complete the moment a bar closes: a bar's range
is finished at its close, and none of these numbers is waiting on an outcome.
That means all rows share one cutoff, the last confirmed bar, and the only
unfinished observation on the whole chart is the bar still open.
That is the simplest possible case of a rule this family applies everywhere,
and it is stated rather than skipped. A rule mentioned only when it bites is a
rule you cannot check.
Below 100 bars the whole gauge is faded and prints its own sample size, so a
reading taken over 40 bars never looks as solid as one taken over 500.
WHAT YOU ENTER
- Spread: 2.0 ticks
- Commission per round turn: 1.0 ticks
- Window: 500 confirmed bars
- Panel position: Bottom center
Six positions are available and the gauge begins at the bottom center. Both
left corners are spoken for by the platform, the legend above and the
TradingView logo below, and the right is where the price scale and most other
panels crowd.
A BRICK'S RANGE IS A SETTING, NOT A FACT
A Renko brick has the range you told it to have. Its size is a setting, not a
market fact, so a cost-to-range ratio measured against it is a ratio against
your own configuration. The same applies to Heikin Ashi, Kagi, Point & Figure
and Range charts.
On those chart types the drawing, the ratio and the published values all stop.
THREE VALUES FOR OTHER SCRIPTS
Three values are published for other indicators to pick up in their Source
setting: the range-to-cost ratio, the share of bars under cost, and the sample
size. All three are descriptions, not events. They change gradually and mean
something on every bar, rather than firing at a moment. Before the gauge has
an opinion they carry no value at all, which is not the same as a value of
zero.
The alert condition is listed beside them and is not a reading. The gauge
draws only its table, which cannot be selected, so these three are the whole
readable surface.
WHAT IT WILL NOT TELL YOU
No verdict. Not "tradeable", not "avoid", not a traffic light. The single
colour change on the panel, the drawing turning red, restates the number
beside it and adds no judgement to it, because the judgement depends on a
method this script has never seen.
It issues no events and stamps nothing at an event bar. It is a screen you run
before a method, and calling any of its readings a signal would be the exact
overreach it exists to argue against.
It contains no equity curve, no fill model and no slippage simulation. What
costs do to a result under realistic fills belongs to Execution-Aware Trend
; how a hit rate responds to a cost belongs to Signal Audit Lab .
This answers only whether a result can exist at all, and that is asked before
either of them.
This tool compares a cost you declare against typical bar size. It does not
predict price, guarantee performance or provide trading advice. Validate the
behaviour on your own symbols, timeframes and execution assumptions before
making decisions.
Open-source Pine Script® v6. Educational use only. Gösterge

RSI with Bollinger BandsRSI with Bollinger Bands combines the Relative Strength Index with Bollinger Bands calculated directly on the RSI itself.
This indicator is designed to help identify periods when RSI momentum becomes unusually stretched relative to its recent behavior, instead of relying only on the traditional fixed 30 and 70 RSI levels.
The RSI is displayed together with a Bollinger Band basis, upper band, and lower band. When RSI moves outside the bands, the indicator can display overbought or oversold breach signals and highlight the background.
Features
RSI oscillator
Standard RSI calculation
Default RSI Length: 14
Adjustable price source
Bollinger Bands on RSI
Bollinger Bands are calculated from the RSI value
Default BB Length: 20
Default Upper Multiplier: 2.0
Default Lower Multiplier: 2.0
Upper and lower multipliers can be adjusted independently
Overbought Breach Signals
Displays an OB signal when RSI moves above the upper Bollinger Band
Red background highlighting can appear during the condition
Oversold Breach Signals
Displays an OS signal when RSI moves below the lower Bollinger Band
Green background highlighting can appear during the condition
Traditional RSI Reference Levels
70 level
50 level
30 level
These levels can be shown or hidden
Customizable Display
Show or hide breach signals
Show or hide the Bollinger Band fill
Show or hide the 30 / 50 / 70 RSI levels
Settings
Length
Controls the RSI calculation period.
Default: 14
BB Length
Controls the lookback period used to calculate the Bollinger Band basis and standard deviation on RSI.
Default: 20
BB Up
Controls the standard-deviation multiplier for the upper Bollinger Band.
Default: 2.0
BB Down
Controls the standard-deviation multiplier for the lower Bollinger Band.
Default: 2.0
Price Source
Selects the price source used for the RSI calculation.
Default: Close
Show Breach Signals
Turns the OB and OS markers on or off.
Fill Bands
Turns the shaded area between the upper and lower Bollinger Bands on or off.
Show RSI 30/50/70 Levels
Turns the traditional RSI reference levels on or off.
How to Read the Indicator
When RSI moves above the upper Bollinger Band, it means RSI is unusually strong relative to its recent range. This can indicate elevated bullish momentum or a potentially overextended condition.
When RSI moves below the lower Bollinger Band, it means RSI is unusually weak relative to its recent range. This can indicate elevated bearish momentum or a potentially oversold condition.
The traditional 30 and 70 RSI levels remain available as additional reference points.
Alerts
The indicator includes built-in alert conditions for:
RSI Above Upper Band
RSI Below Lower Band
These alerts can be used to notify you when RSI breaches either Bollinger Band.
Important
A breach of the upper or lower band should not automatically be treated as a reversal signal. Strong trends can keep RSI extended for a significant period.
This indicator is best used together with price action, trend analysis, support and resistance, volume, or other forms of confirmation.
For educational and informational purposes only. This indicator does not constitute financial advice. Gösterge

AMD Po3 with Live Edge Stats WillyAlgoTrader Version OrGa## English
### AMD Po3 with Live Edge Stats — OrGa
The **OrGa version** is an enhanced New York Session-focused adaptation of the original AMD Po3 concept by WillyAlgoTrader.
The indicator is designed to identify **Power of Three / AMD market cycles**:
**Accumulation → Manipulation → Distribution**
Instead of treating every liquidity grab as a trade signal, the script first detects a statistically compressed accumulation range. A valid manipulation requires price to sweep one side of the range and subsequently **close back inside the range**. Only after this confirmation is the Distribution phase activated.
### Core Logic
**Accumulation**
* Detects compressed ranges using a Donchian-based volatility percentile model
* Default range boundaries are derived from confirmed pivot highs and lows
* Minimum range maturity prevents very young consolidations from generating premature sweep signals
**Manipulation**
* Detects liquidity sweeps above or below the accumulation range
* A sweep alone is not sufficient
* Price must return and close back inside the range within the configured number of bars
* If price fails to return, the event is classified as a breakout rather than a manipulation
**Distribution**
* A confirmed sweep below the range projects an upward distribution
* A confirmed sweep above the range projects a downward distribution
* The confirmed Distribution candle acts as the reference entry candle
### 🐊 Entry Signals
Confirmed Distribution entries are displayed directly on the chart:
**🐊 D ▲ = Long setup**
**🐊 D ▼ = Short setup**
The signal is generated only after candle close.
The entry emoji can be changed in the indicator settings.
### Reference Trade Model
For every confirmed setup the indicator calculates:
* Reference Entry
* Stop Loss
* Distribution Target
* Risk-to-Reward Ratio
* Risk distance in %
* Trade outcome statistics
The Stop is placed beyond the full manipulation extreme with an ATR-based safety buffer.
The Distribution target is calculated using a configurable Fibonacci extension.
**OrGa default: 1.618**
The Fib extension remains fully adjustable, allowing values such as:
* 1.272
* 1.5
* 1.618
* 2.0
The target should be interpreted as an expected distribution objective rather than a mandatory take-profit level.
### OrGa Liquidity & Confluence Model
The OrGa version adds contextual liquidity levels to help evaluate the quality of each AMD setup.
Available confluences include:
* Previous Day High / Previous Day Low
* London High / London Low
* Daily Open
* New York Session VWAP
Each confirmed Distribution setup receives a **Confluence Score**.
Example:
**🐊 D ▲ 3/4**
The score helps distinguish a random range sweep from a sweep occurring at meaningful market liquidity.
By default, the confluence score is informational and does **not** block signals.
An optional minimum score filter can be enabled if only higher-confluence setups should be traded.
### New York Session Optimisation
The OrGa configuration is primarily designed around the **15-minute chart** and the New York trading session.
Default workflow:
**4H Trend Bias → 15M AMD Setup → optional 5M Execution**
The default New York manipulation window is:
**09:30–12:00 America/New_York**
Using the native New York timezone automatically accounts for US daylight-saving changes. Traders using European chart time therefore do not need to manually adjust the session throughout the year.
### Higher-Timeframe Bias
The OrGa default HTF filter is:
**4H Close vs EMA 50**
* Above EMA50 → Long distributions preferred
* Below EMA50 → Short distributions preferred
The HTF data uses the previous confirmed higher-timeframe candle to avoid future-data leakage.
If a manipulation is rejected by the HTF bias, the range can optionally re-arm and wait for a sweep of the opposite side.
### Alerts
TradingView alerts are available for confirmed entries.
Separate conditions are provided for:
**🐊 OrGa LONG Entry**
**🐊 OrGa SHORT Entry**
Entry signals are confirmed on candle close.
The script also supports dynamic alerts for:
* Liquidity Sweep
* Confirmed Distribution
* Target reached
* Stop hit
* Timeout
Webhook JSON formatting is available for external integrations.
### Repainting
The core AMD signal logic is evaluated on **confirmed candles only**.
The higher-timeframe bias uses confirmed HTF data.
Pivot-based range boundaries require confirmation bars, which introduces normal pivot confirmation lag, but this is not future leakage.
The script is therefore designed for live use without intentional future-data leakage or classic signal repainting.
### Recommended Usage
The indicator should not be used as a blind Buy/Sell system.
Higher-quality setups typically combine:
* Valid accumulation
* Liquidity sweep
* Return inside the range
* 4H directional bias
* PDH / PDL or London liquidity
* Daily Open positioning
* Session VWAP alignment
* Strong New York timing
For refined execution, a confirmed 15M Distribution signal can be followed by a 5M market-structure confirmation such as CHOCH, FVG retest or liquidity reclaim.
The objective of the OrGa version is not to generate more signals, but to identify **cleaner and more contextual AMD setups with transparent risk, targets and live statistics**.
---
## Deutsch
### AMD Po3 with Live Edge Stats — OrGa
Die **OrGa-Version** ist eine auf die New-York-Session ausgerichtete Weiterentwicklung des ursprünglichen AMD-Po3-Konzepts von WillyAlgoTrader.
Der Indikator sucht nach **Power-of-Three- bzw. AMD-Marktzyklen**:
**Accumulation → Manipulation → Distribution**
Dabei wird nicht jeder Liquidity Grab automatisch als Trading-Signal interpretiert. Zuerst muss eine statistisch komprimierte Accumulation Range entstehen. Danach muss eine Range-Grenze gesweept werden und der Kurs anschliessend **wieder innerhalb der Range schliessen**. Erst dann wird die Distribution bestätigt.
### Kernlogik
**Accumulation**
* Erkennt enge Ranges über ein Donchian-basiertes Volatilitäts-Perzentil
* Die Range-Grenzen werden standardmässig aus bestätigten Pivot Highs und Pivot Lows gebildet
* Eine Mindest-Reifezeit verhindert Signale aus sehr jungen und instabilen Ranges
**Manipulation**
* Erkennt Liquidity Sweeps oberhalb oder unterhalb der Accumulation Range
* Ein Sweep alleine ist noch kein Signal
* Der Kurs muss innerhalb der definierten Anzahl Kerzen wieder in die Range zurückkehren und dort schliessen
* Erfolgt keine Rückkehr, wird die Bewegung als Breakout und nicht als Manipulation gewertet
**Distribution**
* Sweep unterhalb der Range → erwartete Distribution nach oben
* Sweep oberhalb der Range → erwartete Distribution nach unten
* Die bestätigte Distribution-Kerze bildet den Referenz-Entry
### 🐊 Entry-Signale
Bestätigte Distribution-Setups werden direkt im Chart dargestellt:
**🐊 D ▲ = Long-Setup**
**🐊 D ▼ = Short-Setup**
Das Signal entsteht erst nach dem Schluss der Kerze.
Das Entry-Emoji kann in den Einstellungen geändert werden.
### Referenz-Trade-Modell
Für jedes bestätigte Setup berechnet der Indikator:
* Referenz-Entry
* Stop Loss
* Distribution Target
* Risk-to-Reward
* Risikoabstand in %
* Ergebnisstatistiken
Der Stop liegt hinter dem vollständigen Manipulations-Extrem und erhält zusätzlich einen ATR-basierten Sicherheitsabstand.
Das Distribution Target basiert auf einer frei einstellbaren Fibonacci Extension.
**OrGa-Standard: 1.618**
Der Wert kann jederzeit beispielsweise auf folgende Werte geändert werden:
* 1.272
* 1.5
* 1.618
* 2.0
Das Ziel ist als erwartete Distribution-Reichweite zu verstehen und nicht zwingend als fixer Take Profit.
### OrGa Liquidity- und Confluence-Modell
Die OrGa-Version ergänzt zusätzliche Marktlevels, damit die Qualität eines AMD-Setups besser beurteilt werden kann.
Berücksichtigte Confluences:
* Previous Day High / Previous Day Low
* London High / London Low
* Daily Open
* New York Session VWAP
Jedes bestätigte Distribution-Setup erhält einen **Confluence Score**.
Beispiel:
**🐊 D ▲ 3/4**
Dadurch lässt sich unterscheiden, ob lediglich irgendeine Range-Grenze gesweept wurde oder ob der Sweep gleichzeitig an relevanter Marktliquidität stattgefunden hat.
Standardmässig dient der Score nur als Zusatzinformation und blockiert keine Signale.
Optional kann ein Mindestscore aktiviert werden, wenn nur Setups mit höherer Confluence gehandelt werden sollen.
### Optimierung für die New-York-Session
Die OrGa-Konfiguration ist primär für den **15-Minuten-Chart** und die New-York-Session ausgelegt.
Empfohlener Workflow:
**4H Trend Bias → 15M AMD Setup → optional 5M Execution**
Das standardmässige Manipulationsfenster für New York lautet:
**09:30–12:00 America/New_York**
Durch die Verwendung der echten New-York-Zeitzone werden Sommer- und Winterzeit automatisch berücksichtigt. Bei einem europäischen TradingView-Chart muss die Session deshalb nicht laufend manuell angepasst werden.
### Higher-Timeframe Bias
Der OrGa-Standard verwendet:
**4H Close gegenüber EMA50**
* Über EMA50 → Long-Distributionen bevorzugt
* Unter EMA50 → Short-Distributionen bevorzugt
Für den HTF-Bias wird ausschliesslich die vorherige bestätigte 4H-Kerze verwendet.
Wird eine Manipulation vom HTF-Bias abgelehnt, kann die bestehende Range optional re-armed werden und auf einen Sweep der gegenüberliegenden Seite warten.
### TradingView-Alarme
Für bestätigte Entries stehen separate TradingView-Alarmbedingungen zur Verfügung:
**🐊 OrGa LONG Entry**
**🐊 OrGa SHORT Entry**
Die Entry-Alarme werden erst nach bestätigtem Candle Close ausgelöst.
Zusätzlich unterstützt der Indikator dynamische Alarme für:
* Liquidity Sweep
* bestätigte Distribution
* Target erreicht
* Stop getroffen
* Timeout
Für externe Integrationen kann eine Webhook-JSON-Ausgabe aktiviert werden.
### Repainting
Die eigentliche AMD-Signallogik wird ausschliesslich auf **bestätigten Kerzen** ausgewertet.
Auch der Higher-Timeframe Bias basiert auf bestätigten HTF-Daten.
Die Pivot-Grenzen benötigen einige Kerzen zur Bestätigung. Dadurch entsteht ein normaler Pivot-Bestätigungs-Lag, jedoch kein Future Leak.
Der Indikator ist damit für den Live-Einsatz ausgelegt und verwendet keine absichtliche zukünftige Kursinformation.
### Empfohlene Anwendung
Der Indikator sollte nicht als blindes Buy-/Sell-System verwendet werden.
Hochwertige Setups kombinieren idealerweise:
* saubere Accumulation
* Liquidity Sweep
* Rückkehr innerhalb der Range
* passenden 4H Bias
* PDH / PDL oder London Liquidity
* passende Position gegenüber dem Daily Open
* Session-VWAP-Bestätigung
* gutes Timing innerhalb der New-York-Session
Für einen präziseren Entry kann nach einem bestätigten 15M-Distribution-Signal auf dem 5M-Chart beispielsweise auf CHOCH, FVG-Retest oder Liquidity Reclaim gewartet werden.
Das Ziel der OrGa-Version ist nicht, möglichst viele Signale zu erzeugen, sondern **sauberere und besser kontextualisierte AMD-Setups mit transparentem Risiko, Zielprojektion und Live-Statistik zu liefern**.
Gösterge