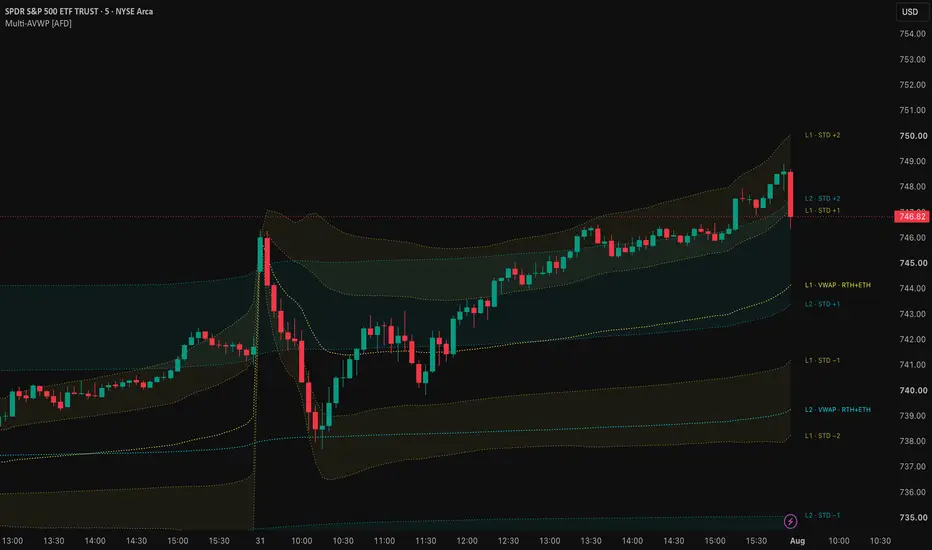
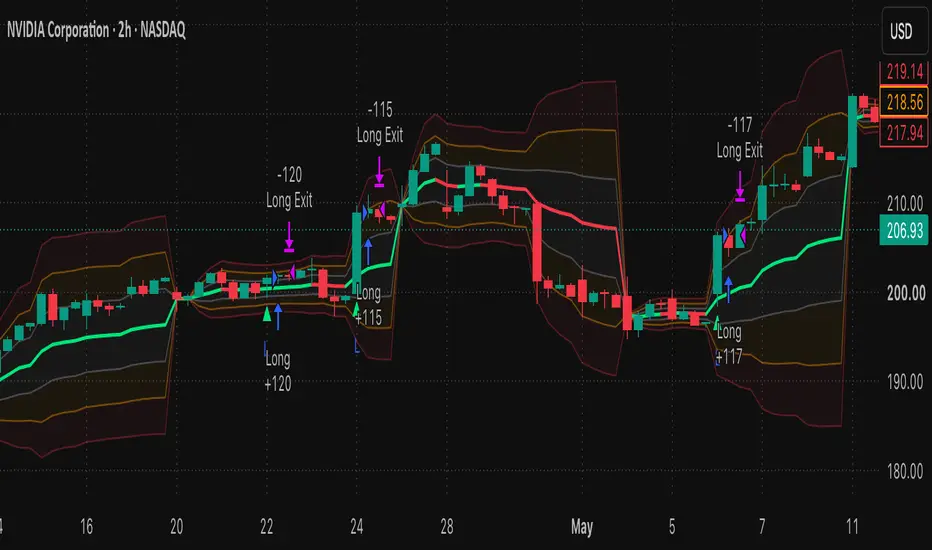
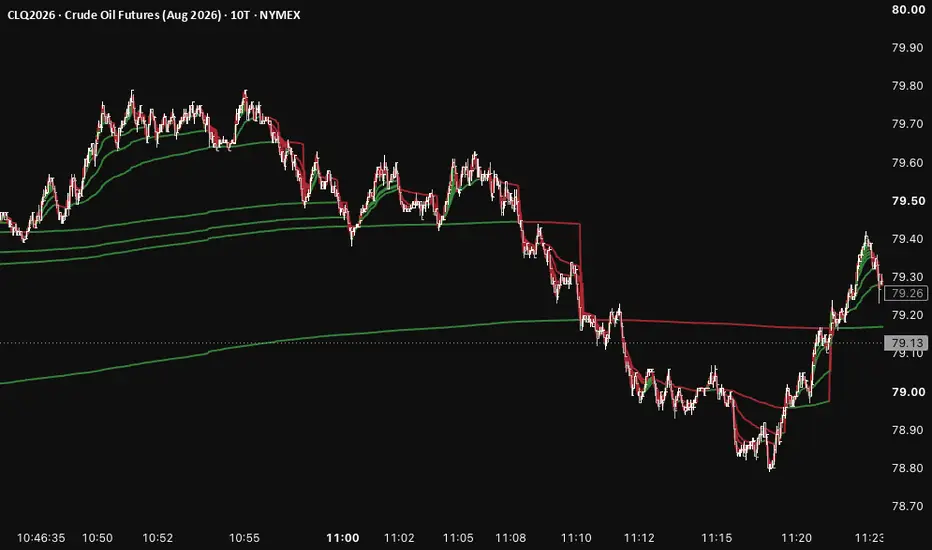
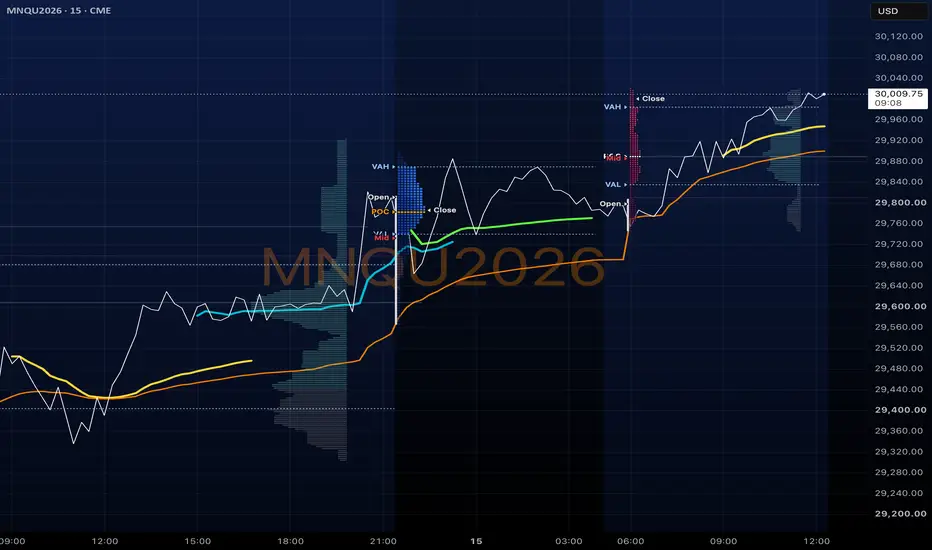
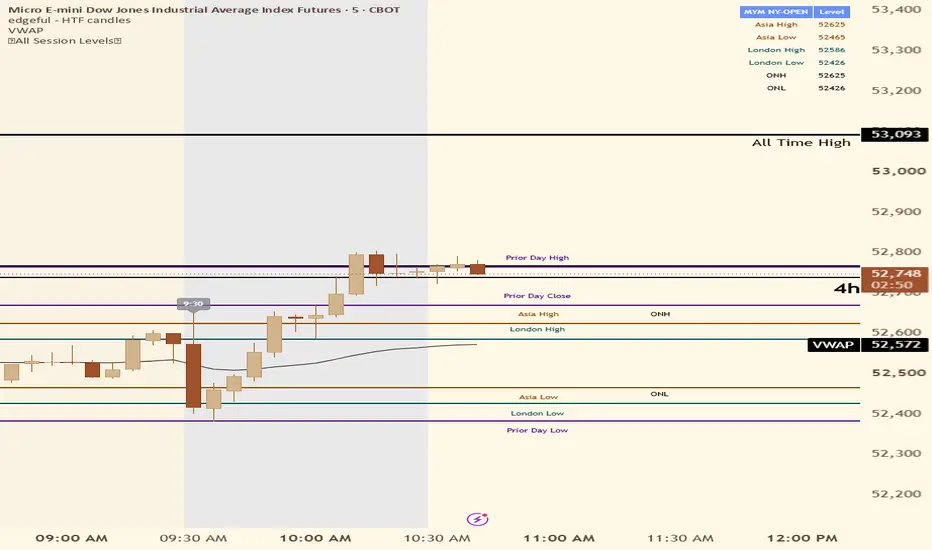
Multi-Period VWAP (7D / 30D / 90D)This indicator plots three rolling Volume-Weighted Average Price (VWAP) lines calculated over trailing 7-day, 30-day, and 90-day windows, giving you a read on where price sits relative to volume-weighted "fair value" across short, medium, and long-term horizons.
Unlike a standard anchored VWAP that resets to zero at a fixed point (session, week, month), these lines are true rolling averages — they continuously reflect the most recent N days of trading and shift smoothly bar to bar, making them useful for spotting mean-reversion zones, confluence with order blocks/key levels, and gauging trend strength when the shorter VWAP is stacked above or below the longer ones.
Features:
- Adjustable lookback lengths for all three periods (defaults: 7 / 30 / 90 days)
- Toggle each VWAP on/off independently
- Customizable colors per line
- Choice of price source (HLC3, Close, or OHLC4)
- Optional "confirmed bars only" mode to prevent the lines from repainting as the current day's volume accumulates
- Live value labels on the last bar for each active VWAP
Built with crypto's 24/7 markets in mind, so the daily boundaries used for the rolling calculation aren't disrupted by traditional session gaps.
Chỉ báo