Alibaba Group Holding — Bearish Selling Setup | Target $75Alibaba Group Holding — Bearish Selling Setup | Target $75 📉
Alibaba Group Holding is presenting a bearish technical scenario, with the current market structure leaving room for a deeper decline toward the $75 objective. The setup is focused on the broader downside path rather than treating the recent price fluctuations as an isolated move.
The stock has been showing considerable weakness across the broader trend. From a technical perspective, the important factor is the inability of price to sustain stronger upside progression, combined with recurring selling activity across the structure. This creates a framework in which further depreciation can remain in focus.
The current chart is being approached from a seller-dominated perspective. Instead of looking for an immediate recovery, the analysis tracks whether the existing bearish sequence can continue producing lower price levels. If the downside structure remains intact, the market can gradually work its way toward the projected $75 target.
📉 Technical Structure
The bearish thesis is built around the progression of price rather than a single resistance or support level.
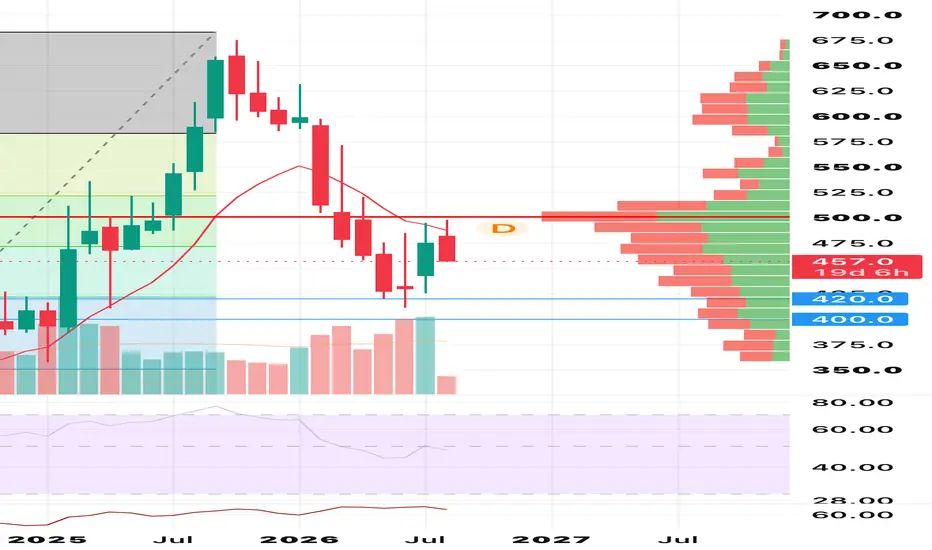
Recent market data shows BABA closed at $113.24 on September 18, 2026, after trading as high as $113.77 during the session. The stock remains substantially below its 52-week high of $192.67, highlighting the larger price contraction already experienced.
The analysis now focuses on whether sellers can extend that weakness into another major leg lower. A temporary rebound would not necessarily invalidate the bearish roadmap; what matters is whether price can regain and maintain a stronger bullish structure.
🔻 Downside Projection
Current structure → Selling pressure → Lower trading zones → Extended decline → $75
The $75 level represents the projected destination of this bearish scenario.
Reaching such a level would require a significant continuation of the existing decline, so the path may contain counter-moves and periods of consolidation. The core thesis remains that sellers can retain the upper hand and progressively push valuation toward the mapped objective.
🌐 Fundamental Context
Alibaba's business continues to have substantial operating activity, so this technical sell thesis should not be interpreted as a statement that the company itself is failing.
Alibaba reported fiscal-year 2026 revenue of RMB 1.024 trillion, up about 3% year over year, while net income declined 19% to RMB 102.1 billion. Its June-quarter results were released on August 20, 2026.
The company is also investing heavily in AI and cloud infrastructure, while recent reporting has highlighted increased capital spending and legal/regulatory concerns. These factors can contribute to volatility, but the $75 projection here remains primarily a technical market thesis.
🔍 Setup Overview
- Instrument: Alibaba Group Holding Limited
- Ticker: BABA
- Exchange: NYSE
- Direction: Sell
- Bias: Bearish
- Projected Target: $75
- Focus: Extended downside
- Technical basis: Market structure, momentum and price behaviour
- Scenario: Continued bearish progression
🎯 Final View
The broader chart continues to offer a downside framework, with the selling thesis centred on further deterioration in price structure.
The market has already travelled a long distance lower — but the mapped bearish scenario points toward another major leg, with $75 as the projected destination. 📉🎯  Short

 Long

 Long

 Long

 Long

 Short

Long 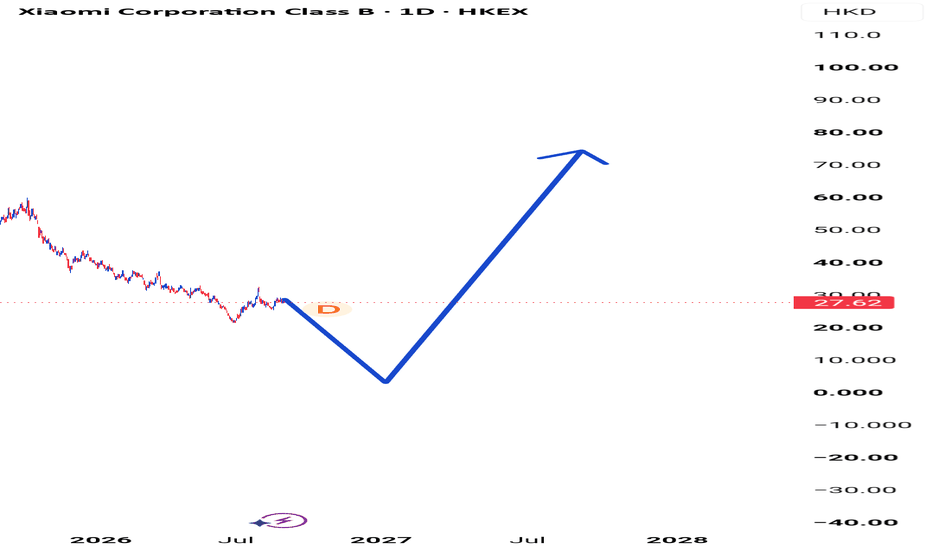
Short 
Is Lenovo the Next Big AI Hardware Winner?Lenovo Group delivered its strongest quarter in company history, with fiscal Q1 FY2027 revenue rising 43% year over year to US$26.94 billion. Adjusted net income surged 176% to US$1.08 billion, exceeding the US$1 billion quarterly milestone for the first time. The results significantly surpassed market expectations and highlight how rapidly Lenovo is benefiting from the global AI infrastructure cycle
🤖 AI Is Becoming Lenovo’s Biggest Growth Engine
AI-related revenue increased 60% year over year to US$9.3 billion, representing roughly 35% of total group revenue. Lenovo is benefiting from multiple AI trends rather than relying on a single product, including AI PCs, AI servers, smartphones and AI enabled services. This diversification could give the company a stronger position as enterprise AI adoption expands over the coming years
🖥️ Infrastructure Business Shows Exceptional Momentum
The Infrastructure Solutions Group was the biggest standout, with revenue almost doubling to US$8.5 billion and operating profit reaching a record US$777 million. Even more importantly, Lenovo’s AI server pipeline jumped 157% quarter over quarter to US$54 billion. If a meaningful portion of this pipeline converts into shipments, the infrastructure division could remain one of Lenovo’s strongest earnings drivers
💻 PC Leadership Adds Stability
Lenovo’s traditional PC business also remains a major strength. The company increased global PC market share to 24.2%, extending its lead over the second-largest manufacturer to more than five percentage points. AI PCs are becoming increasingly important, with Lenovo holding a 25.1% share of the AI PC market
This gives Lenovo exposure to the AI upgrade cycle while maintaining its established position in the broader PC market
⚠️ Valuation and Accounting Risks Need Attention
Despite the excellent operating performance, investors should not ignore Lenovo’s reported net loss of US$609 million. A major factor was a US$1.7 billion non cash fair value loss related to warrants issued in 2025.. The adjusted figures provide a clearer picture of underlying operations, but the difference between adjusted profit and reported earnings shows that Lenovo still carries financial and accounting risks that investors need to monitor
📈 Bullish Outlook, But Expectations Are Now Much Higher
Lenovo’s latest results strengthen the bullish long term case for the stock. Record revenue, accelerating AI infrastructure demand, rising AI related sales and strong PC market share suggest the company is successfully transforming from a traditional PC manufacturer into a broader AI hardware and services player
However, the stock has already reacted strongly to the earnings report, meaning expectations are significantly higher. Going forward, continued AI server growth, margin expansion and conversion of the US$54 billion pipeline will be critical for Lenovo to justify further upside.
Did you know that Lenovo is the largest laptop manufacturer for the Pentagon?  Long

Tencent - Can Buyers Defend the Channel?Tencent Holdings Ltd. remains bullish from a broader perspective, continuing to trade inside the red ascending channel that has guided price higher for an extended period.
Price is now testing an important technical area where the lower boundary of the channel aligns with a strong support and demand zone, creating an interesting confluence to monitor.
⭕As price tests this area, we can start looking for buy setups on lower timeframes, anticipating a bullish reaction from this support zone. For additional confirmation of the next bullish leg within the broader ascending structure, buyers would need to break above the previous major high highlighted by the green trigger area. A successful breakout would strengthen the bullish scenario, after which we can start looking for another buy setups on the retest of the broken area.
⭕However, if the current support and demand zone fails to hold, it would provide the first major indication that bullish momentum is weakening, with the focus shifting toward the next lower support area.
The reaction around this confluence zone may reveal whether buyers are ready to defend the broader bullish structure, or if sellers are beginning to gain momentum.
⚠️ Disclaimer: This analysis reflects my personal market view and is not financial advice.
Rayan Nasser
#Tencent #0700HK #Stocks #TechnicalAnalysis #PriceAction #Trading #MarketStructure Long 
Xiaomi: PullbackWithin the primarily ongoing upward wave, Xiaomi shares have recently experienced their first significant pullback, dropping nearly 18%. However, the stock is likely to resume its upward move soon, heading toward resistance at HK$36.50 and ultimately targeting the higher resistance at HK$58.70. Just below this level, we expect a brief interim correction, which should end above the HK$36.50 mark. From there, Xiaomi should continue to move higher, with the price likely reaching new highs. On the other hand, in our alternative scenario, it’s possible we could see an even deeper long-term bottom form below the HK$8.31 support (probability: 30%). Top 3 EV companies in ChinaOf the 3 companies, I am vested in two - BYD and NIO , both of which are still in the RED.
Fortunately, these are small positions to begin with but seeing it RED in my portfolio is an eye sore.
Yes, they may be dominating US in this EV race and export to many overseas countries but within China, it is a price cut throat business where heavy discounts and frequent promotions are held frequently to get rid of excess inventories. China market for EV has matured and saturated, seeing from the high inventory from BYD. They have no other options but push hard and fast out of China , to any countries, Africa, Europe , LA, etc to quicken the sales.
It is more than economics now with more local automotive companies be it in Asia or Europe complaining about the flooding of China EVs and eroding their market shares. So you can export to my country but paying a much higher import tariff , haha. At same time, consumers are fickle and they want new models , not waiting for years but within months !
So, deferred purchase heighten the problem. Some countries even have EV charging station problem - the local countries are loaded with infrastructure problems, bloated debts and government corruption. Lots of bottlenecks!
Investing has definitely broaden my knowledge to see things from a BIGGER perspective. Not just demand and supply, world leader dominating, latest trend, etc !
Innovent Biologics (1801.HK) —the "Cup & Handle" Breakout ThesisInnovent Biologics (1801.HK) is completing a multi-year Cup & Handle base—a structural accumulation pattern spanning from the 2021 biotech crash (~HK109.10** with institutional volume confirmation.
This is not a speculative biotech bet. It is a structural breakout setup with a fortress balance sheet, accelerating revenue growth, and global pharma validation.
The Setup — A 4-Year Cup & Handle
Innovent has been building this base since the 2021 biotech bubble burst. The cup body formed from ~HK20 (2022-2023), then gradually recovered to HK85–100.
Pattern Element Period Price Range Significance
Left side decline 2021–2022 ~HK20 Biotech bear market crash—weak holders shaken out
Cup bottom 2022–2024 HK$20–40 Long consolidation; institutional accumulation
Right side recovery 2024–2025 HK109.10 Gradual climb back to the left-side peak
Handle (current) Late 2025–present HK$85–100 Volatility contraction; the "rest" before the breakout
The longer the base, the higher the space. Four years of accumulation creates a powerful springboard. The measured move from the cup depth projects a target of HK$170–200.
---
The Catalyst — Earnings Are Exploding
On August 5, 2026, Innovent announced H1 2026 product revenue of >RMB 8.2 billion, +55% YoY, far exceeding market consensus of RMB 6.9 billion. Q2 alone exceeded RMB 4.3 billion, +60% YoY.
Why this matters:
· Growth is accelerating—from +38% in FY2025 to +55% in H1 2026
· The "dual-engine" strategy (product revenue + licensing milestones) is firing on all cylinders
· Core products—Mazdutide (weight loss/metabolic), Tafolecimab (cardiovascular), Teprotumumab (ophthalmology)—are all performing exceptionally well
Institutional reactions:
Firm Verdict
CLSA "1H26 product revenue far exceeds market expectations of RMB 6.9B—a positive catalyst for share price"
Citi "Product revenue growth is strong"; reaffirmed Buy with HK$115 target
Zhongtai Int'l Buy, target HK$134.50
10 investment banks have issued Buy ratings in the last 90 days, with an average target of HK$127.57.
---
The Pipeline — The "Hidden Option"
IBI363 (PD-1/IL-2α-bias) — A Potential $40B Catalyst
At ASCO 2026, Innovent presented Phase 1 PoC data for IBI363 in 1L NSCLC:
· ORR: 86.4%
· Confirmed ORR: 81.8%
· DCR: 100%
Management projects IBI363's potential market opportunity at $40B+. The asset has progressed into global Phase 3 clinical trials alongside IBI343 (CLDN18.2 ADC) and IBI324 (VEGF/ANG2).
Global Pharma Validation
Innovent has secured partnerships with Pfizer (8.85B), Takeda ($1.2B), and Roche, with over 20 collaborative programs including 5 co-development and co-commercialization pipelines.
---
The Balance Sheet — Fortress Capital
Metric Value
Cash & Equivalents >RMB 18B
Total Debt ~RMB 2.8B
Debt-to-Equity ~14.5%
Current Ratio 2.62x
2025 Net Profit RMB 814M (First profitable year)
The company has a fortress balance sheet with ample cash to fund years of R&D without dilution risk. The first profitable year (2025) confirms the business model is working.
---
Technical Setup — The Trigger
Level Price Significance
52-Week High (Pivot) HK$109.10 The breakout line—clearing this triggers the Cup & Handle
Current Price HK$90.15 Trading in the upper handle; consolidating post-earnings
Support HK$85–87 50-day MA zone—first floor
Critical Support HK$82.00 Handle invalidation level—if broken, the pattern fails
Volume Condition: The breakout must be accompanied by volume >15M shares (well above the 3-month average) to confirm institutional participation.
The Tape (August 5, 2026):
· Volume surged +498% from 1.52M to 9.09M shares post-earnings
· Intraday high reached HK89-90)
· Short ratio at 9.44%—bears are active but not dominant
---
Risk-Reward & Probability
Parameter Value
Entry HK$110.00 (breakout confirmation)
Stop-Loss HK$82.00 (handle invalidation)
Risk per Share HK$28.00 (-25.5%)
Target 1 HK$117.50 (analyst consensus) — +6.8%
Target 2 HK$170–200 (measured move) — +54–81%
Probability of Breakout (Conditioned on HK$110 trigger) 55-60%
Probability of Positive Return in 12 Months 65-70%
Probability of Stop-Loss Trigger (HK$82) 20-25%
The Asymmetry: Even with a 60% probability of success, the risk-reward is favorable. The measured move target of HK82 stop.
---
Execution Plan
Phase Action Rationale
Phase 1 Set alert at HK$109.10 Do not act until the trigger fires
Phase 2 Buy on breakout Entry at HK$110.00–111.00 with volume >15M shares
Phase 3 Stop-Loss HK$82.00—if breached, the handle has failed
Phase 4 Scale out Sell 30% at HK140; trail the rest to HK$170–200
Position Sizing: This is an Alpha trade—size for 20-30% of the active war chest. The defined stop protects the downside.
---
Conclusion
Innovent Biologics is the cleanest structural breakout setup in the Hong Kong market.
· 4-year Cup & Handle—the longest base on the watchlist
· Earnings acceleration—+55% product revenue growth, Q2 +60%
· Fortress balance sheet—RMB 18B cash, low debt
· Global pharma validation—Pfizer, Lilly, Takeda, Roche partnerships
· IBI363 pipeline optionality—potential $40B+ market
**The trigger is HK170–200.
---
Disclaimer: This is not financial advice. All investment decisions should be made independently and at the reader's own risk. Past performance does not guarantee future results.  Long

ZhongAn Online P&C Insurance – Falling Knife or Opportunity?At first glance, the chart doesn't look attractive. The stock remains in a clear downtrend and price continues to drift lower. However, what catches my attention is where the price is currently trading.
The stock has entered a major demand/accumulation zone that has repeatedly acted as support over the last few years. Sellers are still in control in the short term, but the risk/reward profile is becoming increasingly attractive.
From a valuation perspective, ZhongAn looks exceptionally cheap:
Price/Sales: 0.43
Price/Cash Flow (TTM): 4.59
Even by Chinese market standards, these multiples appear extremely compressed. The market is pricing the company as if growth has permanently disappeared, yet the business fundamentals tell a different story.
What does ZhongAn do?
ZhongAn is China's first fully digital insurance company. Founded by major technology and financial players including Alibaba, Tencent and Ping An, the company focuses on:
Digital property & casualty insurance
Health insurance
Consumer finance insurance
Embedded insurance products integrated into online ecosystems
AI-driven underwriting and claims processing
Unlike traditional insurers, ZhongAn was built as a technology-first insurer from day one.
Why I'm interested
What stands out is that the company continues to show operational progress:
Revenue has generally trended higher over time.
Technology-driven insurance penetration continues to expand.
The company has steadily improved efficiency through AI and automation.
Quarterly reports consistently show a business that is growing and evolving rather than shrinking.
The market appears to be heavily discounting Chinese equities as a whole, but ZhongAn's valuation suggests investors are pricing in an extremely pessimistic scenario.
Technical Picture
Long-term trend: bearish.
Momentum remains weak.
RSI is near oversold territory.
Price is testing a historical accumulation zone.
I am not calling a bottom. The stock can absolutely continue lower. However, when a company with improving fundamentals trades at less than half of annual sales and around 4.6x cash flow, while sitting inside a multi-year demand zone, it deserves attention.
For me, this is not a momentum trade.
This is a deep-value accumulation candidate where the downside is increasingly reflected in the price, while the upside depends on the market eventually recognizing the gap between valuation and business performance.
The trend is still down. The valuation is screaming cheap. That's exactly why ZhongAn is on my watchlist.  Long

China Railway Group Limited (0390.HK) - Daily Technical AnalysisA technical analysis for China Railway Group Limited (Class H - 0390.HK) HKEX:390
Price: 3.55 HKD (-0.56%) Timeframe: 1 Day (Daily)
1. Price Action & Trend Overview
Current Level: 3.55 HKD (Close: 3.55, Change: -0.02 / -0.56%).
Recent Rebound: The stock formed a local bottom in late June / early July around 3.10–3.15 HKD (near the multi-month support baseline shown in dark red dashed line) and has staged a strong recovery back up to 3.55 HKD .
Key Dynamic Resistance: The price is currently testing the orange dashed trendline (around 3.60–3.65 HKD ), which previously acted as support before breaking down in May 2026. A daily close above this orange line is required to confirm a full trend conversion back into the upper trading band.
2. Key Technical Levels
Major Resistance 5.00 High reached around March 2026 (blue dashed overhead resistance).
Immediate Resistance 3.60 – 3.65 Orange dashed trendline (former support, now acting as supply/resistance).
Current Price 3.55 Latest daily close testing the breakdown structure.
Key Support 3.10 – 3.15 Dark red baseline support where the June/July bounce originated.
3. Indicators Breakdown
Relative Strength Index (RSI - 14):
Value: 64.45 (Signal line / SMA: 49.45).
Interpretation: Strong bullish momentum. The RSI broke out above its 50 midline and moving average, currently targeting the overbought territory (70 level). There is still room before hitting extreme overbought levels (~80).
MACD (12, 26, 9):
MACD Line: 0.044 | Signal Line: 0.025 | Histogram: +0.019
Interpretation: Bullish crossover intact. Both lines have crossed above zero into positive territory, with expanding green histogram bars indicating building upward momentum.
Volume Profile:
Trading volume during the recent July rally is modest (13.7M vs 20-period avg of 20.61M), indicating that while price is moving up efficiently, a decisive breakout above 3.65 HKD will ideally need a noticeable expansion in volume to confirm institutional conviction.
4. Trading Scenarios & Outlook
Short-Term Outlook: Cautiously Bullish
__ Scenario A (Bullish Breakout): A daily close above 3.65 HKD confirms a reclaim of the orange trendline, opening the path toward 4.00 HKD (intermediate resistance) and potentially retargeting the 4.50–5.00 HKD structure.
__ Scenario B (Pullback/Consolidation): Rejection at the 3.60–3.65 HKD zone could prompt a retest of lower support levels near 3.35–3.40 HKD before making another attempt to break higher. How many multiple of 5 years do you have ?Assume one is really smart and lucky and has some capital and starts investing at age 25.
Then , we are looking at multiples of 6 times (ie. 8 x 5 years = 40 years). He would have reach age 65 by then and perhaps pare down on his investment and move to lower risk products.
If one invested in 9988 5 years ago, what would his paltry returns be ? Sad to say, he would be in a loss position. So much hype has been said and so much coverage on a daily/weekly basis on this tech giant and of course we know so much stories about the founder, Jack Ma and his vision.
End of day, does it translate to a good returns for the investor ? If not, no matter how beautiful the story is, it remains as an illusion. Comparatively, take any of the magnificent 7 stocks and you would be handsomely rewarded. Could this be one of the reasons why the stock market remains tepid and despite years of its undervalued story, it failed to pick up and accelerate ?
Or is the Chinese government who runs the macro economic policies deter the institutional and retail investors from becoming more forthcoming ? There are many sectors that had fallen from its grace - Tuition centres, property market, solar panel, etc.
No wonder one follower said the Chinese market is more like a casino, suitable for betting than investing.
Of course, nobody knows the future and we have to wait for multiple of 5 years down the road to see how this chart will evolve. Hopefully, the current investors will stay onboard and ride the wave than to consider liquidate their holdings. After all, the company is still raking in good revenue, profitability and an important tech company in China!
Please DYODD Will Tencent become magnificent when it acquires Manus ?For those who had been following the news of Manus , you may be delighted to know that local tech giant , Tencent has proposed the same acquisition value, US$2billion to take over Manus as its largest shareholder.
Take a step back and think - if the founders of Manus wanted to be BIG in China, it could have easily approach these big guys, Tencent, Alibaba for funding but instead it chose a different path. Perhaps, its timing was key and the China government is unhappy about the US tech company acquiring the Chinese tech expertise, talent, so to speak. Kind of a tit-for tat imo.
Short term, I doubt the share price will rock the Hong Kong market but mid to longer term, this could be a potential IPO listing for Manus as Tencent being its incubator.
We are still early days at the acquisition stage as nothing much is announced , I suspect the like of Baidu, maybe Meituan might come in to take a slice of this AI market rather than let Tencent dominate it !
I am accumulating slowly in tranches and also spreading to other non tech companies as diversification strategy!
Please DYODD Long 
 Long