Comvita inverted hammer monthly chartFurther to earlier post, close up showing the inverted hammer outside of the bollinger bandsLongby dionvuletich1
Comvita Monthly Buy ZoneBuying into Comvita Monthly chart going back decades Has multiple reasons to buy technically, and is selling far below book value, has low debt to equity and current ratio of 5.54 so assets far outweigh liabilities Low dividend, but this is really a long term capital gains play say 5 years should be up to at least $5-$6Longby dionvuletich10
Rakon NZ long term buying level approachingRakon Monthly chart I'm currently looking at long term investments to hold for years, and noticed this one Current price is $0.80, but I think it could easily fall to $0.41c Downside $0.42c Dividend ~ ~5% at that price level Potential capital gain, 300% gain is pretty easy to get to $1.20, the all time high was $5.80 Could easily hold for a couple of years sell half and make 100%+ on your original money and still own some shares The upside with volatile stocks like this is that there are verRLongby dionvuletich0
Air New Zealand Monthly ChartAir New Zealand monthly chart, Descending triangle which is at 25 year low, triangle are often wave 4s which suggest it still wants to go lower I actually want to see this break the low and create a 5th wave triangle overthrow as shown This would be a great buying zone as the current price of $0.587 is offering a 7% dividend, if it were to drop to 42-44cents then it will increase to 10% yield, going back to pre COVID, the dividend went up to 0.08c Downside is $0.40 Upside is dividend 7-10% posLongby dionvuletich10
KMD NZ Buying long term positionMonthly chart Buying long term position trade for a set and forget position Currently at - 16% forward dividend - Large monthly AB=CD pattern - Monthly oversold RSI These 3 reasons alone are enough for me to get in.... Retail is doing it tough and there are going to have to be some restructuring taking place, but it is a good brand that makes good products and I know it very well and have some of their clothes in my wardrobeLongby dionvuletich111
RBD - Weekly ChartHoping this drops to 2.36-2.58 range from where it is now at $3.90 That is somewhere around the current book value of $2.26 mrq so would make sense...0 I'll keep an eye on this one, as any bullish retracement will likely go against the news... So bad news may be a good buying opportunity! Here's hoping...! upside would go up by 3x... RLongby dionvuletich0
RBD - Restaurant Brands NZX Monthly ChartBlast from the past, this was the second stock I bought back in 2005... I'm from NZ so know the company, they own KFC, Pizza Hut, Taco Bell and Carls Junior so compete in the fast food industry, and kiwis love their fast food!! Fundamentally this clearly has a story behind the fall - but I think it has overshot to the downside with basics like PE it is currently around 10 but the market is around 18 Also the revenue has been increasing steadily with EBITDA margin % sitting steady at 16-18% so RLongby dionvuletich0
Sky Network Television Limited NPV: Unlocking Entertainment and Investors, get ready to explore the world of media and entertainment with Sky Network Television Limited NPV. This company is at the forefront of delivering captivating content and presents an intriguing investment opportunity. Let's delve into why Sky Network Television Limited NPV is worth considering. Technical Analysis: Multiple Timeframes: Our analysis covers various timeframes, including 2D, 6D, 7D, 8D, 9D, and 22D charts. This comprehensive approach confirms the stock's performance trLongby MarxBabu0
Rakon Brings a DividendRakon reported strong results today but the pièce de résistance was its dividend of 1.5c per share (roughly ~1.5% gross). We called for a dividend in our initiation of coverage on the company and we’re buoyed that management listened – we think this is crucial to unlocking shareholder value and valuing the stock at a multiple on par with its international peers. Noting good growth in the 5G space alongside its position business, posting double-digit growth on both fronts. Expecting FY23 FWB:27MRby BlackBull Markets7
Rakon: Worth +$1.40; Management should institute a dividend Rakon is a NZ based manufacturer of frequency control chips which enable data transmission, particularly for satellites and the communications industry as a whole. The company forecasts HKEX:40 -43M of EBITDA for the FY23 and trades around 8x earnings. We think the company looks materially undervalued at 8x earnings, largely because the board has not declared a dividend – we think a declared dividend would act as a catalyst that sees the stock re-rate to ~$1.10-1.40 per share. The catalyst is RLongby BlackBull Markets3
Synlait MilkCould see a bottom in the NZ Dairy market, why..... Dairy its their biggest export market. This can also help the fight against inflation and also with GDP as they could see a cool off in the housing/construction market due to Rate hikes. Also seeing A2 and Fonterra companies doing well this last week with good amount of volume and a nice Gap in price indicates to me strong buyers here. Im gauging Synlait Milk could see a +100% gain poss within a year or 2. If that level holds and show signs Longby BullnBear_Markets15
AIR NEW ZEALAND BEAR CALLSAir New Zealand is in a Wave 4 consolidation for continuation to the downside. Invalidation is a break to the upside of the purple box.. The catalysis would need to be something much worse than covid. And looking at other airlines it shares the same fate... is it possible could 'they' inflick some type of natural disaster that will disrupt travel? Shortby BullnBear_Markets3
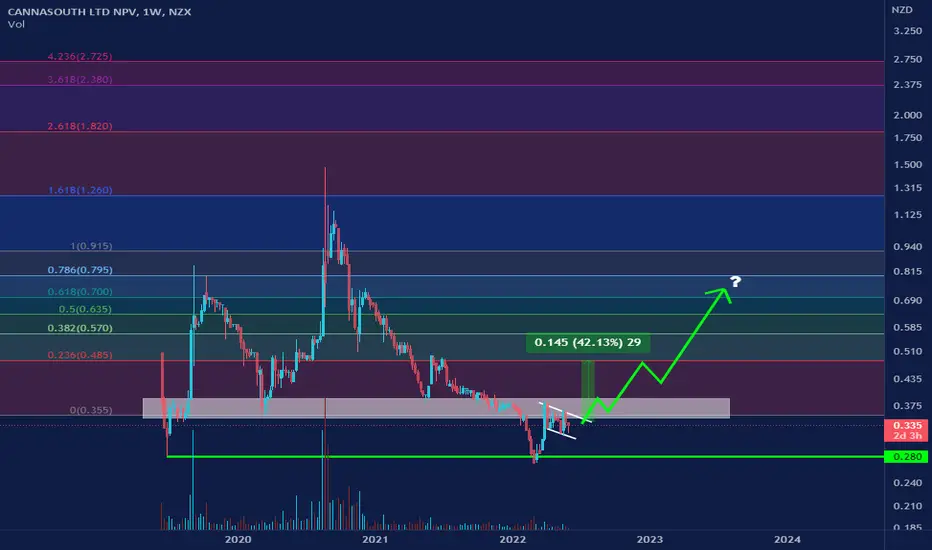
CANNASOUTH - BULLISH So much Bullish sentiment for this market to run. The pharmaceuticals aspect of this will be a breakthrough for medical use which will have adoption very quickly. Not to mention recreational use also easing up in many parts of the world will see big demand. Remember, do your own research!! CLongby BullnBear_Markets2
Stay neutral, AAIA to go up again probably in 2 to 3 months.Although currently the COVID-19 is hitting the airline industry hard, it seems that New Zealand is somewhere between halfway to near its peak in the Omricon wave. According to the Rate Of Change on "Confirmed_NZ", NZ New cases usually plateau somewhere around 20. Currently the Rate Of Change is around 10. It is also being seen that the Rate Of Change is already slowing down. Thus, New Zealand is near the plateau of new case numbers. Once new case numbers start going down, air travel to by Amol_Soneji2
MERCURY NZ LTD NPVMercury NZ Ltd. engages in the generation and distribution of electricity from hydro, geothermal, and gas.Longby samsalari332
ASX banks comparedreading charts after the event only highlights the need to understand fundamentals.by aspiringguru0
AIR.NZ high returns for the next couple of years For stable investors, we have seen the pandemic and preventive measures taken by the countries that have affected the airlines market, Suspension of flights, and the ban on receiving travelers in some countries, High oil, energy prices, and layoffs have made a huge collapse of airlines market. for the New Zealand airlines, the time is coming to buy the small fish, with the share price dropping 49% in three years and the COVID-19 negative news, we can go long on AIR.NZ stock. Corporate directorsLongby youssefallax5
Air nz back in businessBreaking its overall trend resistance since covid last year air nz has been bought out its long positions between 1,30-1,55 zone and is currently entering a bullish channel for 2022. ITs overall support has now increased and with covid pandemic almost being finished with vacc rates close to 90% we will see the tourisim business looking to get back in 2022, Price prediction,2.20 by feb and 3-5 dollars within the following years with an increase in EV's with its 2030 first electrical plane forecasLongby Glo12351223
Confirm levels and look for Longs for NZ re-openingWith further re-opening of domestic air travel in New Zealand and potential foreign destinations opening with higher vaccination rates - it would seem a good time to start reviewing companies like Air New Zealand.Longby Adam-Cox2
 LongLongLong
 Long
 Long
 Long
 Long
 Long
 LongShort

 Long

 Short
 LongLongLongLong