Is the US Central Bank Going to Cut Interest Rates At All?After the US announced fresh tariffs globally on 1st of August, the markets experienced a meltdown, followed by a rebound the next trading day.
The reason cited: traders are anticipating that the Fed to cut interest rates soon with the 30 day Fed fund moving much higher.
We will track the traders’ sentiment behind this anticipation, and learn how we can access to its fund flow.
30 Day Federal Funds Futures and Options
Ticker: ZQ1!
Minimum fluctuation:
1/2 of one basis point (0.005) = $20.835
30 Day Federal Funds Futures (May 2028)
No trades
No trades
In-depth trading ideas
CME FedWatch : the essential tool to consult before the FedThe CME FedWatch Tool is a free and widely used resource offered by CME Group. It has become a key reference in the financial industry for tracking, in real time, market expectations about upcoming interest rate decisions by the U.S. Federal Reserve (Fed). Frequently cited in financial media, this tool allows traders and analysts to assess the likelihood of a rate hike, hold, or cut ahead of each scheduled FOMC meeting.
How does it work?
At the core of the FedWatch Tool lies data derived fro
Decoding Fed Rate Changes via Federal Funds Futures Index◉ What Are Federal Funds Futures?
● Definition: Federal Funds Futures are financial contracts traded on the Chicago Mercantile Exchange (CME) that allow market participants to bet on or hedge against future changes in the federal funds rate (the interest rate at which banks lend to each other overnight).
● Purpose: These futures reflect the market's expectations of where the Fed will set interest rates in the future.
◉ How Federal Funds Futures Work?
● Pricing: The price of a federal f
Money Market says that rate cut will be an urgent one (again)Just take a look on a rate cut expectations.
In a short, the main technical graph is a difference (spread) between the nearest futures contract on FOMC interest rate (in this time Sept'24 ZQU2024) and the next one futures contract (in this time Oct'24 ZQV2024).
It's clear that spread turned to negative in 2024, and heavily negative over the past several weeks. Historical back test analysis says that in all of such cases, FOMC is to cut interest rates immediately.
The next scheduled FOMC meeti
The US Election and Possible Fed Rate DetourCBOT: Micro 2-Year Yield ( CBOT_MINI:2YY1! ), Micro 10-Year Yield ( CBOT_MINI:10Y1! )
Last Thursday night, I watched the first Biden-Trump presidential debate live on TV, along with tens of millions of likely voters of the 2024 US presidential election.
Who won the debate? According to the exit poll conducted by 538/Ipsos:
• 60.1% of the likely voters being polled said former President Trump performed best;
• Only 20.8% said President Biden performed best at the debate.
However, the debate m
🎲 Interest Rates. To Cut, or not to Cut. That is the questionJamie Dimon Sees ‘Lot of Inflationary Forces in Front of Us’, as in recent interview to Bloomberg JPMorgan CEO has warned for months that rates could stay high.
Jamie Dimon said he’s still more worried about inflation than markets appear to be.
The JPMorgan Chase & Co. chief executive officer said significant price pressures continue to influence the US economy and may mean interest rates will be higher for longer than many investors are expecting. He cited costs linked to the green economy, r
An Uncharted Landscape of Prolonged Yield Curve InversionCBOT: Micro 2-Year Yield ( CBOT_MINI:2YY1! ) and Micro 10-Year Yield ( CBOT_MINI:10Y1! )
The recent US inflation cycle started in June 2020. As the global pandemic interrupted the global supply chain, the prices of goods began to rise rapidly. In the following two years, the headline CPI shot up nearly nine percent to a 40-year high.
The Federal Reserve initially judged inflation to be transitionary and sat on the sideline for almost two years. However, when it finally came into action, it did
Repricing Interest Rate Cuts! We return to Fed Fund Futures, as the market has been repricing interest rate cut expectations. At the beginning of the year, there were 150bps of cuts expected by the market on the premise of a weaker economy, falling inflation, and a softer labor market. However, none of these expectations have materialized. The market has settled into a middle ground ahead of the Fed’s interest rate projections next week.
What comes next?
As we can see, the front and deferred month (December) Fed Fund Fu
The Final Piece Of The Pre-FOMC Data JigsawAfter a disappointing labour market report last week, where a blowout nonfarm payrolls print was overshadowed by rather dismal details in the household survey, focus now turns to the February US CPI report, being the last significant piece of the data jigsaw before the March FOMC meeting.
Off the back of hotter than expected inflation figures in January, with price pressures in the services sector remaining particularly stubborn, consensus sees headline CPI remaining unchanged at 3.1% YoY in Feb
Macro Trader: Swaps = DotsWell, what a turnaround it’s been. Just 57 days ago, markets were flat-out ignoring what the FOMC were saying on the policy outlook, and pricing as many as six 25bp rate cuts over the course of the year ahead. Now, less than two months later, the swaps are in line with the dots, as we see money markets implying just 75bp of easing this year, with the first 25bp cut not fully priced until July. Naturally, this begs the question of how we got here, and what comes next.
It must be said that the haw
How Many Interest Rate Cuts in 2024?In January 2024, the market had priced in more than 150 basis points worth of interest rate cuts. This suggested six 25-basis-point cuts throughout the year. Market participants believed that economic weakness was on the horizon, thus pricing in more cuts than the Fed’s Summary of Economic Projections (SEP).
Why the Change?
The continued strength of the labor market has fueled consumer spending and confidence. Energy prices have remained in focus, and natural gas prices have fallen by more
The Summer Of Rate CutsLondon is cold, wet, and grey at present – rather typical of your average British winter. I hope, then, that you’ll forgive me for looking ahead to the brighter summer months, particularly as financial markets are beginning to do the same.
Even after a hotter-than-expected January US CPI report, money markets continue to price a ‘summer of rate cuts’. Though the, somewhat futile, game of guessing, and second-guessing, when central banks will kickstart easing cycles, and how deep these cycles w
Fed Funds Futures - Repricing Economic Resilience?Recent price action in the CME's 30-day Fed Funds Futures has ruled out one cut for 2024. As of the end of 2023, the spread between the front-month Fed Funds Futures and the deferred (December) ones indicated a 150-155 basis points spread, suggesting that the markets were anticipating six cuts in 2024. However, recent developments have prompted a reevaluation, making market participants rethink the likelihood of six cuts.
Economic Developments:
On January 4, ADP NonFarm data reported an addi
Fed Pause is the New Restricted PolicyCME: Micro Russell 2000 ( CME_MINI:M2K1! )
Global financial market orbits around Federal Reserve’s interest rate decisions. By concept, hiking interest rates means monetary tightening while cutting them signals easing. In reality, market perception to the Fed actions evolves over time, sometimes blurring the difference between “good news” and “bad news”.
• On May 5, 2022, the Fed surprised the market with a larger-than-expected 50-bps rate hike. The S&P 500 fell 3.6%. This is a normal market re
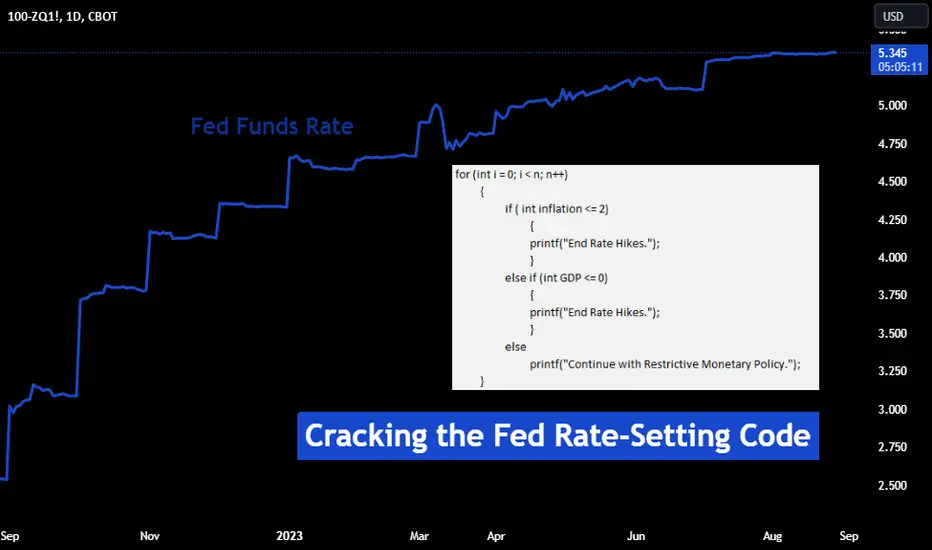
Cracking the Fed Rate-Setting CodeCME: Micro Russell 2000 ( CME_MINI:M2K1! )
On August 25th, Federal Reserve Chair Jerome Powell delivered his annual policy remark, “Inflation: Progress and the Path Ahead”, at the Jackson Hole Symposium.
The message is very clear: It is the Fed's job to bring inflation down to the 2% policy goal. The Fed is prepared to raise rates further if appropriate and intends to hold policy at a restrictive level until inflation is moving sustainably down toward its objective.
In my opinion, there is a
What to Expect in US Inflation Data for July 2023Consensus data,
Headline inflation 3.3, Core CPI 4.8
Scenario 1
If the data prints higher than expected that is core CPI at 5.0 and Headline inflation at 3.5 market participants might interpret inflation as being sticky this will influence them to price for another rate hike either in September or November pushing the fed funds rates to the range of 5.5 – 5.75 percent and expected the fed to keep rates higher for longer. That is dollar bullish especially against the Yen and Swiss Franc.
In this
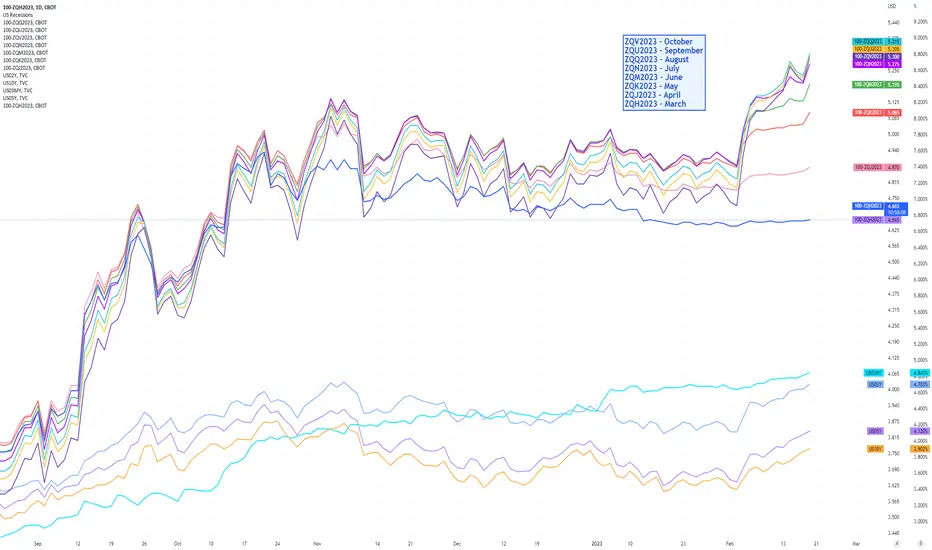
We Are One Week Out from the FOMC Rate DecisionNext week is the FOMC rate decision and the markets are pretty confident that there will be no change from the group according to Fed Funds futures (subtracting the contract value of the time frame we are looking for from 100 gives you the loose implied rate).
Interestingly though, the OECD said this morning it expects the Fed to peak at 5.25-5.50 percent which would entail another 25bp rate hike sometime soon. Also, there has been something of a 'hawkish' (or really 'less dovish') shift of lat
Gold - better levels for longs await Gold is in beast mode - we eye the 2022 and ATHs at $2070 and $2075 respectively and scalper aside it's hard to bet against the momentum play right now
The USD is finding few friends and the ST bear trend is a massive tailwind for gold. We've seen US yield curves looking like they will resume bull steepening and rate cuts are once again being priced into OIS and fed fund futures - gold is not a hedge against inflation per se, but the symptoms of high inflation and tighter policy - i.e weaker g
BOND, huge buying volume on the highs!To all the perma bulls out there, look at bonds, there won't be any pivot till higher interest rates at or above 6%.
Bonds risk-off is the most important out there, as the bond market is much bigger than the stock/indexes market.
Something will have to give, either bonds or the markets...