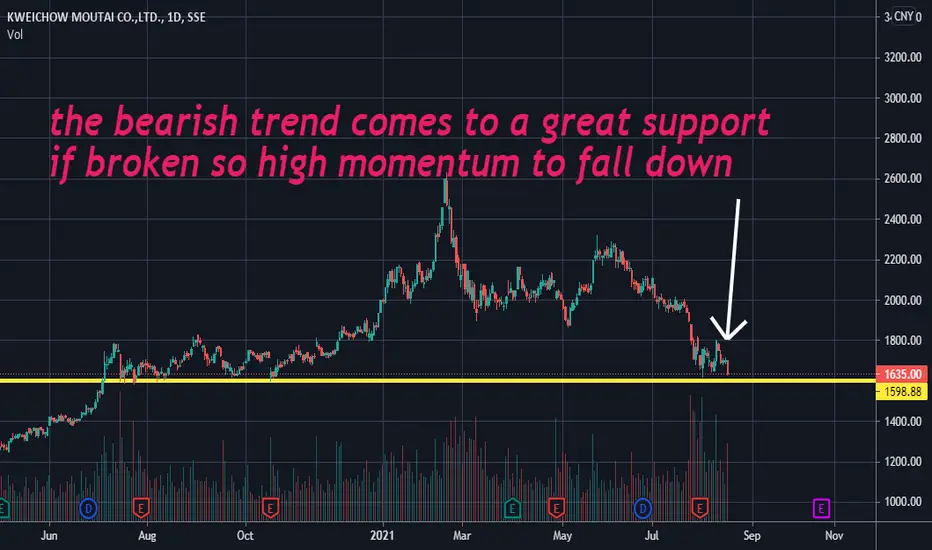
JICPT| Kweichow Moutai reached attractive buy level as expectedHello everyone. This is a follow-up post of my published idea titled 'Kweichow Moutai potential buying level of 1550' on July 28th. Back then, price was CNY 1768 per share. I guess a lot of Chinese investors doubted if it can fell to that level.
Now it sat at CNY 1550 and a lot of investors started to concern if there is much room to the downside.
In my opinion, the valuation became really attractive for me, though I observed huge sell orders from foreign institutions via the HK and Shangh
buy BYD nowThe issue of NIO’s autonomous driving has caused BYD’s stock price to fall under pressure. However, BYD’s sales soared in July and opened four bases in August to acquire three eight talents and two 12-inch semiconductor factories.
BYD Tang exports only to Norway, and the little dolphins basically arrive in the store. The sales volume is expected to be four to five thousand per month
I believe that BYD still has buying potential
JICPT| Kweichow Moutai potential buying level of 1550Kweichow Moutai is the icon of Chinese stocks. With gross margin of 90% plus, It's been served as the deep value investor's must-have holdings. In addition, the share of Moutai is the most expensive one in domestic Chinese market.
However, 2021 is not the year of Moutai. The price has dropped by approximately 37% from around 2630 created in Feb. From the valuation perspective, it fell into the reasonable zone which attracted me. I bought Chinese wine ETF and plan to add more in the next future
BOE and TCL poised for LED screen market dominanceGreat recovery and bounceback of Q1 earnings. At current price levels it is reasonable.
Growing at 15% revenue per year in this LED market of increasing demand as more items in our lives are getting integrated with the internet IoT, screens will be seen alot more in Cars, Appliances, Phones, Tablets, Displays in Outdoor areas, Offices, Advertisement Boards.
Top suppliers to look at are:
BOE Technology 000725
TCL 000100
Construction to pick up in the 2H of 2021, great upside potentia50% retracement from its highs, current valuations are very attractive at PE or 10.
I expect the construction industry to continue to expand and chinese manufacturer to become more competitive in the coming years.
Great upside from its current levels.
BOE Released its Performance Forecast: Profits Might be IncreaseBOE expects to achieve a net profit of CNY 12.5 billion to CNY 12.7 billion in the first half of 2021, with a year-on-year growth of 1001% to 1018%.
On July 13, BOE Technology Group Co., Ltd. (BOE) released its 2021 semi-annual performance forecast. According to the announcement, the basic earnings per share are expected to be about CNY 0.355 to CNY 0.361, 13 times higher than that of CNY 0.026 apiece in the same period of 2020.
The announcement shows that BOE's good performance is attributed
GoldWind is back after waiting for pullbackIf we see the consolidation around 11.50 to 12.50 this area shows a good spike in volume and breakout of its consolidation.
With China's renewable energy push, Wind energy has been very quiet considering all other areas of renewable energy have been accelerating.
Also since the launch of the Carbon Trading Exchange on Friday, this might be good enough a push to draw attention back to the wind industry.
Entered trade at 12.50 and look to take profit at around 15.50.
Other wind names that look
Possible Long for BOE Technology (incl Apple Supply Chain) Short Term looking at a short via MACD momentum, as Apple devices usually launching coming close to season.
BOE might only get 20% order, still looking a possible W pattern forming and resistance to break to see the possible profit.
Share might keep flowing down wards trending if no breakout. We lets watch...
#Apple as this company is within Supply Chain possibility
Great Walls Great Stock GainsGreat Wall Motor Company Limited is China's largest producer of sport-utility vehicles and pick-up trucks and its share price is up around 500% over the last 12 months reflecting the rapid adoption of vehicles in China as well as Great Walls continued expansion into international markets.
Share price is probably in the overbought / expensive area at the moment so if you are interested you could wait for a bit of a pull back in the 5% to 10% type range or a drop in the RSI back under 65% if it
JICPT| Gree is testing M bottom, creating buy opportunity Frankly speaking, I love Gree which is still the best Air conditioner manufacturer in China. I started to trade it back in 2012 and still hold some shares as of today.
The company has been up by more than 900% in the past ten years. It used to be must-have stock for value investors due to its outstanding financial performance. However, things started to change from 2018.
The below is my personal view for reference:
1. single-product line business strategy: No doubt, Gree makes the best AC w