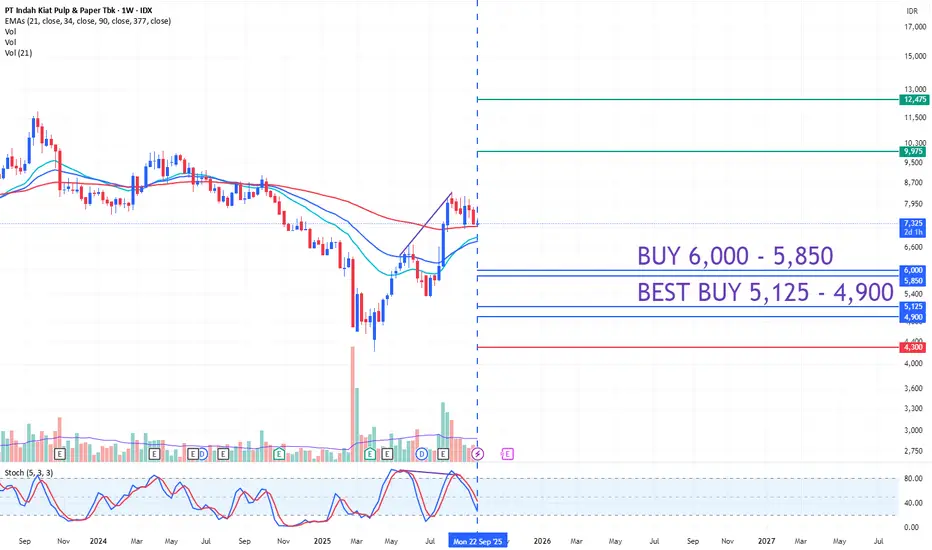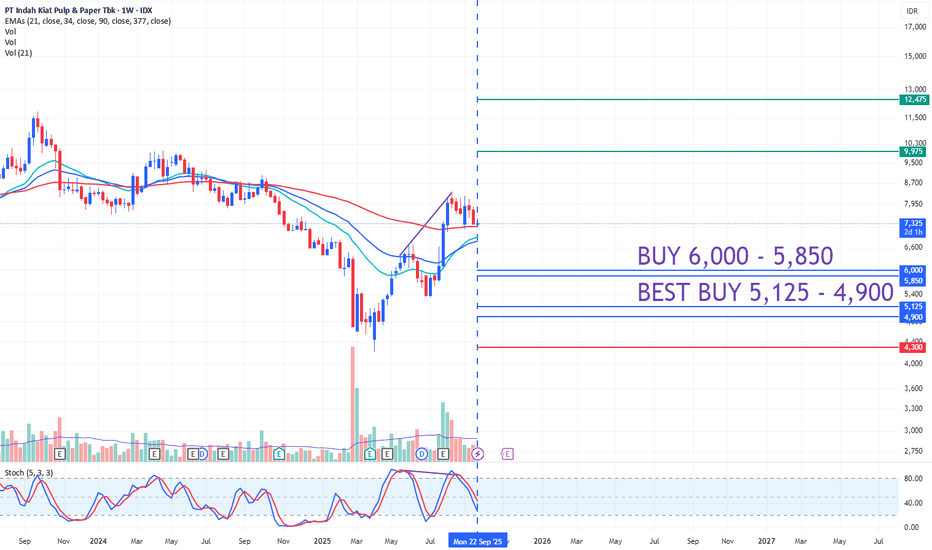
$IDX:INKP Technical Analysis Bearish Divergence Weekly timeframeFundamental Analysis:
PBV: 0.37
Technical Analysis:
A Stochastic Bearish Divergence has been identified on the Weekly (1W) timeframe, pointing towards potential declines to the cluster areas of 6,000-5,850 and 5,125-4,900.
Stoploss: 4,300
Takeprofit 1: 9,975
Takeprofit 2: 12,475
Note:
-This analysis is only valid based on the company's current fundamentals (PBV 0.37).
-This analysis becomes invalid if the upcoming fundamental report (Q3) is not supportive.
-Takeprofit 2 is contingent on favorable market tides.
IDX:INKP
$IDX:SMGR long with target price 2900 within 90 daysLONG position on IDX:SMGR with a target price 2900 in 90 days. Analyst price targets averaging 3,185.83 IDR, higher than the current 2,140.00 IDR.
A Price-to-Book (P/B) ratio of 0.33 for Semen Indonesia (Persero) Tbk ( IDX:SMGR ) suggests that the stock is trading at a significant discount to its book value. SMGR’s low P/B ratio of 0.33 could make it an attractive target for foreign investors looking for undervalued assets. The low P/B ratio and EV/EBITDA NTM ratio indicate undervaluation compared to peers. This could appeal to value investors looking for bargains. Qatar has recently shown interest in Indonesian sectors like energy, tourism, and real estate, but nothing explicitly ties IDX:SMGR to Qatari funds. Without concrete deals or announcements, it’s speculative.
However, low P/B can also signal concerns. The market might be pricing in risks like declining profitability, operational challenges, or sector-specific headwinds—cement is a cyclical industry tied to construction and infrastructure, which can be volatile. It’s also possible that the book value itself is inflated due to outdated or impaired assets.
Current Share Price 2,140, 52-Week Low 2070, 52-Week High 5650. The current share price of 2,140.00 IDR, near the 52-week low, might suggest a buying opportunity for value investors, especially given IDX:SMGR ’s role as a state-owned cement giant tied to Indonesia’s infrastructure sector. Likely that infrastructure spending in 2025, including the new capital Nusantara, will boost cement demand, supporting long-term growth. IDX:SMGR holds over 40% of Indonesia's cement market and has recently acquired Semen Baturaja, potentially enhancing efficiency.
Given the undervaluation, significant infrastructure spending, and analyst optimism, IDX:SMGR appears to have potential for a long trade.
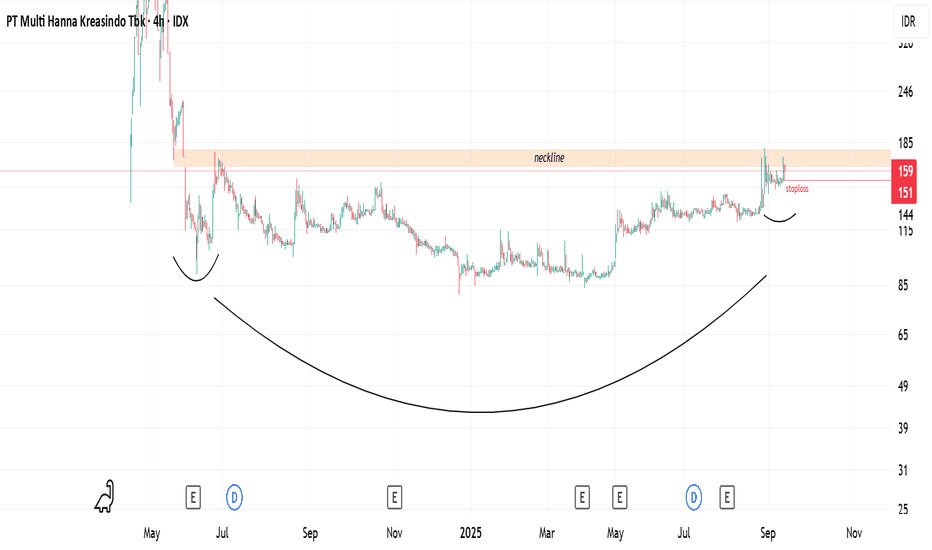
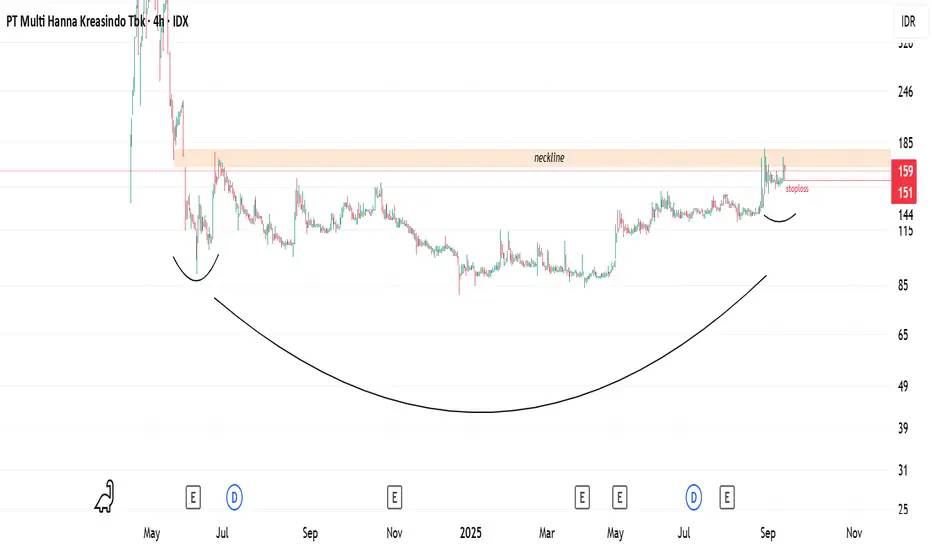
$MHKI - Inverted Head and Shoulder?So, the chart doesn't really show that it's forming an inverted head and shoulders pattern yet. But if you look at the moving averages, this stock is still above the 10 and 20 moving averages, which means it's still in a decent uptrend on the daily timeframe.
This could be a chance to make a speculative buy with the stop loss mentioned above!
Tradeplan:
Buy 159 - 156
Stoploss < 151
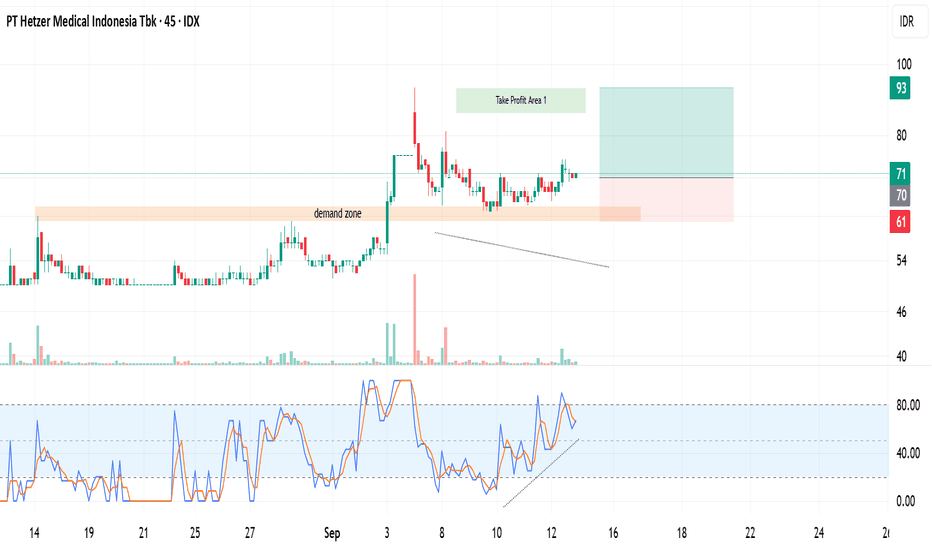
MEDS - rebound from supply area IDX:MEDS
In terms of trend, it's starting to move from sideways to an uptrend. The structure that's forming looks pretty solid, with the supply area that was previously broken now successfully turning into a demand area, as shown by the stock price rebounding in that area.
For the 1-hour intraday timeframe, there's also a golden cross happening between the 10 and 20 SMA.
Buying Area: Feel free to buy near the 3, 5, or 10 MA.
For Stoploss, if it can’t hold above the demand area below.
This trade plan has a Risk:Reward ratio of 1:2.56.That makes this stock pretty interesting to trade.
BBRI - Analisis Fundamental / Analisis TechnicalFundamental
Price: ~IDR 4,140 per share.
Earnings: EPS ~376, showing good profit generation.
Dividend Yield: ~8.4%, quite attractive.
Assets & Equity: Growing steadily, though debt is also increasing.
Strength: Strong in micro/SME lending, wide customer base.
Risk: Economic slowdown, rising interest rates, and loan defaults (NPL).
Technical
Support: IDR 3,740–3,900
Resistance: IDR 4,290–4,380
Trend: Short-term downtrend, but near oversold → possible rebound.
Current Action: Price is consolidating (sideways).
Outlook
For long-term investors: Good for dividend and growth exposure.
For short-term traders: Buy near support, sell near resistance.
Risks: Economy, regulation, and loan quality.
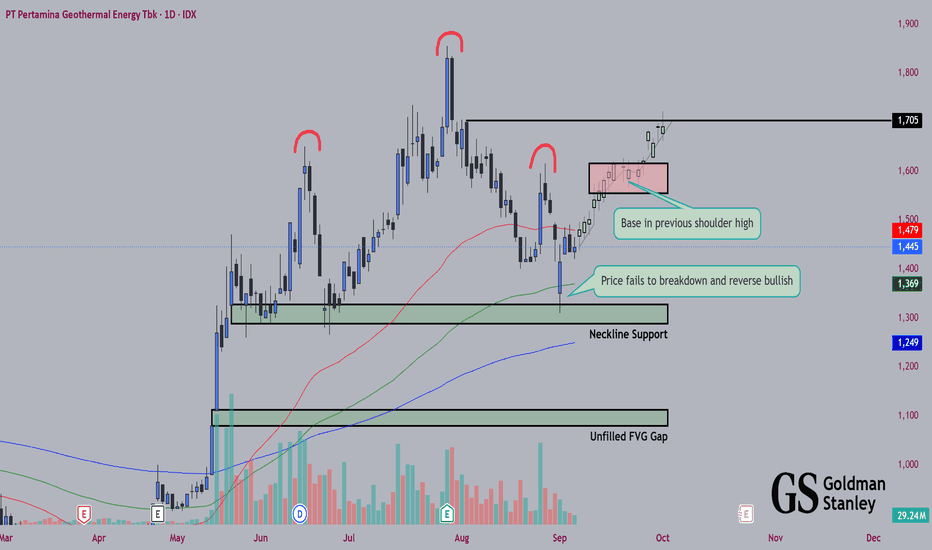
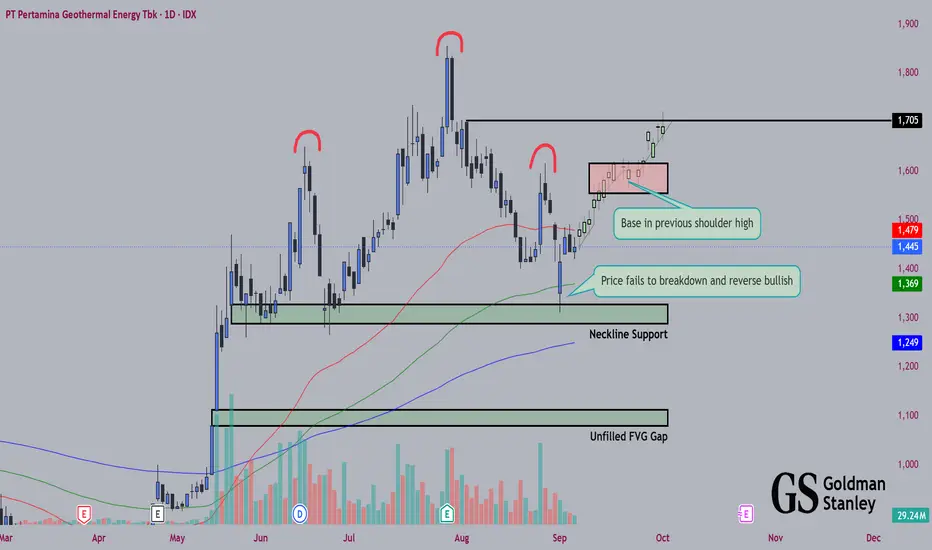
ER PGEO 07/09/2025My technical view for PT Geothermal Energy as of 07/09/2025. Seems to be failed Head & Shoulder pattern, as price fails to breakdown and continue bullish reversal with strong momentum. Moving on, expecting price to reach previous shoulder high and form a base before eventually moving to reach previous heads high of 1800.
BBCAShort Term: There is a chance of a rebound to the 8,400 – 8,600 area if the 7,800 support holds.
Medium Term: As long as the price has not broken through and remains above 9,000, the trend is still likely to decline.
Important Levels:
Support: 7,800 – 7,600
Resistance: 8,600, then 9,600 – 10,000
Strategy
Aggressive traders: Can try to enter near support (7,800 – 8,000) with a target of 8,400 – 8,600, stop loss below 7,600.
Conservative traders: Wait for the price to break through and stay above 9,000 to confirm a reversal.
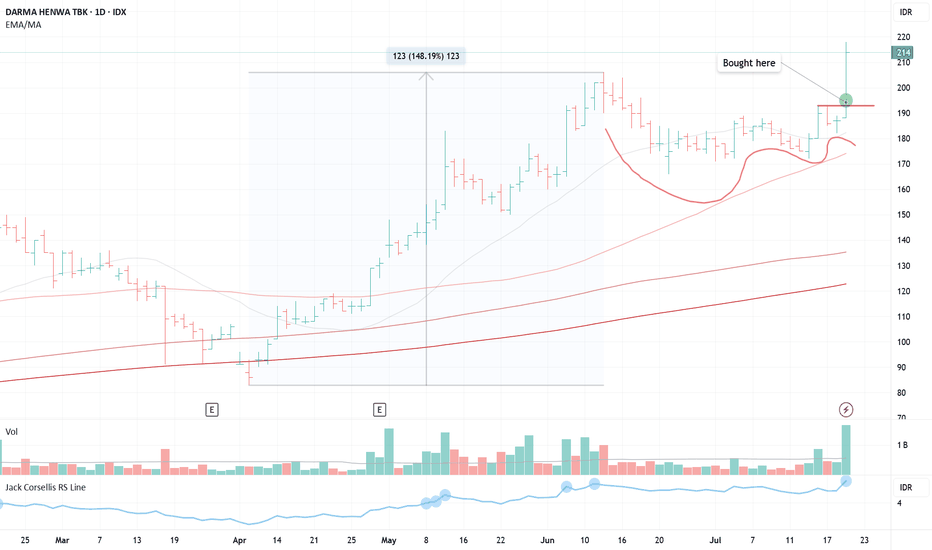
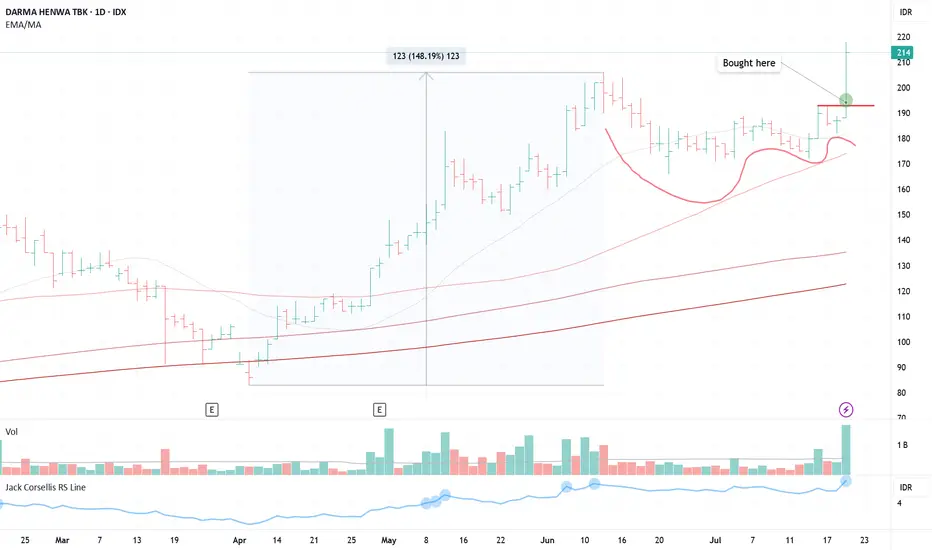
$DEWA (VCP - 6W 19/6 3T)Position update: July 21, 2025.
Key factors:
1. Confirmed stage 2 uptrend.
2. A textbook Volatility Contraction Pattern (VCP) with a clearly defined, low-risk entry point.
3.Currently forming a VCP following a prior price surge of nearly 150%, demonstrating strong momentum.
4. The stock moves on its own drummer, rallying close to 150% while the broader market advanced just 23%.
5. Displays high relative strength, outperforming sector and index benchmarks.
6. Volume has dried up, indicating less supply coming to the market.
7. Significant volume expansion on the breakout.
Considerations: Despite a favorable technical setup, risk should be managed diligently given the stock's sharp ascent and potential for profit-taking. Establishing stop-loss levels and monitoring market conditions is essential.
This is another quintessential VCP breakout with a clear pivot entry and minimal risk. I’m starting to see increased traction in the market now—a very positive sign to scale up trading size.
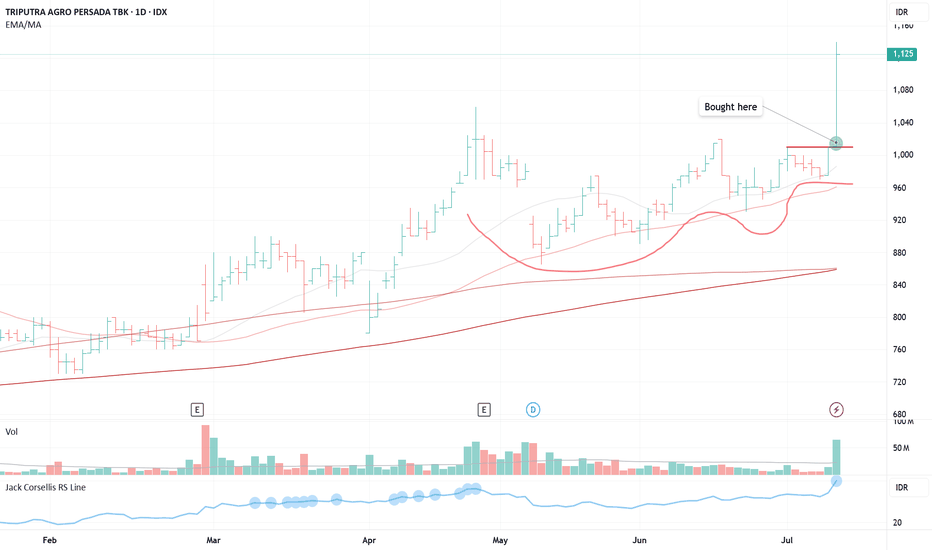
TAPG (VCP 10W 18/4 3T)Position update: July 9, 2025.
Key factors:
1. Confirmed stage 2 uptrend.
2. A textbook VCP setup with a clear, low-risk entry
3. Has absorbed its majority line of supply.
4. The stock moves on its own drummer, hitting an all-time high while the index struggles to reclaim its highs.
5. High relative strength.
6. Volume has dried up, indicating less supply coming to the market.
7. Strong fundamentals, with consistent triple-digit year-over-year earnings growth.
8. Significant volume surge on the breakout.
Considerations: Despite a favorable technical setup, risk should be managed diligently given the stock's sharp ascent and potential for profit-taking. Establishing stop-loss levels and monitoring market conditions is essential.
This is a quintessential VCP breakout with a clear pivot entry and minimal risk. I’m starting to see increased traction in the market now—a very positive sign to scale up trading size.