Socimis: Merlin and Colonial fall because of the Tax ReformThe Spanish real estate sector is facing one of its biggest challenges in years, following the announcement of the agreement between PSOE and Sumar to include in the General Budget a proposal that eliminates the favorable tax regime for Socimis. This measure has not only caused significant falls in the share price of the main companies in the sector, such as Merlin Properties and Inmobiliaria Colonial, but has also sparked a debate on the economic and strategic impact of this decision.
Stock market impact
The uncertainty hit Merlin Properties hard, whose shares fell 4.24% yesterday to 9.71 euros, erasing all the gains accumulated during the year. Inmobiliaria Colonial fell 3.11% to 5.29 euros, accumulating a loss of 14.6% so far in 2024. Today's opening was positive at 9.77 for the former and 5.525 for the latter.
These falls have only reflected not only the market's immediate reaction to these changes, but also concerns about the future of the sector. The elimination of this tax exemption, which currently allows Socimi to be taxed at 0% instead of 25% corporate income tax, will drastically reduce firstly their cash generation and secondly their ability to pay dividends on a one-off basis. In other words, this law is likely to have dynamited the Socimi business in part.
It is unlikely that such a measure will gain the necessary support in Parliament, since the mere announcement has already affected the perception of the real estate sector. Even, extending to apply a tax on undistributed profit, something similar to a proposal already discarded in 2020. The recommendation possibly with nothing clear in the face of such a law for large managers could move from “Buy” as a sure thing to “Sell”, in a move ahead of such high regulatory uncertainty for the sector. Or at the very least, to establish a speculative operation and not so much an investment one.
Sector Response
Merlin Properties and Inmobiliaria Colonial have expressed their concern, warning that the tax change would not only impact their business model, but also discourage foreign investment in Spain. Colonial, with a strong presence in Paris, has already indicated that it will re-evaluate its investment strategy, hinting at the possibility of redirecting its operations to more stable and fiscally attractive markets.
For its part, Merlin Properties highlights that the current tax regime for Socimis is aligned with international standards for REITs, considered essential for the development of offices, shopping centers and logistics.
Technical Aspect
If we look at the chart of Merlin (Ticker AT: MRL.ES) and Colonial (Ticker AT: COL.ES) is palpable fear already reflected on the 12th in both assets, currently Merlin had developed a good year upward until mid-September, from that date has been correcting healthy in demand liquidating selling positions to collect profits and on Friday and Monday have been given the signals indicated. Currently it is not very clear if it will return to the POC zone around 10.50, since the RSI indicates an oversold level of 33.69%, so it should recover positions.
As for Colonial, its evolution has been very strong and with a strong upward trend and then, like Merlin, it has corrected in September. Currently the bearish gap has affected it in a different way since both companies have had very different performances, but it would not be unusual to see how this one also tries to climb towards the POC of 6 euros, although it will cost it since its current RSI is 45.58% so it is not as oversold as in the first one.
Currently both practically replicate the situation of a 50-day average crossing below the 100-day average, although in the second one it seems that the 200-day average is starting a bullish crossover over the 100-day average, so we could see a faster price recovery in Colonial than in Merlin, due to the opportunistic appetite of short-term speculators.
Conclusion
The elimination of the Socimis tax regime could radically transform the Spanish real estate landscape. Beyond the pressure on large companies in the sector, the country risks losing its attractiveness as an investment destination compared to other European markets. Parliament's final decision will mark a turning point, not only for the Socimis, but also for the general confidence in the Spanish economy as a safe place to invest.
Ion Jauregui - Analyst ActivTrades
*******************************************************************************************
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and such should be considered a marketing communication.
All information has been prepared by ActivTrades ("AT"). The information does not contain a record of AT's prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acing on the information provided does so at their own risk.
 Long

 Short

 Long

 Long

 Long

BlackRock may acquire 20% stake in NaturgyFinancial giant BlackRock has received approval from the Spanish government to acquire 20% of Naturgy, consolidating its position as a reference shareholder in the energy company. This stake comes from the purchase of alternative asset manager GIP, which had held that position in the gas company's capital since 2016. The transaction marks a major change in Naturgy's shareholding structure, following the failed takeover attempt by Emirati energy company Taqa before the summer.
The Council of Ministers, under the leadership of the Ministry of Economy, has given the green light to the transaction, maintaining its policy of attracting foreign investment without compromising the country's strategic interests. Although the conditions imposed have not been specified, BlackRock is likely to face similar requirements to those set in 2020, when the Australian fund IFM acquired a 15% stake in Naturgy. These conditions include commitments in renewables, head office in Spain, and labor stability.
Naturgy’s Outlook
With the entry of BlackRock, new perspectives open up for Naturgy, both financially and strategically. BlackRock is known for its long-term approach and its ability to provide stability in the companies where it invests. This could reduce selling pressure from other funds, such as CVC, which also owns 20% of the company and has been looking to exit the capital in recent times.
On an operational level, BlackRock's entry could facilitate the implementation of new energy transition projects, as the company has a strong commitment to sustainability and renewable energy investments. Naturgy could leverage this capital injection to expand its clean energy operations, which would be aligned with government policies and global trends toward decarbonization.
In addition, BlackRock could help strengthen Naturgy's international presence, opening doors to new markets and growth opportunities, all in an environment where financial stability and debt reduction will be key to improving the company's competitiveness in the coming years.
Ion Jauregui - Analyst ActivTrades
*******************************************************************************************
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and such should be considered a marketing communication.
All information has been prepared by ActivTrades ("AT"). The information does not contain a record of AT's prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acing on the information provided does so at their own risk.
 Long

Banco Sabadell Rejects Hostile Takeover Bid with Record ProfitBanco Sabadell reported a record net profit of €791 million in the first half of 2024, up 40.3% year-on-year, beating analysts' expectations. The bank increased its promised dividend by 21%, committing to distribute €2.9 billion between 2024 and 2025, in response to BBVA's hostile takeover bid. Return on tangible equity (RoTE) rose to 13.1%, and the top-quality capital, CET1 fully loaded, reached 13.48%. The improvement in profits was due to growth in SME and corporate financing, mortgages, and an improved credit risk profile. The bank also announced an increase in pay-out to 60%, with the first payment of 8 cents per share in October. The board of directors rejected BBVA's takeover bid as insufficient.
Looking at the chart since February, Banco Sabadell has been climbing, with its latest price rise since June 14 to date being 16.25%. This shows that its enterprise value is very well consolidated in the market. If we compare it with BBVA, which since the publication of the hostile takeover bid in May, has shown how Sabadell sustained its price, while BBVA depreciated. Since the last period of June both firms have been climbing positions. This is closely related to the ECB's monetary policies.
Sabadell is currently giving an overbought RSI signal at 69.48% which we could keep an eye on after the issuance of dividend payments, a very frequent occurrence. If we look at the price bell, currently the POC is 1.1250, with the high being the current trading area in a rather double bell.
It would be expected with the “Hype” that has been created that Sabadell will rally a bit more to then try to establish a new higher support zone.
Ion Jauregui - ActivTrades Analyst
*******************************************************************************************
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and such should be considered a marketing communication.
All information has been prepared by ActivTrades ("AT"). The information does not contain a record of AT's prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acing on the information provided does so at their own risk.
 Long

Long 
 Long

 Long

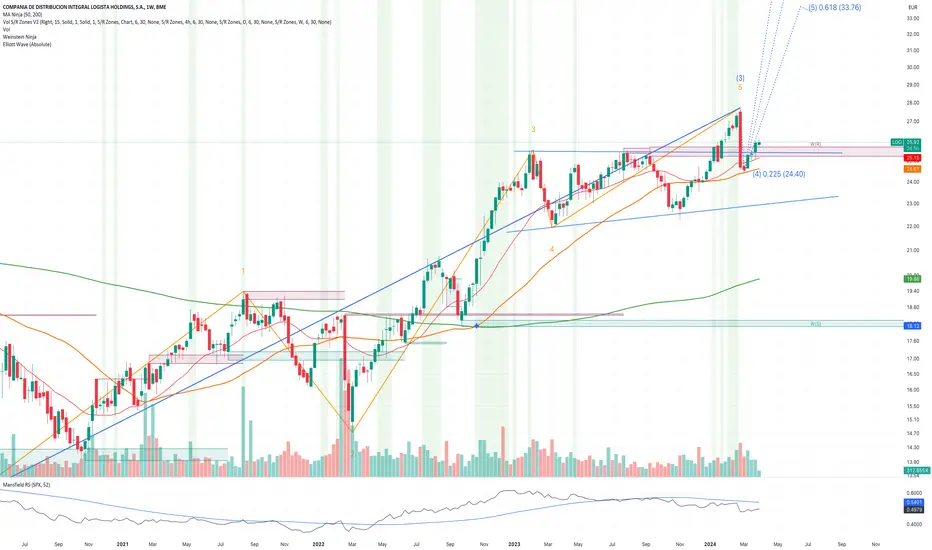
LOG Potential Breakout Logista $LOGLOG Potential Breakout Analysis
BME:LOG is indicating a potential breakout based on technical analysis, suggesting an opportune moment to consider delving into Logista.
Why Logista?
Logista, as a leading distributor and logistics operator, plays a crucial role in various industries, including tobacco, pharmaceuticals, convenience, and technology. The company's strategic positioning and efficient supply chain management make it an attractive option for investors looking to capitalize on the logistics sector's growth potential.
Compelling Reasons to Consider Logista:
Market Dominance: Logista holds a strong market position in its core businesses, benefitting from long-standing relationships with key clients and a wide-reaching distribution network.
Resilience: The essential services provided by Logista ensure consistent demand for its logistics solutions, making it a stable investment choice even during economic uncertainties.
Innovation: Logista continues to invest in technology and automation to enhance operational efficiency and meet evolving customer needs, positioning itself for sustained growth in the logistics industry.
Exploring opportunities in Logista could offer a blend of stability and growth prospects within the logistics sector. Stay tuned to BME:LOG for further developments signaling a potential breakout to make informed investment decisions effectively.  Long

 Short

 Long

 Long

Short 
 Long

 Long

 Long

 Long

 Long

 Short