Short

 Short

 Long

 Long

The Ultimate Inflation Proxy: Why Sumitomo Metal Mining (5713.T)Hello Traders,
Are you feeling cautious about buying major tech names or the Nikkei at these elevated levels? Looking for a robust safe haven against sticky inflation?
If we peel back the layers of global cross-asset rotation, a massive subterranean shift is occurring. Today, I want to share a quantitative and macro perspective on why Sumitomo Metal Mining (TSE: 5713) is currently exhibiting a textbook setup for global value and macro investors.
1. The Macro Divergence: Why Base Metals?
When we analyze the market not just against the USD (DXY) but against the broader commodity index (DBC), a stark reality emerges. The "real return" of many US mega-caps and major indices is essentially being eaten alive by inflation, flatlining against DBC.
Where is the smart money hiding? Our cross-asset relative strength models indicate a massive, localized capital concentration into the Japanese "Non-Ferrous Metals" sector, heavily outperforming both global peers and the broader TOPIX. 5713 is the undisputed crown jewel of this inflow.
2. Don't Let the Price Tag Fool You: A Fundamental Beast
Trading around the 10,000 JPY psychological level, the stock might visually look "expensive" to retail traders. However, a peek under the hood reveals a valuation anomaly where earnings growth is drastically outpacing the stock price.
Margin Expansion: Over the TTM, Operating Margins have surged from 11.32% to 16.65%, and Net Margins from 10.12% to 16.28%.
Capital Efficiency: ROE has improved to a solid 12.08%, and ROIC to 10.30%, placing it well within the ranks of global quality compounders.
Cash Flow Explosion: Free Cash Flow (FCF) per share has skyrocketed over 4x (from 70.2 JPY to 301.4 JPY). It is literally a cash-generating machine in the current macro environment.
Fortress Balance Sheet & Dividends: With a Long-Term Debt/Equity ratio of just 0.15, debt risk is virtually non-existent. Dividends per share have more than doubled (104 JPY to 228 JPY) with a highly sustainable payout ratio of 35.1%.
Deep Value Multiples: Despite the absolute price, it trades at a mere 11.59x TTM P/E, 1.28x P/B, and an EV/EBITDA of 10.91. The fundamentals have completely detached from any notion of being "overbought."
3. Technical Setup: The Multi-Decade "Wave 3" Dream
Take a look at the attached ultra-long-term Monthly (1M) chart.
The Macro Channel: Mapping the cycle from the early 2000s using a Fibonacci channel reveals that after a massive, prolonged consolidation (a macro Wave 2), the asset is currently launching perfectly off the lower trajectory. This aligns flawlessly with the sticky consolidation seen in global commodity indices.
The "Dream" Target: If this truly is the genesis of a super-cycle Wave 3, the upside targets (e.g., the 1.618 extension around 25,000 JPY) seem almost absurd. Let's keep that strictly as a "dream scenario" for now.
Realistic Entry Strategy: Dreams aside, the massive monthly momentum is undeniably pointing north. After fighting through the 10,000 JPY psychological barrier and squeezing energy, we are looking for the initial breakout. The highest-probability setup here is to buy the dips on lower timeframes (e.g., 30m/1H), backed by the bulletproof fundamentals mentioned above. A realistic initial target is the upper channel boundary near 18,000 JPY.
We are witnessing a rare dual-tailwind: a Global Macro Capital Shift combined with an EPS & Cash Flow Explosion. Add this to your watchlist and track the relative strength!
Trade safe.
This publication is for educational and informational purposes only and does not constitute financial advice, investment recommendations, or an endorsement to buy or sell any security. All financial metrics and market analysis presented are based on publicly available data, and past performance or current financial health does not guarantee future market results. Trading and investing in equities and commodities involve substantial risk of loss. All investment decisions and trading executions must be made entirely at your own risk and discretion.
 Long

 Long

 Short

SquareEnix Just Turned Its IP Into Gold | Earnings Boss DefeatedSquare Enix’s first quarter came in much stronger than last year, with net sales rising 32.3% YoY to ¥78.4 billion, while operating income jumped 88.6% to ¥17.0 billion. Profit attributable to owners of the parent climbed an impressive 175.5% to ¥13.2 billion. The numbers show a much healthier earnings mix, with Digital Entertainment once again doing the heavy lifting. For a company that has spent the last few years dealing with development costs, uneven releases and restructuring, this quarter feels like a pretty serious stat upgrade
🔥 HD Games Got a Massive Critical Hit
The real MVP was Square Enix’s HD Games business.. Net sales nearly doubled to ¥17.7 billion, while operating income exploded 510% to ¥6.1 billion. The biggest catalyst was Final Fantasy VII Rebirth expanding beyond PlayStation through releases on Nintendo Switch 2, Xbox Series X|S and the Microsoft Store. But this wasn't a one game carry. The Adventures of Elliot: The Millennium Tales, catalog sales and additional releases including Octopath Traveler, Octopath Traveler II, Star Ocean: The Second Story R and Final Fantasy X/X2 HD Remaster also contributed
Square Enix basically discovered that its old save files still have plenty of loot
🕹️ Multiplatform Is Becoming the Meta
The FFVII Rebirth performance also highlights why Square Enix's multiplatform strategy could become one of its biggest long term catalysts. Instead of limiting major releases to a single ecosystem, the company is increasingly putting its games in front of PlayStation, Xbox, Nintendo and PC players. That gives its biggest IP a much larger addressable audience and creates additional revenue opportunities years after the original launch.
For investors, this is important because Square Enix doesn't necessarily need a brand new blockbuster every quarter. Ports, remasters and catalog titles can keep farming revenue between the major releases
⚔️ FFXIV Keeps the MMO Engine Running
The MMO segment also delivered a solid performance, with net sales increasing 32.2% to ¥12.7 billion, while operating income remained strong at ¥3.6 billion. Square Enix attributed the improvement to stronger user activity following the announcement of the next Final Fantasy XIV expansion. The company also noted that some expenses were recognized ahead of the planned early 2027 release, which makes the result even more interesting. FFXIV continues to function as Square Enix's reliable endgame content, providing recurring revenue and engagement instead of depending entirely on individual game launches
📱 Mobile and Browser Are Also Pulling Their Weight
The Smart Devices/PC Browser business was another underrated winner. Net sales increased 35.6%, while operating income jumped 72.7%. This matters because Square Enix's earnings don't have to live or die by Final Fantasy anymore..
Mobile, browser titles, MMOs and catalog games create multiple revenue streams that can help smooth out the notoriously volatile AAA gaming cycle. One blockbuster can carry the raid, but having several smaller DPS players consistently dealing damage makes the overall party much harder to wipe
🚀 The Next Boss Is Guidance
Despite the monster Q1, Square Enix kept its full year forecast unchanged, so management isn't going full "WE ARE SO BACK" just yet. That caution is probably the biggest thing investors need to watch. Q1 operating income of ¥17.0 billion represents a substantial chunk of the company's roughly ¥49 billion full year operating income forecast, but the gaming business can be extremely back-loaded depending on the release schedule. The bigger question now is whether Square Enix can turn this quarter's momentum into a sustained trend through multiplatform releases, catalog monetization, FFXIV engagement and its upcoming pipeline
For now, the earnings report is a clear W. revenue is accelerating, margins are improving and the company's legendary IP is finally being monetized across more platforms. The stock still has bosses left to fight, but Square Enix definitely isn't playing this quarter on hard mode anymore.
I recently read Cliff Bleszinski’s book Control Freak, and it’s a great behind the scenes look at the gaming industry, creativity, and building games..If you’re into gaming or game development, I definitely recommend giving it a read  Long

Nintendo Earnings | Huge Profits, Mixed Switch 2 ResultsNintendo’s Q1 revenue for the June quarter fell 10% year over year to ¥518 billion, or roughly $3.3 billion, but still came in above expectations. Operating profit was the standout, jumping 151% to ¥143 billion, nearly twice the consensus estimate, while net income climbed 54% to ¥147 billion. However, about $300 million in refunded U.S. tariffs lowered the cost of sales, giving profitability a significant one time boost⭐
The Switch 2 sold 3.8 million units during the quarter, 34% below the original Switch’s launch-quarter sales. Even so, that puts Nintendo at 23% of its full year FY27 target of 16.5 million consoles. The Switch 2 has now reached an installed base of 23.7 million units globally, compared with 17.8 million units for the original Switch after its first year
Interestingly, the original Switch is still generating strong software sales. Software sales jumped 39% to 34 million units, far ahead of the 9.5 million Switch 2 games sold during the quarter. Tomodachi Life: Living the Dream sold 7.9 million copies, while Pokémon Pokopia reached 1.3 million. The numbers show that backward compatibility is helping Nintendo keep its massive 150M+ Switch user base engaged as players gradually move to the new hardware.
Digital sales nearly doubled to ¥133 billion and now account for 62% of total software revenue. Nintendo’s IP-related revenue also more than doubled to ¥35 billion, helped by The Super Mario Galaxy Movie, which has already crossed $1 billion at the global box office. The stronger mix of software and IP revenue helped gross margin rise 22 percentage points to 54%, although the tariff refund played a major role in that improvement
For now, Nintendo is sticking with its FY27 guidance. The company still expects to sell 16.5 million Switch 2 consoles and 60 million Switch 2 games, while targeting ¥2.05 trillion in revenue and ¥370 billion in operating profit.
The bigger test comes in September, when the Switch 2 price rises to $500 just ahead of the crucial holiday shopping season 🍄  Long

Konami Just Unlocked a New Achievement, Record ProfitsFor years Konami was treated like the final boss that gamers loved to hate
Between the departure of Hideo Kojima, the company's heavy focus on pachinko, and the long silence from beloved franchises, many players thought the studio had rage quit AAA gaming. Fast forward to 2026, and the narrative has completely changed
Konami is quietly putting together one of the strongest comeback stories in gaming while delivering record financial results that most publishers would happily speedrun
The biggest reason behind Konami's success is that it isn't relying on a single "Game of the Year" launch every few years.. Instead, it has built a diversified ecosystem of recurring revenue. Mobile hit eFootball continues to expand its global player base, surpassing one billion downloads, while YuGi Oh! remains a cash printing machine through both physical trading cards and digital games
Meanwhile, classic franchises including Metal Gear Solid Δ: Snake Eater and Silent Hill have reignited excitement among longtime fans, proving Konami's legendary IP library still has plenty of extra lives left
Revenue climbed 17.1% year over year to ¥493.7 billion, while operating profit jumped 33.3% to ¥135.9 billion. Net income reached a record ¥100 billion, up nearly 34%, marking the company's third consecutive year of record revenue and profit.. The Digital Entertainment division, which includes console, PC, mobile and card games, generated ¥371 billion in revenue, up 21.5%, with business profit surging 37.5% to ¥136 billion. Those numbers highlight just how profitable Konami's gaming business has become, especially compared to publishers that depend heavily on blockbuster launches every few years
One of Konami's biggest competitive advantages is its portfolio
Unlike publishers that live or die by one franchise, Konami earns money from multiple segments including gaming, arcade systems, casinos, sports clubs, and digital entertainment. This diversification helps smooth out earnings during weaker game release cycles. At the same time, the company owns some of gaming's most recognizable intellectual property, including Metal Gear, Silent Hill, Castlevania, YuGi Oh!, eFootball, Suikoden, and Contra. That's an inventory most publishers would happily loot
AAA game development has become increasingly expensive, and fans now expect high quality remakes rather than quick nostalgia cash grabs
Mobile gaming also remains fiercely competitive, while Chinese publishers continue to dominate global live-service games. In addition, Konami's non gaming businesses, including gaming systems and sports operations, generally grow at a much slower pace than Digital Entertainment. Investors will want to see whether the current revival of classic franchises can translate into sustainable long term growth instead of being a one time combo streak
Konami no longer looks like a company living off old save files .. It has successfully respawned as a diversified entertainment giant with record earnings, expanding live service games, evergreen card franchises, and a growing lineup of premium releases. For investors, the biggest question isn't whether Konami still has legendary IP because that's obvious.
The question is whether management can keep chaining together critical hits with new releases while maintaining the incredible profitability that has made FY2026 one of the strongest years in the company's history. If they can, this stock may still have another level to unlock
 Long
Buy Candidate: Nippon Steel Corp (Code: 5401)Idea sourced via technical screener.
NIPPON STEEL CORP. engages in the manufacture and trade of steel products. It operates through the following segments: Steel Manufacturing, Engineering, Chemicals & Materials and System Solutions. The Steel Manufacturing segment produces and distributes steel sheets, plates, bars and wire rods, pipes and tubes, and machinery parts. The Engineering segment develops steel plants, heat management facilities, and industrial machinery and equipment. The Chemicals & Materials segment produces and trades chemical products, carbon materials, epoxy resins, semiconductors, stainless-steel foils, silicon carbide wafers, carbon fibers, and metal substrates for catalytic converters. The System Solutions segment includes information technology infrastructure services. The company was founded on April 1, 1950 and is headquartered in Tokyo, Japan.
Strategy: Volume breakout from multi-month base.  Long

 Long

Buy Candidate: Otsuka Holdings Co., Ltd (Code: 4578)Idea sourced via technical screener
Otsuka Holdings Co., Ltd. engages in the management of its group companies which are in the pharmaceuticals business. It operates through the following segments: Pharmaceuticals, Nutraceuticals, Consumer Products, and Others. The Pharmaceuticals segment manufactures therapeutic drugs and infusions focusing on the central nervous system, oncology, and infectious diseases. The Nutraceuticals segment develops and markets nutrition products such as nutritional food, quasi-drugs, health drinks, and dietary supplements for homes, medical facilities, and nursing care units. The Consumer Products segment sells mineral water, food, and beverages. The Others segment distributes functional and fine chemicals, optical inspection devices, and clinical diagnosis equipment. The company was founded on July 8, 2008 and is headquartered in Tokyo, Japan.
Emerging strength below consolidation highs.
 Long

Buy Candidate: Komatsu Ltd (Code: 6301)Idea sourced via technical screener.
Komatsu Ltd. engages in the manufacture and sale of construction and mining equipment, utility devices, forest and industrial machineries. It operates through the following business segments: Construction Machinery and Vehicles, Retail Finance, Industrial Machinery, and Others. The Construction Machinery and Vehicle segment covers machineries for mining, loading, transportation, underground construction, and recycling. It also includes leveling roadbed for machinery, industrial vehicle, engine, other machineries and equipment, casting and logistics. The Retail Finance segment offers sales financing related to construction and mining machineries. The Industrial Machinery and Others segment covers forming and sheet metal machinery, machine tools, defense related, temperature controlled equipment, prefabricated house for business, and semiconductor exposure equipment for excimer laser. The company was founded by Meitaro Takeuchi on March 13, 1921 and is headquartered in Tokyo, Japan.
Strength within a consolidation range, looking to break out.  Long

 Long
 Long

 Long

 Long
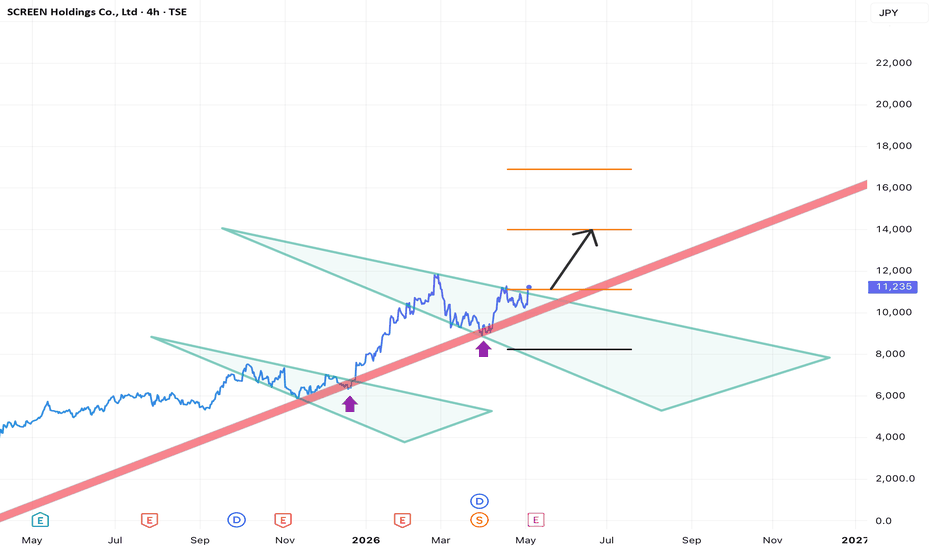
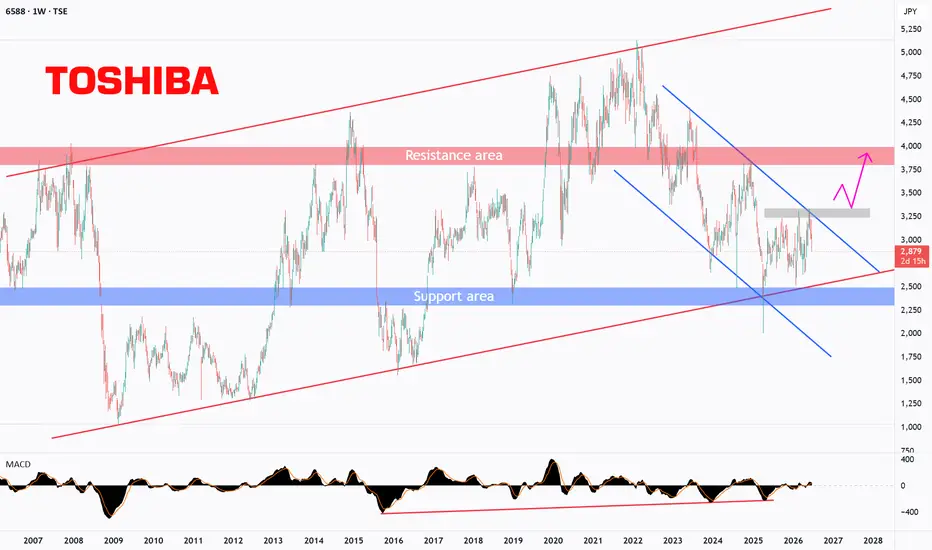
Toshiba — Corrective Phase Near Major Support !For investors with a long-term horizon, Toshiba may be an interesting stock to keep on the watchlist.
From a broader perspective, price has been respecting a large ascending red channel for many years, reflecting a long-term upward structure despite periods of correction.
At the moment, the stock appears to be moving through a corrective phase, trading inside a shorter-term descending blue channel within the broader bullish structure.
What makes the current location especially interesting is that price is now testing an important blue support area that has been respected multiple times since 2018 without a successful breakdown.
This support also aligns with the lower boundary of the broader ascending channel, creating a strong technical confluence zone.
In addition, we can observe the development of bullish divergence, suggesting that downside momentum may be weakening and that the market could be preparing for a shift in direction.
From here, two scenarios become relevant:
→ Bullish scenario:
If support continues holding and buyers regain momentum, this area may become an attractive region to monitor for the next long-term bullish phase. However, for stronger confirmation, price would ideally need to break above the selected grey area around 3350, as this could signal the beginning of a broader recovery phase.
→ Bearish scenario:
If support eventually fails to hold and the broader channel loses structure, the corrective phase may extend and delay the long-term bullish outlook.
For now, the focus is not on predicting the reversal — but on watching whether price can defend support and reclaim key resistance levels.
This is a scenario-based analysis — not a prediction.
Disclaimer: This analysis is shared for educational purposes only. It reflects personal market observations and does not constitute financial advice or a trading recommendation.
Rayan Nasser
#Toshiba #Stocks #LongTermInvesting #TechnicalAnalysis #PriceAction #Investing #StockMarket #RiskManagement  Long
 Long