Our opinion on the current state of SIBANYE-S(SSW)Sibanye (SSW) is a mining house that has been on a rapid acquisition trail, accumulating platinum and gold mines in South Africa and America. The company is now broadening its scope to include base metals and minerals, especially so-called "green" metals. The company is run by Neal Froneman, who is well-known in the mining industry for his toughness, expertise, and experience. Froneman has said that he intends to retire in about 2024/5 but plans to double the size of the company before he does.
Our opinion on the current state of ARCMITTAL(ACL)ArcelorMittal (ACL) is South Africa's largest steel-producing company. It has survived where companies like Highveld Steel have disappeared. Arguably, ArcelorMittal felt the impact of the sub-prime crisis more than any other South African company and has fallen from its high of R260 in June 2008 to as low as 25c in August 2020. Since then, it has rallied strongly and now trades at 1052c.
The company has had to deal with the collapse of the construction industry locally, which was a major consum
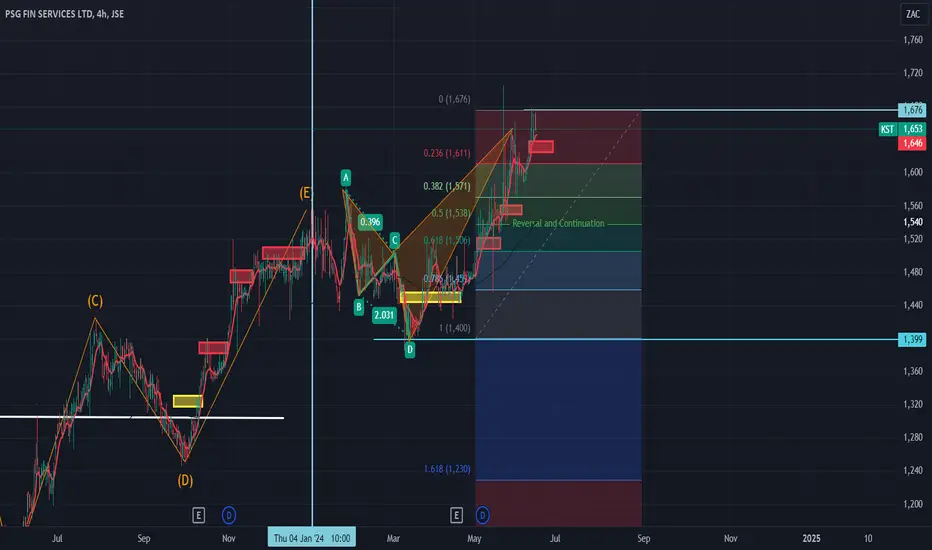
Stock correction.Looking at the recent dividend results the company's dividend yield experienced a minor drop from 2.77% to 2.76 and while the company's P/E ratio increased ( from 18.89 - 20.60) which is not a good sign from an investment perspective and looking at the trend and Elliot wave count which completed at the beginning of the year and Bat harmonic pattern completion at beginning of 2024/2025 financial year, this could be sign of a minor correction waiting to happen.
Our opinion on the current state of CONDUIT(CND)Conduit Capital (CND) is a small financial services company primarily operating in the insurance industry. It has two main divisions: Investments and Insurance & Risk. Through its subsidiary, Conduit Risk & Insurance Holdings, the company engages in underwriting, investments, and earning commissions. Conduit Capital offers a variety of niche insurance products, including medical malpractice, primary health, funeral, and life insurance, guarantee and indemnity solutions, medical evacuation, and m
C
Our opinion on the current state of CROOKES(CKS)Crookes Brothers (CKS) is an agricultural and property company formed in 1913 and listed on the JSE in 1948. The company produces sugar cane, bananas, macadamia nuts, and deciduous fruit, and has a property division. It owns Renshaw Farm, which consists of 1800 hectares between Scottburgh and Umkomaas. Of this, 266 hectares have been re-zoned for development, with 52 hectares subject to a contested land claim. The company has decided to sell the 28 hectares being developed as Renshaw Hills, a 50
Our opinion on the current state of GRINDROD(GND)Grindrod (GND) is an international freight and financial services company operating in twenty-eight countries. In mid-June 2018, Grindrod unbundled and separately listed its loss-making shipping division, Grinship (GSH). This accounts for the "cliff" in the share price at that time. The company is now focused on its two remaining divisions: freight and financial services.
Grindrod owns the North-South railway line from Beitbridge to Victoria Falls as well as port terminals at Richards Bay, Nata
Our opinion on the current state of LIGHTHCAP(LTE)Lighthouse Capital (LTE) (previously Greenbay) was one of the Resilient group of REITs (real estate investment trusts) along with Resilient itself, Rockcastle, and Fortress. These companies were the subject of a damning report by 36One Asset Management, which stated that their share prices were too high due to their cross-shareholdings. Consequently, Lighthouse's share price (after a 20-for-1 consolidation in November 2018) fell from 5420c in December 2017 to as low as 688c in February 2019.
Th
Our opinion on the current state of MARSHALL(MMP)Marshall (MMP) describes their business as follows: "Based in the UK, with strategically located offices globally, Marshall Monteagle PLC is a diversified investment holding company. The company provides procurement, logistics, and trading in various hard and soft commodities, industrial raw materials, consumer food and non-food products. Other non-operational investments include Commercial & Industrial Properties and listed equities.”
In its results for the year to 31st March 2024, the company
Our opinion on the current state of NICTUS(NCS)Nictus (NCS) is a furniture and electrical appliance retailer with three stores in South Africa. It also sells short-term insurance through Corporate Guarantee.
In its financials for the year to 31st March 2024, the company reported revenue down 5.1% and headline earnings per share (HEPS) up 67.43%. The company said, "The debtors’ book continues to decline as customers prefer to pay immediately on a cash basis. Bad debts are well below the industry norm and are well managed and supported by our
Our opinion on the current state of PBT-GROUP(PBG)PBT Group (PBG) is a fledgling IT company in the general finance sector. It has operations in South Africa and Europe, having recently exited operations in the Middle East and the rest of Africa. The company operates in data analytics, data visualisation, application development, strategic consulting, the cloud, and data platforms. The company did a 10-for-1 consolidation earlier. The group has established agreements with a number of European companies to expand its operations into Europe. Agree
P
Our opinion on the current state of RESILIENT(RES)The Resilient group of companies (Resilient, Lighthouse - previously Greenbay, Rockcastle, and Fortress) used to be the high-flyers of the property sector until the beginning of 2018 when a damning report was produced by 360ne Asset Management. The report claimed that the high prices enjoyed by the shares of these four real estate investment trusts (REIT) were primarily a result of their incestuous cross-shareholdings. This caused the price of Resilient (and the other members of the group) to pl
Our opinion on the current state of SEAM(SXM)This is a very thinly traded mining exploration company. It bought two gold projects in the DRC in 2020. In its results for the year to 28th February 2023, the company reported a headline loss per share of 143,34c compared with a loss of 141,76c in the previous period. The company has a negative net asset value (NAV) of 741,36c per share.
In its financials for the six months to 31st August 2023, the company reported zero revenue and a headline loss per share of 70,65c compared with a loss of 55
Our opinion on the current state of NAMPAK(NPK)Nampak (NPK) is Africa's largest packaging company with interests in South Africa and ten other African countries. About 60% of its turnover comes from South Africa, but only 36% of its trading profit. The rest of Africa accounts for 59% of trading profit and only 31% of turnover. The company also has small interests in the UK and Ireland. It produces four kinds of packaging products - plastics, metals, paper, and glass. The great preponderance of its trading profits come from metals - which con
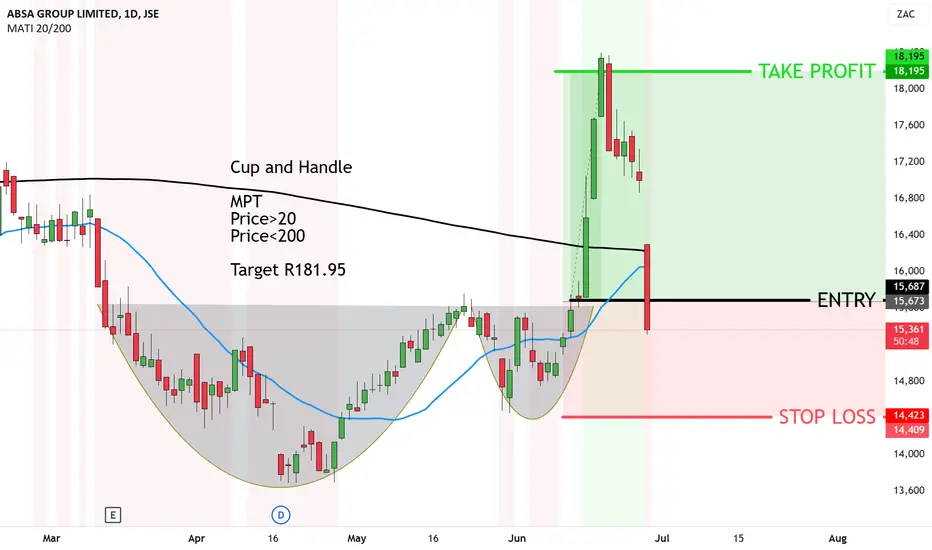
UPDATE: Absa Target reached at R181.95 what next?Cup and Handle formed on Absa, broke up and out of it.
On 12 June I said it was imminent for a breakout to the upside, but I had NO clue how fast this thing was going to rally.
And it was only a Medium Probability Trade
Price>20
Price<200
Now that the price has shot up, it obviously is silly to just buy and go long without waiting for a trend confirmation signal in my case.
But we do have a DOWN gap (Breakaway gap) that has a 70% chance of closing based on history.
However, we need so
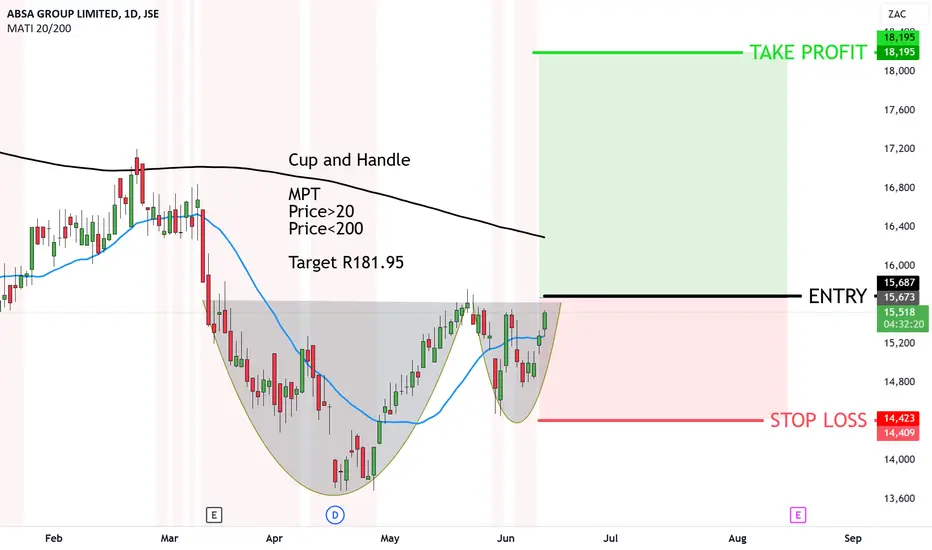
Is Absa setting itself for upside to R181.95Cup and Handle seems to be forming on Absa.
There was little supply (selling) which caused a major push up on the bank stock.
Banks have lagged many of the leading markets, and so hopefully they play catch up once the JSE TOp 40 picks up yet again.
RIght now it's in Medium Probability territory.
MPT
Price>20
Price<200
Target R181.95
🐯TIGER BRANDS🇿🇦 FORECAST Q2 FY24' : BEARS VS TIGERSOne last bullish impulse before the tank
The ranging net income over the years, with worsening free cash flow and okay 12% debt to equity for its industry tells me they arent concerned with growth right now, and the dividend yield is a good strategy but it will backfire cause its a bluff when ur fcf is not easy on the eyes
....But since 2019 the whole Industy has been taking a decline in share price as for the reason
i dont know and dont feel like investigating that far it just part of the cy
Our opinion on the current state of ATTACQ(ATT)Attacq (ATT) is a BEE level 2 property developer that converted to a real estate investment trust (REIT) in May 2018 and has been listed on the JSE since 2013. It is the owner of the Mall of Africa in Halfway House and the developer of the Waterfall City complex. It is now building the Ellipse Waterfall residential high-rise, which will have 590 apartments priced between R1.5m and R12m. Overall, Waterfall City is expected to consist of over 1 million square meters of multi-use space over the nex
Our opinion on the current state of BRAIT(BAT)Brait (BAT) is an investment holding company which owns 78% of Virgin Active, 93.7% of Premier, and 18.5% of New Look (a clothing retailer in the UK). It sold its stake in Iceland Foods for R2.4bn in June 2020 and used the proceeds to pay down debt. It is itself 46% owned by Christo Wiese's company Titan. The company's most important performance measure is its net asset value (NAV). The NAV was impacted by a change in the valuation multiple for Premier, which was reduced from 12.4 times to 11.4
Our opinion on the current state of CCCCybin is a company which focuses on the production and marketing of medical cannabis. It was listed in the Alt-X of the JSE 25th June 2024 as a special purpose acquisition company (SPAC) and plans to acquire Cilo Cybin Pharmaceutical. Cilo Cybin is to make 10% of its 71m ordinary shares available to the market - which probably means it will be very thinly traded at least to begin with. The company's CEO is Gabriel Theron.
Our opinion on the current state of EXXARO(EXX)Exxaro (EXX) is a BEE coal company with interests in iron and heavy minerals. It has interests in Australia, America, and Europe. Exxaro is a provider of coal to Eskom's Medupi power station. The company initially aimed to increase coal production from 48 million tons to about 60 million tons by 2022, but this policy might be changed due to the lower demand for coal in the global market. The price of export coal has dropped from $100 per tonne at the end of 2018 to as low as $60 per tonne.
Thi
Our opinion on the current state of KAPKAP International Holdings (KAP) is a diversified industrial company that produces and markets timber, chemicals (PET and related chemicals), bedding, and car parts. It also has a logistics division. The acquisitions of Safripol and Hosaf were integrated into a polymers business under the Safripol name. The bedding division showed strong growth with new investment in infrastructure and manufacturing capability, while growth in the automotive parts division was muted. This company was 43% owned b
Our opinion on the current state of ORIONMIN(ORN)Orion Minerals (ORN) is an Australian exploration company listed on the JSE (September 2017) and on the Australian Stock Exchange in Sydney. The company is seeking funding for its copper and zinc mine in Prieska. The Prieska mine was previously operated by Anglovaal, which ceased operations in 1990 after 20 years, having extracted more than 1 million tons of zinc and 430,000 tons of copper concentrate. A significant challenge for the mine is flooding, which requires substantial investment in pum