 LongLong

 Short
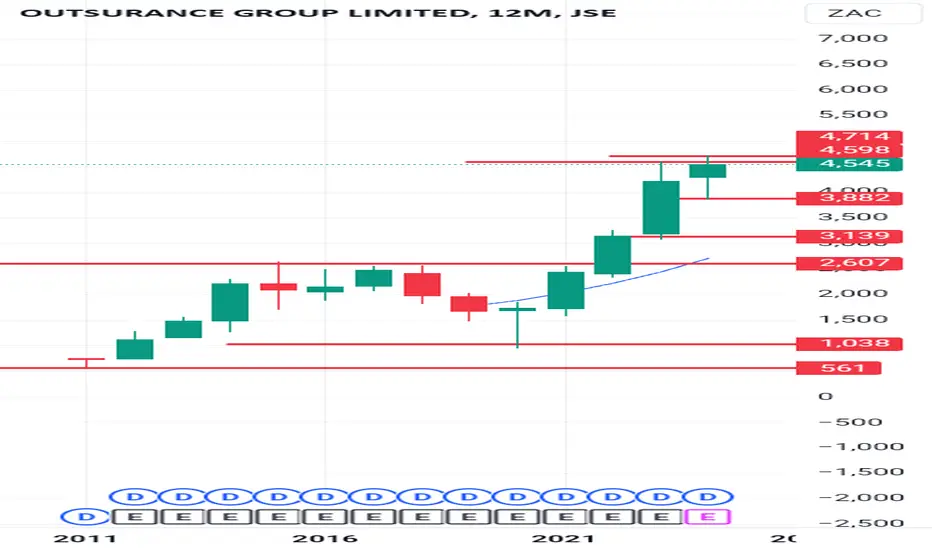
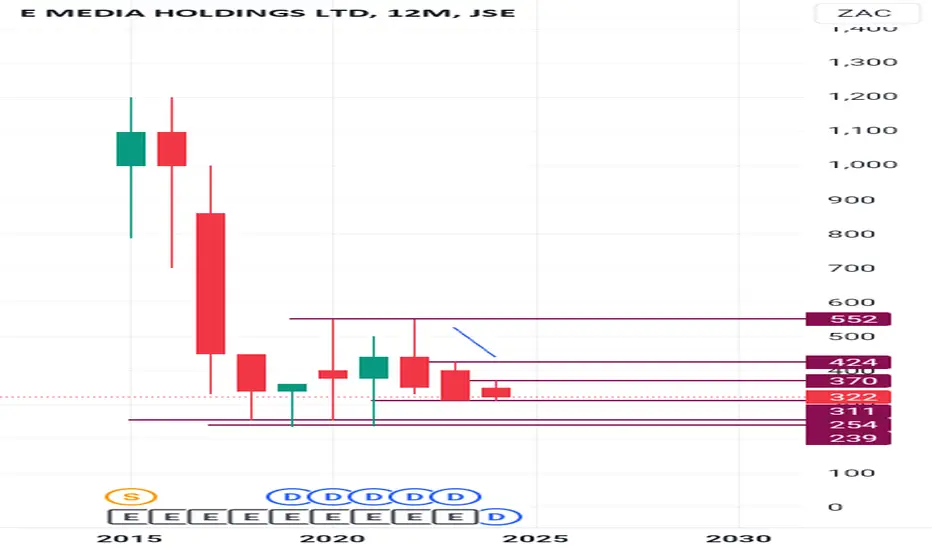
Buy ETV is good company it pays dividends give as movies all the time 📈📊🧾 I can put it in the list of my portfolio 🧾📈🏦💰💵
 Long
 Long
 Short
CLong

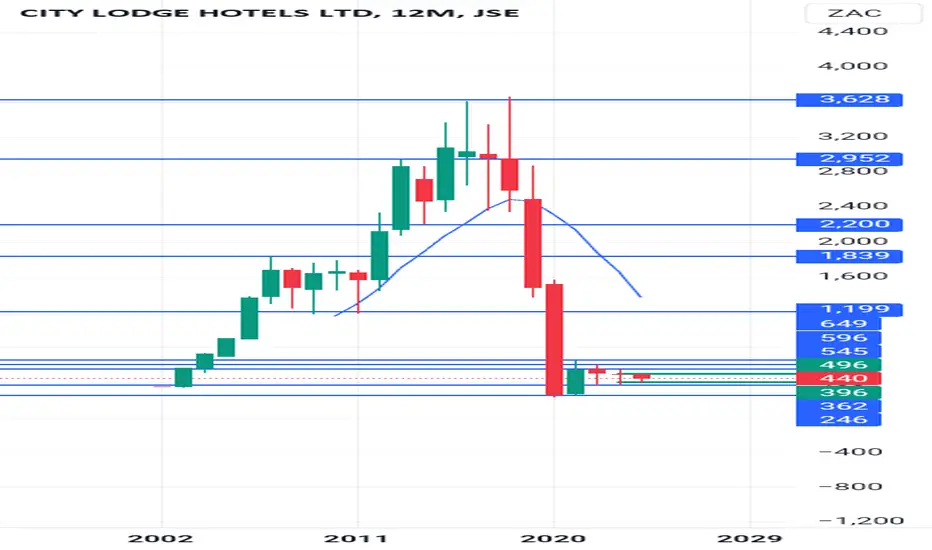
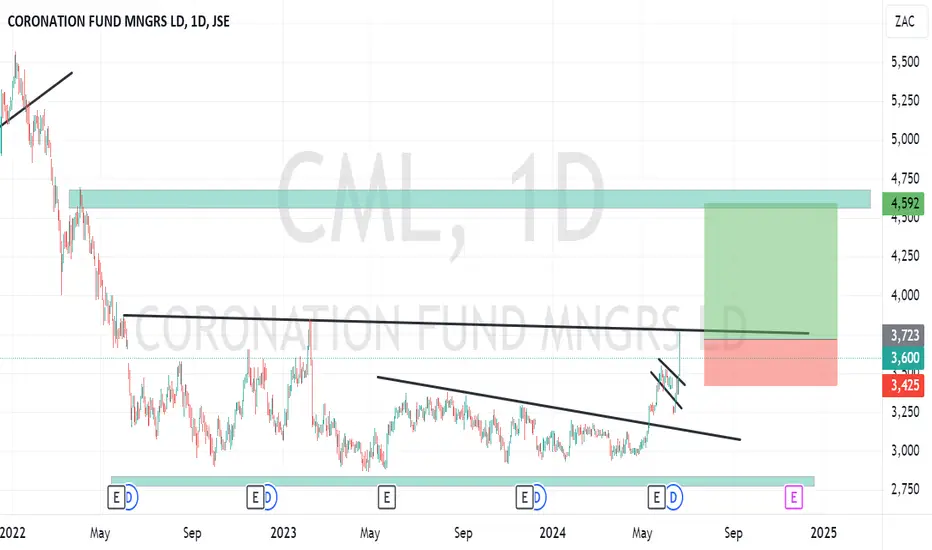
Court case against Transnet impactThe outcome of the constitutional court case against Transnet might push CML out of the range and towards 4652, especially if a special dividend is declared.
 Long
 Long

 Long

Uptrend on MERAFEPrice action exhibiting bullish trend. buy at 144 with first target as 172 and second target as 188 and stoploss of 131
 Long

$JSEVOD - Vodacom: Potential Double Bottom ReversalSee link below for previous analysis.
Vodacom selling momentum looks to have tapered as the MACD has given a strong bullish convergence pattern.
I am also on the lookout for a potential double bottom pattern between the 9070 to 8544 zone.
It is still too early to call a reversal but i will monitor price in this key price zone.


$JSEABG - ABSA: Scratch The Head & Shoulders?See link below for previous analysis.
Bulls have come in aggressively at 13683 cps and price looks impulsive, currently in the third wave.
Price did not sell-off with momentum below the neckline so there is a high probability that the head & shoulders pattern I previously forecasted has been invalidated.
My bias has turned bullish short-term as momentum is strong to the upside so buy the dips is the strategy.
 Long

$JSESLM - Sanlam: More Upside PotentialSee link below for previous analysis.
I have made a minor adjustment to the wave count with wave 3 terminating at the March high.
The stock looks to be unfolding in a five wave impulse from 6150 cps and is currently in the third wave of wave 5 of (3).
Buy the dips.
 Long

$JSETRU - Truworths: No Double Top; Stock On The Move See link below for previous analysis.
The potential double top outlook has been emphatically invalidated.
Price is tracing out a five wave impulse from 6697 cps and is currently in the third of the third wave.
Buy the dips, momentum looks strong.
 Long

$JSEDSY - Discovery: Stock Re-Discovers BullishnessSee link below for previous analysis.
Discovery stock held above the critical 10073 cps level and found support at the lower support trendline of the channel.
Price has caught a strong bid and looks to be tracing out a five wave impulse; currently the stock in the third of the third wave.
Dips will provide good buying opportunities.
 Long

Our opinion on the current state of FTBPROPB(FTB)Fairvest (FTB) is a real estate investment trust (REIT) which specializes in investing in smaller rural and non-urban shopping centers that are focused on consumers who have a lower living standard measure (LSM). It has 131 properties valued at R11,8bn. This is broken down as 67% retail, 23% office, and 10% industrial. It also owns 60,9% of Indluplace (ILU) and 5,1% of Dipula (DIB).
The company boasts that it is the top-performing REIT in South Africa with a return to investors of just under 18% for the year. In its results for the six months to 31st March 2024, the company reported revenue up 4,9% and headline earnings per share (HEPS) up 5,3% for the "A" shares and down 6,9% for the "B" shares. The loan-to-value (LTV) was 32,6% and vacancies were 5,3%. The company said, "We anticipate net property income growth, on a like-for-like basis exceeding inflation and positive renewal reversion from all sectors for the full financial year."
In a pre-close update on 19th June 2024, the company said, "Notwithstanding the tough macroeconomic and consumer environment, stubborn inflation and elevated interest rates, the South African retail portfolio has achieved like-for-like tenant turnover growth of 7,1% and maintained a low vacancy rate, by rental, of 1,3%."
Technically, the share was in a steady upward trend since April 2020 but has been moving sideways and upwards recently, especially since the latest results. Fairvest remains one of the better options in the property sector.


Our opinion on the current state of GEMFIELDS(GML)The Gemfields Group (GML) (previously Palinghurst Group) is a mining group that has two major projects: (1) Kagem, the world's largest producer of emeralds (in Zambia) and rubies (at Montepuez in Mozambique); (2) Jupiter Mines, a South African producer of manganese. The group is led by Brian Gilbertson, previously the CEO of BHP Billiton. Gilbertson identified that the semi-precious stones market was under-developed and offered an opportunity for consolidation and professional management - hence the Gemfield's operation.
Jupiter was listed on the Australian Stock Exchange (ASX) in April of 2018, and in the process, Gemfields disposed of 60% of that company in line with its decision to cease being a diversified mining company and to focus purely on gemstones. The share is fairly well-traded with approximately R0.5m worth of shares changing hands on average every day. Like all commodity shares, it is risky and its fortunes depend on the prices of emeralds and rubies on the international market, as well as the risks associated with mining in third-world countries.
It appears to have found a niche for itself where there is very limited competition, and it should do well as the world economy recovers. On 24th October 2022, the company announced that operations had resumed at MRM and key personnel had returned following an insurgent attack on a mine about 12km away on 20th October 2022. On 7th August 2023, the company announced that it would construct a new processing plant that would triple its output from the Montepuez ruby mine.
In its results for the year to 31st December 2023, the company reported revenue down 23% and a headline loss of 0,9c (US) compared with a profit of 4,8c. The company said, "The Group’s financial performance was impacted in the year by the withdrawal of November 2023’s higher-quality emerald auction and an unrealised write-down of Gemfields’ non-core 6.54% equity holding in Sedibelo Resources, the platinum group metals mining company."
Technically, the share rose off an island formation and entered a strong new upward trend which lasted until July 2023 when the trendline was broken. We recommend waiting until the downward trendline is broken - which has not yet happened. On 11th June 2024, the company announced the appointment of Bruce Cleaver as Chairman. In a report on 19th June 2024, the company said that in June 2024 auctions, it had sold $68,7m worth of rubies at an average price of $316,95 per carat.


Our opinion on the current state of LIBSTAR(LBR)Libstar (LBR) is a recently listed decentralised food and beverage company producing "consumer packaged goods." It raised R3 billion in an initial public offer (IPO) in May 2018. It owns the Denny brand, a leading mushroom supplier, and Lancewood, known for its dairy products, among other food brands. Altogether, it makes over 9000 products and has launched 88 new products in the past six months. The company produces private label brands for retailers like Spar, Woolworths, Pick 'n Pay, and Shoprite. A centralised head office supports and invests further in autonomous production units by supplying capital and expertise and making acquisitions.
The company has spent R60 million on coping with COVID-19. Consumer spending is under pressure because of load-shedding, civil unrest, retrenchments, high unemployment, the residue of COVID-19, and now developments in central Europe. This company is entirely dependent on consumer spending.
In its results for the year to 31st December 2023, the company reported revenue up 5,2% and normalised headline earnings per share (HEPS) down 11,2%. The company said, "Selling price inflation and mix changes contributed 10.0% to sales growth. Sales volume declined by 4.8% as the Group experienced a decline in its retail, industrial and export channels. Group net finance costs on interest-bearing debt (excluding IFRS 16 lease liabilities), increased by 53.3% from R109.8 million to R168.3 million, mainly due to the full period impact of the increase in the Johannesburg interbank average lending rate (JIBAR) compared to the prior period."
In a voluntary trading update on 19th June 2024, the company reported revenue up 4,6%. The company said, "Revenue growth was driven by price and mix changes of 6.3%, against a volume decline of 1.7%. Perishable Products category revenue increased by 4.4%, with selling price inflation and mix changes contributing 7.7% to sales growth. Sales volume declined by 3.3% driven mainly by lower beef volumes in the food service channel."
Libstar trades on a multiple of 8,2 and a dividend yield (DY) of 3,07%. Technically, the share has been in a downward trend for some time. We suggest waiting for a clear break above the long-term downward trendline.


Our opinion on the current state of STADIO(SDO)Stadio (SDO) is a tertiary education institution that offers a wide range of post-school training. The company provides higher education through five universities, offering higher certificates, degrees, master's, and PhD qualifications. It currently has over 46,000 students enrolled in six faculties offering more than 50 accredited training programs. Notably, 86% of these students study online. The company envisions having 100,000 students, with most expected to be distance learning students.
In its results for the year to 31st December 2023, the company reported revenue up 16% and headline earnings per share (HEPS) up 19%. The company's net asset value (NAV) increased by 1% to 212c per share. The company stated, "...despite a challenging economic environment, with good growth in student numbers for the year, specifically in new student numbers. The growth in EPS, HEPS and CHEPS is due to an increase in student numbers, coupled with good cost controls and efficiencies."
In a business update at their AGM, the company reported that student numbers increased by 8% in the year to June 2024. This was made up of 86% of students in distance learning and 14% in contact learning.
We believe that Stadio has a great future based on the general ineffectiveness of government tertiary education in South Africa. At current prices, and following their results, Stadio has broken up through its long-term downward trendline and is now on an upward trend. We are bullish on its prospects.


Our opinion on the current state of SANLAM(SLM)Sanlam (SLM) is one of the largest insurance and financial services groups in South Africa. It was established in 1918 and demutualised in 1998, subsequently listing on the JSE and the Namibian Stock Exchange. The company operates in South Africa, the UK, America, Europe, India, Australia, and a range of other African countries. Its product range includes general insurance, life insurance, asset management, banking, credit, health, and bancassurance.
The business has four essential elements:
1. Sanlam Investment Holdings (SIH) - now 25% owned by African Rainbow Capital
2. Sanlam Emerging Markets - which includes its 84.5% interest in Saham
3. Sanlam Personal Finance
4. Santam - in which it owns 61%
Outside of South Africa, Sanlam has operations in 11 other African countries and Malaysia. Saham operates in 33 French-speaking countries with 3,000 staff members across 700 branches, offering a product mix similar to Sanlam's. Sanlam also owns 26% of Shriram, a leading provider of insurance products and financial services in India. Additionally, it acquired 69% of Catalyst Fund Managers, a Cape-based manager of listed property assets, and 100% of an Irish company, CIG Fund Management.
About 50% of Sanlam's profits come from its personal finance operation primarily based in South Africa. Consequently, it is impacted by low levels of consumer spending and the economic recession in the country. Sanlam is 18% black-owned and has initiated a partnership with African Rainbow Capital (ARC) to focus on lower- and middle-income consumers and small companies. Sanlam will provide R2bn of seed capital for this initiative.
On 14th June 2021, the company announced that it had acquired the Alexander Forbes group risk and retail life business for R100m. Furthermore, Sanlam announced that, like Discovery, it would require employees to be vaccinated against COVID-19 from 2022.
In its results for the six months to 30th June 2023, the company reported the net result from financial services up 26% and headline earnings per share (HEPS) up 118%. The company said, "Cash net results from financial services increased by 30%, while net results from financial services increased by 26%. The improved performance was broad-based. Net result from financial services from our general insurance line of business increased by 38%, life insurance by 28% and credit and structuring by 36%."
In an operational update for the nine months to 30th September 2023, the company reported new business volumes up 13% and operational earnings up 35%. The company said, "The solvency position of the group remained strong and within target ranges on 30 September 2023, with a group solvency cover ratio of 170%."
In a trading statement for the year to 31st December 2023, the company estimated that HEPS would increase by between 43% and 53%. The company said, "The higher expected percentage increase in net operational earnings is due to higher investment returns on the shareholder capital portfolio." In an update on the three months to 31st March 2024, the company reported cash flow up 14% and investment returns up 15%.
Sanlam is one of the JSE's foremost blue-chip shares with a history of steady growth over a long period. After recovering somewhat from the fall in markets due to the corona pandemic, it is currently trading on a P:E of 11.86. We consider it to be good value at these levels.
In a joint announcement on 18th June 2024, Sanlam agreed to buy 60% of MultiChoice's insurance business for R1.2bn in cash.

Our opinion on the current state of SEPHAKU(SEP)Sephaku (SEP) is a construction materials business in South Africa, supplying ready-mixed cement products and cement to the construction industry. The group consists of 100% of Metier Mixed Concrete and 36% of associate company Sepcem, with the remaining 64% held by Dangote. Sephaku is directly impacted by the difficulties in the construction industry.
In its results for the six months to 30th September 2023, the company reported revenue up 19.7% and headline earnings per share (HEPS) of 7.54c compared with 11.26c in the previous period. The company said, "While the year-on-year value of residential buildings passed declined during 2023, activity on civil construction projects and non-residential buildings increased. The rising cost of essential goods and services, coupled with higher interest rates, continued to erode the disposable income of consumers, maintaining pressure on the retail market."
In a trading statement for the year to 31st March 2024, the company estimated that HEPS would be between 24.5c and 26c compared to 9.98c in the previous year. The company said, "Métier Mixed Concrete (Pty) Ltd ("Métier") and Dangote Cement SA (Pty) Ltd ("Sephaku Cement") both demonstrated resilience and agility in maintaining market share, and Métier delivered strong growth in revenue and profit."
The share was in an upward trend from July 2020 until October 2021 but has been falling and moving sideways since. It has R818,000 worth of shares changing hands on average each day, making it practical for the private investor. Although volatile, it appears to have found some support at around 85c and has begun moving up on its latest results.


Our opinion on the current state of STOR-AGE(SSS)Stor-Age (SSS) is the JSE's only real estate investment trust (REIT) specializing in buying and running domestic storage facilities in all major South African cities and in the UK. Its business is split about 60% in South Africa and 40% in the UK, with expectations that its UK business will eventually exceed the South African operations. The company owns 103 properties worth R17.3 billion.
The business of Stor-Age tends to do well in both recession and boom periods of the economy. The average client keeps their storage unit for 2 years. The client base is widely diversified and very stable from a statistical point of view. The company's foray into the UK demonstrates its ability to find appropriate properties and add them to its portfolio, also giving the share a rand-hedge element.
In its results for the year to 31st March 2024, the company reported rental income up 14.8% and a loan-to-value (LTV) of 31.4%. The company said, "Excellent strategic progress made in our JV structures during the year having opened or acquired 12 properties, representing 72,500m² GLA (SA 4; UK 8) - Third-party management agreement entered into with Hines (one of the largest privately held real estate investors and managers globally) post year-end to manage their recently acquired three-property self-storage portfolio in Kent, taking the total number of managed properties to 23 (SA 6; UK 17)."
We believe that this is one of the best property investments available on the JSE. It offers steady growth and minimal risk. Technically, the share was rising steadily until April 2022, then it began a downward trend which ended in October 2023. Now moving up again, this share represents a potential buying opportunity in our opinion. On 13th May 2024, the company announced that it had entered into a third-party agreement with Hines to manage their self-storage business in the UK.


Our opinion on the current state of TELKOM(TKG)Historically, Telkom (TKG) was the government-controlled provider of fixed-line telephone connectivity in South Africa. With the advent of cell phones, Telkom was forced to subsidize the development of its own competition in the form of Vodacom, MTN, and more recently, Cell-C. This subsidy takes the form of termination rates for calls, which are now being phased out. Over the past twenty years, the CEO of Telkom, Sipho Maseko, says that Telkom has effectively subsidized other networks to the tune of R70bn.
Telkom is currently listed and is owned 41% by the government and 11.9% by the Government Employees Pension Fund (GEPF) - so it could still be considered to be government-controlled. In reality, it operates as an independent organization divided into 5 divisions. (1) Open Serve is South Africa's primary supplier of wholesale connectivity with the country's largest network. (2) Telkom Consumer is the largest supplier of broadband internet connectivity with a growing mobile phone network. (3) Yellow Pages provides advertising and marketing to local businesses. (4) BCX is an ICT solutions company operating in Southern Africa. (5) Swiftnet was formed in April 2018 to house Telkom's masts, towers, and property interests. Swiftnet owns a diverse portfolio of 1,330 properties and has 40 earmarked for development.
Of course, Telkom is impacted by the ruling of the Independent Communications Authority of South Africa's (ICASA) decisions regarding the so-called "inter-connect" fees. However, in our opinion, Telkom has been well managed, and its downsizing should result in improved profitability going forward. This company is steadily switching from fixed-line to mobile.
On 23rd July 2021, the CEO, Sipho Maseko, announced that he would be stepping down with effect from 30th June 2022. On 22nd March 2024, the company announced that they had sold Swiftnet for R6.75bn to a consortium of investors. The cash will be used to reduce Telkom's debt.
In its results for the year to 31st March 2024, the company reported group revenue up 1.6% and headline earnings per share (HEPS) up 201.3%. The company said, "Total headline earnings per share (HEPS)1,4,7,8 and basic earnings per share (BEPS)1,3 increased by more than 100% to 376.0 cents and 385.5 cents, respectively, driven by improved operational performance. From a loss position in the prior year, profit for the year also increased by more than 100% to R1.9 billion1,3, boosted by the non-recurrence of once-off restructuring costs and lower depreciation, while higher interest rates increased net finance costs compared to the prior year."
Technically, Telkom's share fell from highs of around R98 in June 2019 to levels around R15.00 in March 2020. It has been moving sideways and down since then. The company has high debt levels compared to its market capitalization, which makes it risky for investors. In our view, this company is battling to find a new direction in a very difficult economy and against stiff competition, but the latest results are positive.

