Long
 Long
Kraken Robotics (TSX-V: PNG) - Swing TradeSwing Setup
PNG.TO
— Swing Trade Breakdown
Kraken Robotics (TSX-V: PNG) is a Canadian marine technology company developing sonar and underwater robotics systems used in defense and offshore energy. The stock has exploded off its 52-week lows, driven by strong order flow and renewed interest in small-cap defense tech. It’s now showing a clean momentum setup with defined support and resistance levels for swing traders.
📊 Fundamentals
Kraken trades at roughly 92× earnings, far above the small-cap tech average (20–30×), meaning growth expectations are already baked in. The price-to-book is around 14×, showing limited book value support.
On the positive side, ROE sits near 17% with debt-to-equity at only 0.3, so leverage is low. However, free cash flow is still negative (~-13 M CAD) and the company relies on reinvestment for growth. Cash reserves around 33 M CAD provide a liquidity cushion.
Overall, Kraken is a high-growth, high-valuation play — decent profitability but no margin for execution mistakes.
📈 Trends & Catalysts
Revenue has climbed roughly 30% YoY (to about 90 M CAD), while EPS turned modestly positive (~0.06 CAD). That growth has investors rotating into the name, but negative operating cash flow remains a concern.
Recent catalysts include:
• New contracts in sonar and subsea battery systems
• Expanding demand from naval and defense clients
• Broader rotation into small-cap tech and defense innovation plays
Main risks: valuation stretch, execution in complex defense contracts, and persistent negative FCF.
🪙 Industry Context
Marine robotics is a small but rapidly growing niche. Over the past year, PNG has surged more than 200%, massively outperforming the TSX Tech Index. Sentiment has shifted bullish after years of stagnation, and the stock remains a micro-cap momentum magnet — but prone to sharp corrections.
📐 Technical View
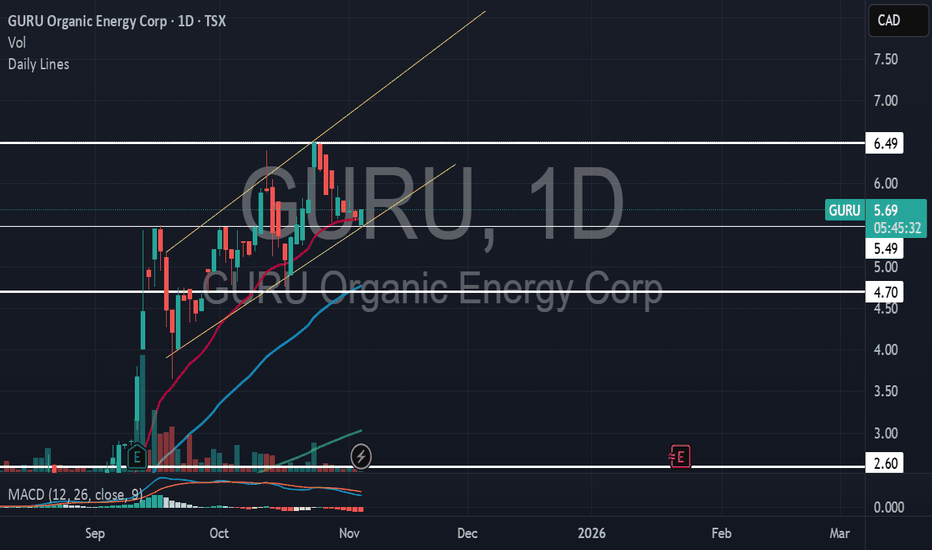
PNG is trading near 5.69 CAD, well above its 50-day SMA (~5.00) and 200-day SMA (~3.50) — confirming a strong uptrend.
Momentum cooled after a sharp run, with RSI2 at 1.94, resetting from short-term overbought conditions.
The 5.50–5.60 CAD zone is now acting as support (former breakout base), while 7.40 CAD marks the key resistance at the recent high. Volume spikes during rallies suggest institutional accumulation — but expect volatility.
🎯 Trade Plan
I’m watching for a pullback entry around 5.50–5.70 CAD, which aligns with the 20-day EMA and prior consolidation range.
Stop-loss sits near 5.00 CAD, just below structural support.
Initial target is 7.40 CAD, offering roughly a 1.2:1 R/R, extendable toward 8.00+ CAD if momentum continues.
Alternatively, a breakout above 6.70 CAD on strong volume could trigger a momentum continuation setup for active traders.
🧠 My Take
Kraken is in a confirmed uptrend with strong sector tailwinds and visible contract growth. Valuation is aggressive, but momentum remains intact. This is a high-beta swing trade, not a long-term hold — I’m looking for a disciplined entry near support or a confirmed breakout, keeping risk tight and respecting volatility.
Bias: Bullish above 5.50 CAD, targeting 7.40 CAD+
Invalidation: Close below 5.00 CAD  Long

Long 
(TSX: BITF — Bitfarms Ltd.) — Swing Trade Breakdown💰 BITF — Swing Trade Breakdown
(TSX: BITF — Bitfarms Ltd.)
🏢 Company Snapshot
Bitfarms is a Bitcoin mining and blockchain infrastructure company operating across Canada, the U.S., and South America. It’s gaining attention as crypto momentum returns and management pivots toward high-performance computing (HPC) and AI data-center infrastructure — a speculative but potentially high-growth move.
📊 Fundamentals
BITF remains a speculative play. The company is still unprofitable, so no meaningful P/E ratio applies. Debt-to-equity sits around 7.8×, which is high leverage for a volatile industry. Free cash flow remains negative due to heavy capex in new facilities. Cash reserves provide short-term flexibility, but profitability is not yet visible.
There’s no dividend, and ROE remains negative.
Summary: Fundamentally weak but improving — leveraged growth bet on the crypto/HPC narrative rather than a value play.
📈 Trends & Catalysts
Revenue grew roughly +31% YoY in 2024, while EPS losses narrowed (still negative but improving). Cash flow pressure remains, though the company continues to scale operations.
Catalysts:
• Bitcoin’s recovery and rising hash prices
• Expansion into AI and HPC data infrastructure
• Upcoming Q4 results and potential production update
• Sector-wide sentiment shift toward digital assets
Risks:
• High leverage and dilution risk
• Crypto price volatility directly impacting profitability
• Rising network difficulty squeezing margins
• Regulatory and energy cost exposure
🪙 Industry Overview
Crypto miners have rallied strongly in recent weeks. The sector is showing renewed bullish sentiment alongside BTC’s strength.
Weekly: up roughly +20%+ — short-term momentum breakout
Monthly: up ~60% — rotation into miners and AI-exposed names
12-Month: volatile, but sentiment improving as risk assets recover
Overall mood: Cautiously bullish, with traders chasing speculative beta plays like BITF.
📐 Technicals
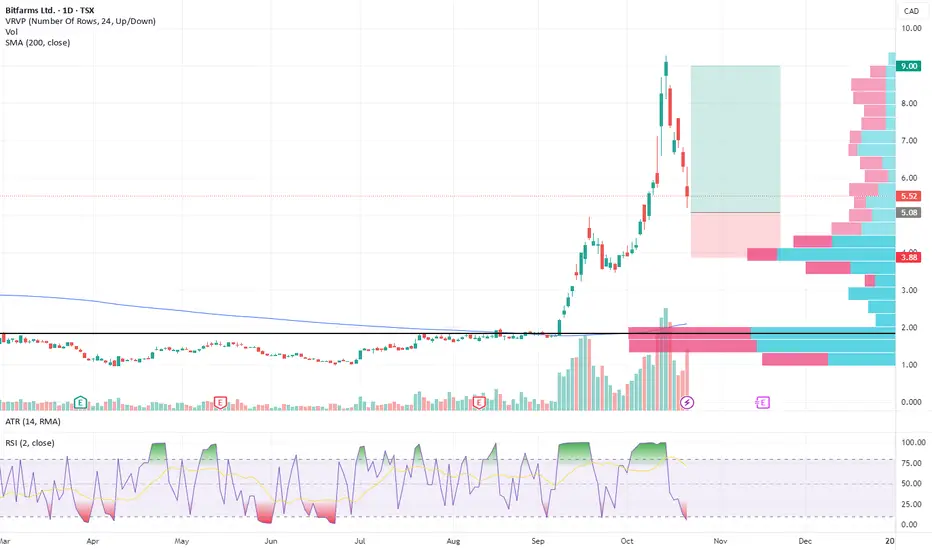
BITF is trading around $6.46, sitting above both its 50-SMA (~$6.43) and 200-SMA (~$5.33) — confirming a shift back into a short-term uptrend.
RSI(14) sits near 57, indicating neutral momentum (room to extend).
Structure: Breakout and consolidation phase after a sharp run-up.
Support lies around $5.70–$5.80, with major resistance at $8.00–$9.00 (52-week high near $9.27).
Volume has been well above average, confirming accumulation and institutional participation on the breakout.
🎯 Trade Plan
Entry Zone: $5.80 – $6.20 (retest of support or clean breakout continuation)
Stop Loss: $5.30 (below prior support)
Target: $8.00 – $9.00 (previous range top and measured move)
Risk/Reward: ~2:1 — acceptable for a momentum swing setup
Alternate Setup: Wait for a pullback to mid-$5s if BTC retraces before next leg.
🧠 My Take
BITF fits the bill for a momentum-based swing — speculative but technically strong. The stock broke out above its long-term trend, riding both crypto and AI hype cycles. If the 50-SMA holds, this could push toward the $8–$9 zone before facing real resistance.
That said, fundamentals don’t justify a long-term hold — this is a pure swing or momentum play, not an investment. Keep position size small and risk defined.  Long

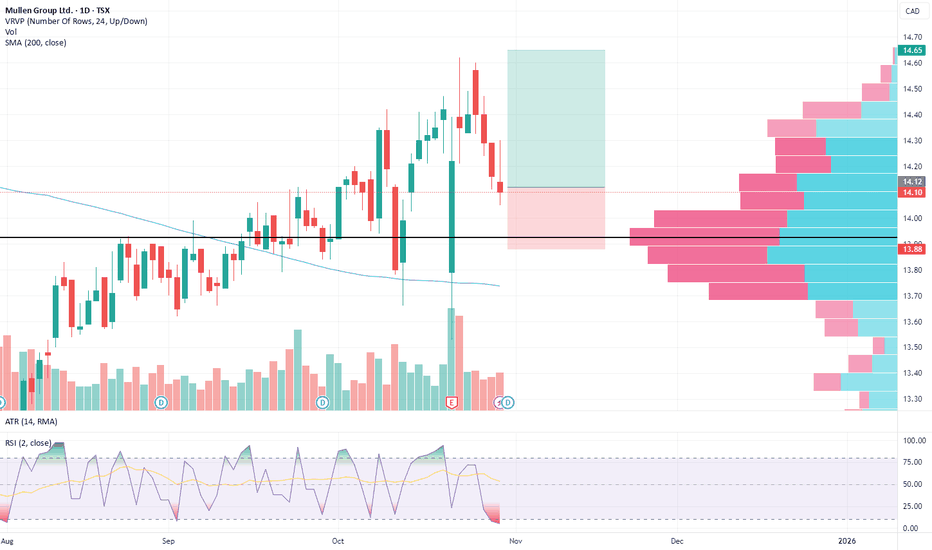
Mullen Group Ltd. (TSX: MTL) - Swing Trade💰 MTL — Swing Trade Breakdown
🏢 Company Snapshot
Mullen Group Ltd. (TSX: MTL) is a Canada-based logistics and trucking services company with operations across Canada and the U.S., covering less-than-truckload (LTL), warehousing & logistics, specialized services, and international freight. It’s attracting attention due to its moderate valuation, attractive monthly dividend, and potential swing-trade opportunity as the freight/transportation sector hints at recovery.
📊 Fundamentals
P/E: ~13.6× (slightly undervalued vs peers)
P/B: ~1.2× (modest book multiple)
Debt/Equity: ~1.17 (moderate leverage)
ROE: ~9.9% (lower than peers)
Dividend Yield: ~5.8% (appealing income component)
Free Cash Flow: Positive, modestly improving
Cash on Hand: Provides short-term flexibility
Summary: Balanced fundamentals — moderate valuation, decent dividend, but profitability is weak and debt is non-trivial.
📈 Trends & Catalysts
Revenue Growth: ~5.5% YoY
EPS Trend: Slightly declining year-over-year
Cash Flow Trend: Positive and improving
Balance Sheet: Moderate debt, adequate cash reserves
Catalysts: Potential rebound in freight demand, high dividend yield, possible growth through acquisitions
Risks: Rising fuel and regulatory costs, margin pressure, competitive market, leverage risk
🪙 Industry Overview
Weekly: Slightly down, short-term softness in freight demand
Monthly: Moderate uptrend, signals of capacity tightening
12-Month: Underperforming broader market, freight cycle correction and cost pressures
Industry commentary: Canadian trucking faces rising costs, driver shortages, and regulatory challenges, but gradual stabilization or recovery is possible.
📐 Technicals
Price: ~CAD 14.10
50-SMA: ~CAD 13.89 (current price above)
200-SMA: ~CAD 13.76 (long-term trend confirmation)
RSI(2): 4.9
Pattern: Consolidation around moving averages
Support: CAD 13.00–13.50
Resistance: CAD 15.50–16.00
Volume: Average, no breakout yet
🎯 Trade Plan
Entry Zone: CAD 13.30–14.00 (near support or pullback)
Stop Loss: CAD 12.80 (below key support)
Target: CAD 16.00 (next resistance / swing target)
Risk/Reward: ~2×
Alternate Setup: Breakout above CAD 16.00 could target CAD 18.00
🧠 My Take
MTL presents a moderate bullish swing-trade opportunity. Fundamentals are balanced with an attractive dividend, but profitability is low and debt is moderate. Technically, it’s consolidating, so I’d look for a pullback to support or a strong breakout above CAD 15.50 before entering. The 1:2 R/R swing setup is favorable if executed near key levels.  Long
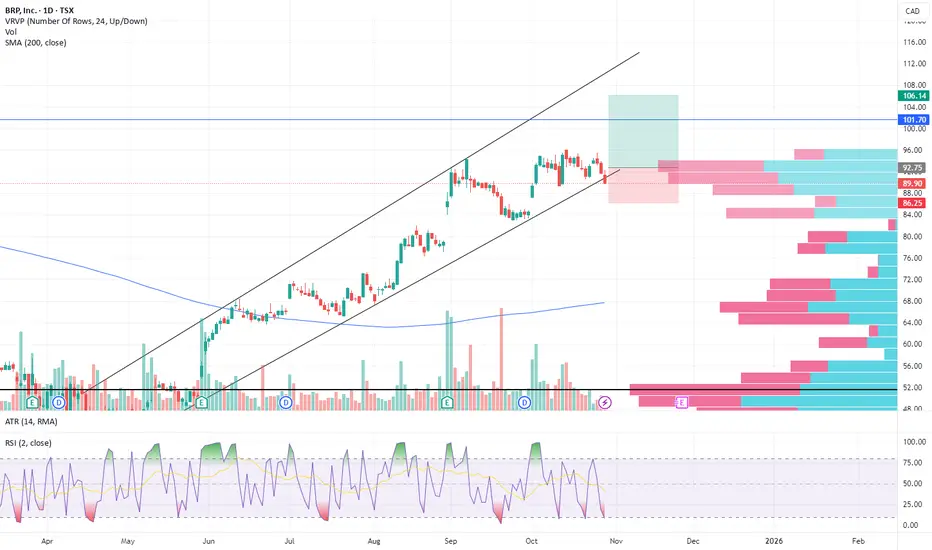
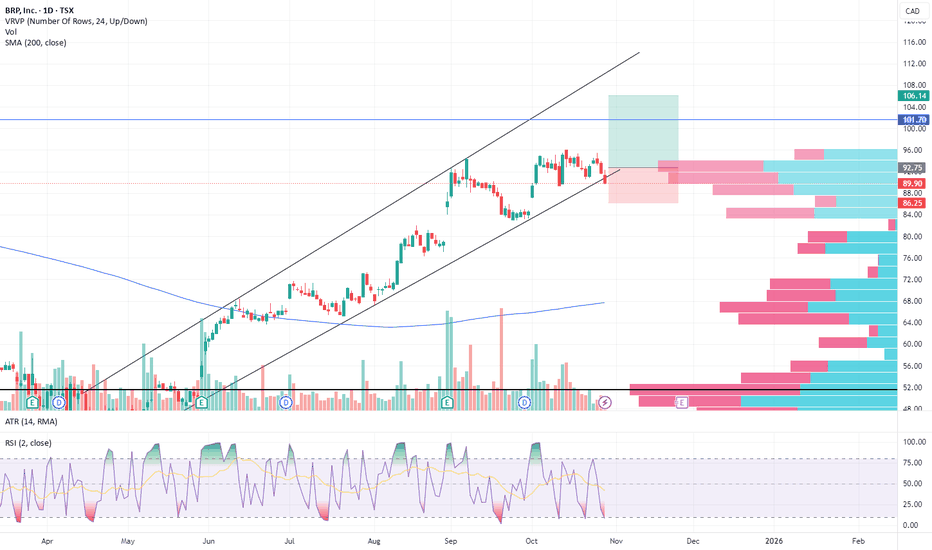
BRP Inc. (TSX: DOO) - Swing Trade
🏢 Company Snapshot
BRP Inc. (TSX: DOO) is a global powersports manufacturer behind Ski-Doo, Sea-Doo, and Can-Am. The stock recently surged from its 52-week low around C$43.88 to the mid-C$90s range, breaking a long consolidation base. Traders are eyeing it as a cyclical rebound play into winter demand, with strong seasonality and improving earnings momentum.
📊 Fundamentals Overview
DOO trades around 34× trailing earnings (≈19× forward) — elevated versus peers. Its P/B is extremely high (~14×), reflecting a premium multiple rather than intrinsic asset strength.
The Debt-to-Equity ratio (~6.2×) signals heavy leverage, though this is partly offset by strong free cash flow (~C$534 M) and C$271 M cash on hand.
ROE is negative (~-8.7%), indicating weak recent profitability, but analysts see a potential turnaround as operating cash flow remains healthy.
Dividend yield sits near 0.9%, modest and secondary to its growth profile.
Summary: High-risk, high-leverage consumer cyclical with strong free cash flow and potential for earnings recovery.
📈 Trends & Catalysts
Revenue Growth: +4.3% YoY last quarter, showing resilience amid macro headwinds.
EPS: Beat expectations last quarter (C$0.92 vs C$0.47 est.) — positive earnings momentum.
Cash Flow: Consistent operating strength supports reinvestment and debt servicing.
Balance Sheet: Debt-heavy but manageable with current FCF.
Catalysts:
Seasonal boost from winter/snowmobile sales.
Product refresh in Can-Am line.
Analyst upgrades and momentum rotation into discretionary stocks.
Risks:
High leverage amplifies downside risk if consumer spending weakens.
Valuation leaves limited margin for error.
Inventory buildup or supply chain disruptions could pressure margins.
🪙 Industry Context
Consumer leisure/discretionary names have rallied over the last month. DOO gained roughly +20–25% monthly and ~+25–30% over 12 months, outperforming peers as capital rotated back into cyclical sectors. Market sentiment is currently bullish for the space, particularly heading into the winter season.
📐 Technical Breakdown
Current price sits around C$94, well above both the 50-SMA (~C$88) and 200-SMA (~C$66) — confirming a strong uptrend.
RSI (~58) shows neutral momentum; not overbought yet, which leaves room for a continuation swing.
The chart recently broke above major resistance near C$90, now acting as support. The next resistance lies around C$96–100, aligning with the 52-week high.
Pattern-wise, this looks like a clean breakout from a multi-month base. Volume has been steady but not explosive — ideal for a pullback entry rather than a chase setup.
🎯 Trade Plan (Swing Setup)
Entry Zone: C$90–92 on a retest of breakout support.
Stop: C$84 (below recent higher-low structure).
Target: C$100–105 (measured breakout projection).
R/R Ratio: ~2.5× if entered near C$91.
Alternate Plan: Re-enter on a pullback to the 50-SMA (~C$88) if momentum cools and stabilizes.
🧠 My Take
Technically strong, fundamentally leveraged, and seasonally positioned — DOO offers a bullish swing setup for disciplined traders. The key is patience: wait for a retest into the C$90 area or confirmation above C$96 with volume expansion. Momentum and free cash flow justify upside continuation, but the balance sheet leverage demands tight stops.
Bias: Bullish above C$90, target C$100–105, invalidation below C$84.  Long
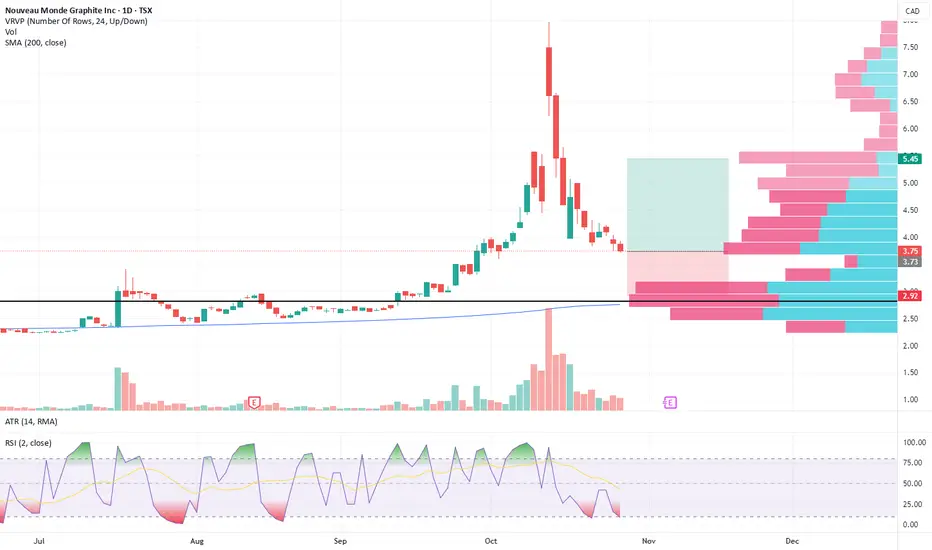
NOU(TSX: NOU) — Swing Trade💰 NOU — Swing Trade Breakdown (TSX: NOU)
🏢 Company Snapshot
Nouveau Monde Graphite Inc. is a Québec-based developer of graphite and battery-anode materials. The company’s integrated mine and battery plant strategy has put it at the center of Canada’s EV supply chain narrative. Recent price momentum follows strong interest in critical minerals and graphite demand tied to EV growth.
📊 Fundamentals
NOU remains a development-stage, pre-revenue company — not yet profitable, so traditional metrics like P/E don’t apply. The price-to-book sits around 5×, a premium to peers, suggesting investors are pricing in future production success. Debt remains low with a debt-to-equity ratio near 0.15, and the company holds roughly $73 M CAD in cash against ~$18 M CAD in debt.
However, free cash flow is deeply negative (-$70 M TTM), and ROE sits around -53%, reflecting the heavy capital burn of early-stage mine development.
Summary: Healthy balance sheet for a small-cap, but still a high-risk bet on future execution rather than current profitability.
📈 Trends & Catalysts
Revenue Growth: Minimal — still pre-production.
EPS Trend: Losses widening as project spending increases.
Cash Flow: Negative, typical for early miners.
Balance Sheet: Solid liquidity but ongoing share dilution.
Catalysts:
Final Investment Decision (FID) expected for Phase 2 mine and Bécancour plant.
Government and EV-supply-chain incentives for Canadian graphite.
Technical breakout momentum following months of accumulation.
Risks:
Execution and funding risk.
High valuation vs fundamentals.
Possible dilution if additional financing is needed.
🪙 Industry Context
Graphite and battery materials are seeing renewed strength. Over the last month, the graphite segment has rallied hard — with NOU up roughly +50% and nearly +90% YTD — outperforming broader materials. Sentiment remains bullish, though volatility is high as traders rotate through battery-related names.
📐 Technicals
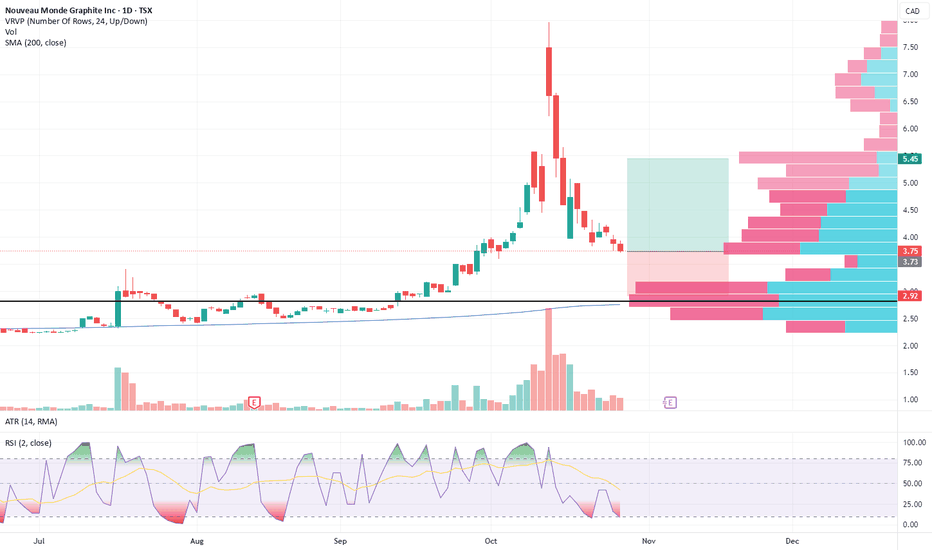
NOU recently surged from around C$2.50 to nearly C$8.00, then retraced back toward support near C$3.50–3.80, which aligns with its 50-day SMA around C$3.44. The 200-SMA sits lower near C$2.75, confirming a still-bullish long-term structure.
RSI has cooled from overbought levels (mid-60s), indicating the stock could be setting up for a secondary leg higher if demand returns.
Support is seen between C$3.30–3.50, with major resistance between C$5.50–6.60. Volume expanded sharply on the rally, then tapered during the pullback — suggesting profit-taking rather than a trend reversal.
🎯 Trade Plan
Entry Zone: C$3.50–3.80 (near support and 50-SMA)
Stop Loss: C$2.90 (below last swing low)
Target: C$6.60 (prior resistance)
Risk/Reward: ≈ 2:1
Alternate Setup: Break and close above C$5.00 with volume for a continuation move toward C$7+
🧠 My Take
This is a momentum swing on a speculative name — not a fundamental investment. I like the setup technically: clean pullback after a breakout, strong long-term trend, and supportive sector tailwind. A patient entry near the 50-SMA with a tight stop offers a solid R/R setup.
I’m watching for confirmation with volume; if it holds above C$3.50 and reclaims C$4.00, it could make another leg toward C$6+. Below C$3.30, the setup breaks down — take the loss quickly.
Bias: Bullish swing setup on retest of support within an emerging uptrend.  Long
Long 
Long 
 Long
(Apex Critical Metals Corp. | TSX: APXC) — Swing Trade 💰 APXC — Swing Trade Breakdown
(Apex Critical Metals Corp. | TSX: APXC)
🏢 Company Snapshot
Apex Critical Metals is a Canadian exploration company focused on rare earth elements (REE) and niobium, with projects in carbonatite and alkaline rock settings across Canada and the U.S. Recent acquisitions and exploration updates have sparked momentum as traders rotate into the critical minerals theme.
📊 Fundamentals
APXC is a pre-revenue explorer, so profitability metrics don’t apply. The company carries minimal debt, limited tangible book value, and negative free cash flow as it funds exploration. Market cap sits around CA$150–200 million. Like most juniors, it’s high-risk/high-reward — leverage is low, but dilution risk is high.
Summary: Early-stage speculative profile — clean balance sheet, no earnings, no dividend, pure exploration exposure.
📈 Trends & Catalysts
• Revenue Growth: N/A — still in exploration phase.
• EPS Trend: Negative — consistent losses, normal for juniors.
• Cash Flow: Declining; ongoing exploration expenses.
• Balance Sheet: Low debt, modest cash reserves — likely needs future financing.
• Catalysts:
– Upcoming exploration results and permit updates.
– Continued REE/niobium hype amid North American supply chain focus.
– Potential JV or strategic investment announcements.
• Risks: Dilution through equity raises, exploration risk, and volatile rare-earth pricing cycles.
🪙 Industry Overview
The rare-earth exploration space has been hot, with select juniors up hundreds of percent YTD. After a steep run, the group saw a 10% weekly pullback on profit-taking but remains up ~60% month-over-month and up 500%+ over 12 months. Sentiment is speculative but still constructive while commodity demand themes stay in focus.
📐 Technicals
• Current Price: CA$3.29
• 50-SMA: ≈ CA$2.50
• 200-SMA: ≈ CA$1.20
• RSI(2): 44.8 — neutral, post-pullback.
• Pattern: Breakout → consolidation; momentum cooling after a strong vertical run.
• Support: CA$2.80 – 3.00 (prior breakout area)
• Resistance: CA$4.50 – 5.00 (swing high zone)
• Volume: Well above historical averages — clear sign of accumulation earlier this month.
🎯 Trade Plan
Watching for an entry between CA$2.90–3.30, ideally on a low-volume pullback or consolidation near support.
Stop: CA$2.50–2.70 (below structural support).
Target: CA$4.50 (first major resistance).
R/R: ~2.5× potential if the setup holds.
Alternate setup — momentum continuation: a breakout above CA$4.00 on volume could confirm another leg higher.
🧠 My Take
APXC remains a high-beta, news-driven play tied to the critical minerals narrative. Technicals show a healthy consolidation after a massive speculative run, offering a possible second-leg swing if REE sentiment stays positive. I’m bullish for a short-term trade off support but keeping stops tight — failure to hold CA$2.80–3.00 would invalidate the setup and suggest momentum has dried up.  Long

Ucore Rare Metals Inc. (TSXV: UCU) — Swing Trade🏢 Company Snapshot
Ucore Rare Metals Inc. (TSXV: UCU) is a Canadian critical minerals and rare-earth developer. The company’s main focus is its RapidSX™ separation technology aimed at reducing North America’s dependence on Chinese supply chains. The stock has been attracting attention after receiving U.S. Department of Defense funding and showing extreme price momentum over the past year.
📊 Fundamentals Overview
UCU is still pre-revenue and unprofitable, trading mostly on future potential. The stock carries a high price-to-book ratio around 11×, typical for speculative juniors with strong narrative backing. Debt levels remain moderate (Debt/Equity ~0.3), and the company holds around CAD 12 M in cash, giving it limited but sufficient short-term flexibility.
However, return on equity sits around –28%, and free cash flow remains negative, so any growth will depend on external financing or new partnerships. In short, this is a high-risk development story — no earnings yet, but with significant leverage to rare-earth sector momentum.
📈 Trends & Catalysts
Revenue: none yet — development stage only.
EPS: still negative and trending lower, with ongoing R&D and expansion costs.
Cash Flow: declining due to project investments and scaling of RapidSX™.
Balance Sheet: assets up slightly, moderate liabilities, supported by grants and equity raises.
Catalysts to watch:
U.S. DoD award of ~US$18 M to fund RapidSX™ facility expansion.
Progress on supply partnerships and technology validation milestones.
Broader rare-earth sector rotation driven by geopolitical and green-energy demand themes.
Risks:
No operating revenue, potential for further dilution, and heavy reliance on future technology success. Execution and funding are key variables.
🪙 Industry Context
The rare-earth and critical-minerals sector has outperformed most materials peers over the past year thanks to Western governments’ push for supply independence. Momentum remains bullish mid-term, though volatility is high, and sentiment swings sharply with commodity headlines.
📐 Technical View
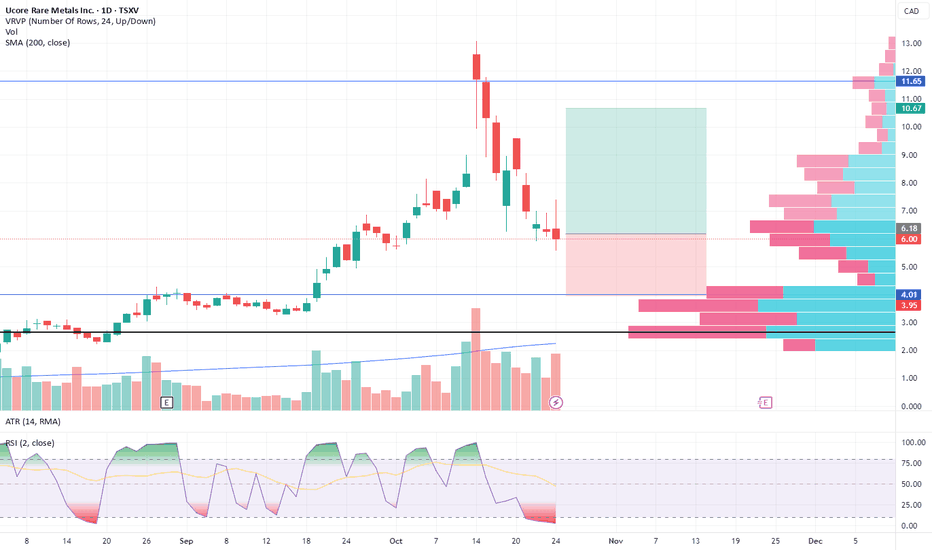
UCU closed near CAD 6.00 after a steep pullback from its 52-week high around 13.00. The 50-day SMA sits around 7.25, and the 200-day SMA near 7.00, showing short-term weakness below key trendlines. RSI around 39 suggests mild oversold conditions.
The chart shows a deep retracement after a massive run — potentially forming a base between 5.50 and 6.00. Key support lies around 5.20–5.70; resistance stands near 7.00–8.40.
If the base holds, we could see a bounce toward 8.50–9.50 in a 2:1 to 3:1 reward setup. A clean break below 5.00 invalidates the pattern and would signal a potential drop back toward 4.00.
🎯 Trade Plan
Looking for an entry near 5.50–6.00 with a tight stop just under 5.00.
Target range 8.50–9.50.
If price breaks above 7.50 with strong volume, momentum traders may take a breakout continuation setup instead.
🧠 My Take
UCU is a speculative swing setup with strong narrative backing but weak fundamentals. The recent pullback could provide a technical entry zone for traders looking to play the next leg up in the rare-earth theme. Risk management is critical here — treat it as a momentum-based play, not an investment. A rebound above the 50-SMA would confirm renewed strength and open room toward 9.00+.  Long
 Long
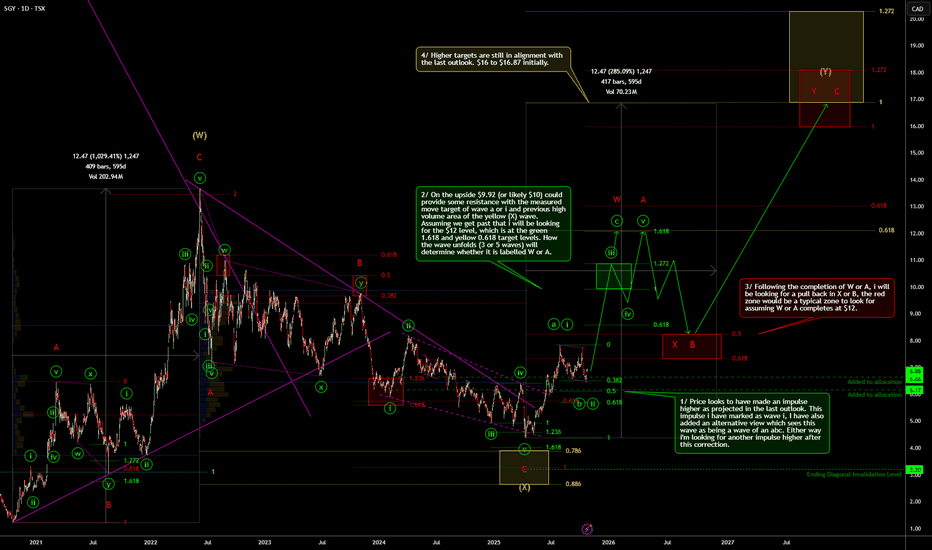
BITF — Swing Trade Breakdown (TSX: BITF)🏢 Company Snapshot
Bitfarms Ltd. (TSX: BITF) is a Canada-based bitcoin mining and compute-infrastructure operator with facilities across Canada, the U.S., Paraguay, and Argentina.
The stock has gained attention recently due to surging crypto-mining sentiment and a sharp technical breakout.
📊 Fundamentals
BITF remains loss-making, making traditional valuation metrics less reliable.
P/E: Negative (no profits yet).
P/B: Around 4.2× — elevated for a miner still unprofitable.
Cash Flow: Negative; capex-heavy operations keep pressure on liquidity.
Balance Sheet: Recently announced large convertible notes (~US$300–500M), which could add dilution and leverage risk.
Dividend: None — this is a pure speculative growth play.
💡 Summary:
High-risk, high-reward exposure to bitcoin and compute infrastructure. Valuation remains stretched given negative earnings, but sentiment and momentum could override fundamentals in the short term.
📈 Trends & Catalysts
Revenue Growth: +31.8% YoY (FY2024: US$192.9M vs US$146.4M).
EPS: Still negative but improving (-US$54.06M vs prior year).
Cash Flow: Under pressure — analysts expect negative FCF ahead.
Balance Sheet: Leverage risk rising; capital raise adds short-term liquidity but long-term dilution concerns.
Catalysts:
Rebound in bitcoin prices and hash-rate efficiency.
Progress on compute/co-location diversification.
Technical breakout momentum and broader rotation into crypto-mining stocks.
Risks:
Bitcoin downturns or energy cost spikes can crush margins.
Regulatory tightening or dilution from new financing rounds.
Execution risk in scaling data/compute infrastructure.
🪙 Industry Overview
Crypto-mining equities have been volatile, tracking bitcoin sentiment closely.
Weekly: -20% (short-term pullback).
Monthly: +60%+ rebound for BITF amid rotation into miners.
12-Month: Volatile, underperformed broader markets.
Overall: Sentiment improving, but macro risk remains high.
📐 Technicals
Price: ~CAD $5.52
50 SMA: ~CAD $3.63
200 SMA: ~CAD $2.09
RSI(2): 5.22 → deeply oversold, potential bounce setup
Pattern: Breakout toward ~$9.30 (52-week high) followed by pullback — potential bull flag or retest formation.
Support: ~$4.00
Resistance: ~$9.00
Volume: Strong recent uptick confirming trend continuation potential.
🎯 Trade Plan
Entry Zone: ~CAD $5.00
Stop Loss: ~CAD $3.85
Target Range: CAD $9.00 – $10.00
🧠 My Take
BITF offers a speculative swing setup fueled by crypto momentum and a bullish technical structure. It’s above key moving averages with strong volume confirmation, but fundamentals remain weak — this is not an investment, it’s a trade.
Use strict risk management, manage position size, and stay aware of bitcoin’s short-term price direction — it’s the main driver.
⚠️ Disclaimer:
This analysis is for educational purposes only and not financial advice. BITF is a high-volatility stock tied to crypto sentiment — trade at your own risk. Long 
Uranium Royalty Corp. (TSX: URC) - Swing Trade🏢 Company Snapshot
Uranium Royalty Corp. (TSX: URC) is a pure-play uranium royalty and streaming company that builds a portfolio of royalties, physical uranium and equity/debt exposure across Canada, the U.S., Namibia and Spain.
The attention today is being driven by renewed interest in the uranium sector and URC’s upcoming catalysts (new asset acquisitions + physical uranium build-up) even as the broader sector rotates.
📊 Fundamentals
P/E: N/A (negative earnings) — peers in uranium exploration/royalty often trade with challenging earnings metrics.
P/B: ~2.5× (book value ~CAD 2.22/share, price ~CAD 5.30)
— modest premium, reflects growth expectations.
Debt/Equity: Extremely low (~CAD 196 k debt vs ~CAD 296 M equity) — net-cash balance sheet.
ROE: Negative (~-0.69%) — company unprofitable for now.
Dividend Yield: None — focus is growth/exposure rather than income.
Summary: Balance sheet strength is good, valuation is fair but profitability lacking—speculative growth play rather than stable income.
📈 Trends & Catalysts
Revenue: CAD ~48.8 M (TTM) and net loss CAD ~-1.97 M — improving but still unprofitable.
EPS trend: Slight improvement (recent quarter positive EPS surprise) though trailing losses persist.
Balance sheet: Net cash position, growing physical uranium holdings and royalties.
Catalysts: Sector friendly (uranium price momentum); URC’s own asset acquisition/newsflow, plus upcoming earnings (~Dec.12/25) and macro rotation toward nuclear.
Risks: Unprofitable firm, relies on sector momentum; equity dilution risk (ATM program active)
Newswire
🪙 Industry Overview
Weekly: Up (recent rebound in uranium equities)
Monthly: Up, uranium names gaining relative strength
12-month trend: Up ~+25-35% for URC vs broader uranium sector
Sentiment: Bullish — nuclear/uranium theme gaining traction (but watch for tactical pullbacks)
📐 Technicals
Price ≈ CAD 5.30.
50-SMA ≈ CAD 4.92; 200-SMA ≈ CAD 3.52 — price is above both, showing medium-term uptrend.
RSI(2): 8.58.
Pattern: Recently rallied from CAD 2.00 → ~CAD 7.50 (52-week high) then pulled back — forming a consolidation zone around CAD 5.00–6.00.
Support: CAD ~5.10-5.20 (volume accumulation)
Resistance: CAD ~5.90-6.00, then CAD 6.50+
🎯 Trade Plan
Entry Zone: CAD 5.10-5.30 (on pullback to support)
Stop Loss: CAD 4.60 (below support)
Target: CAD 6.50 (initial) → CAD 7.50 (secondary)
Risk/Reward: CAD ~0.50 risk to CAD 1.20 target → ~2.4× reward
Alternate Setup: If price breaks above CAD 6.00 with volume, look for breakout continuation to CAD 7.50+, stop below CAD 5.60
🧠 My Take
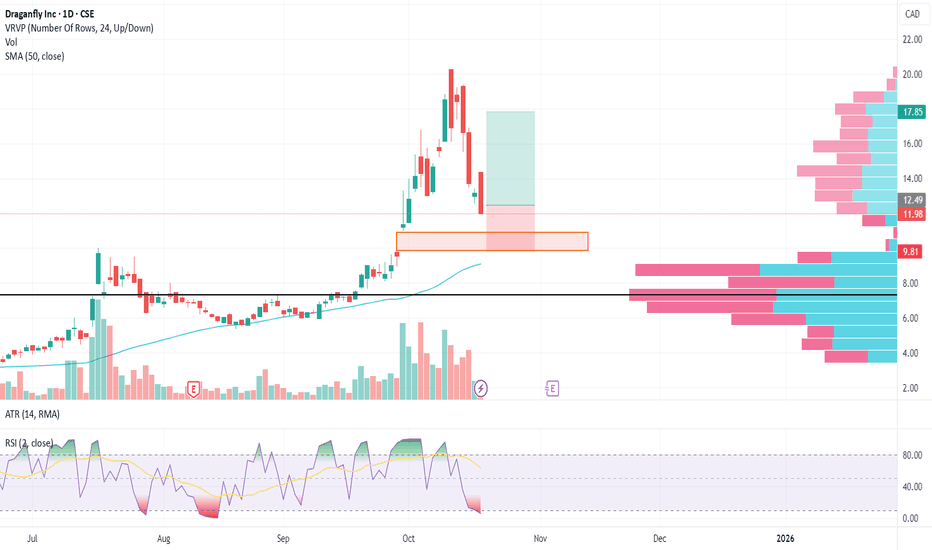
This is a high-volatility growth/sector-momentum setup more than a classic value trade. URC checks the box for a clean balance sheet and exposure to the uranium‐uptrend, and technically it’s pulled back into a support zone with a balanced risk/reward. My bias is bullish for a swing toward CAD 6.50, but only if the support holds and sector tailwinds persist — manage risk tightly given the speculative nature. Draganfly Inc. (DPRO) — Swing Trade🏢 Company Snapshot
Draganfly Inc. (Ticker: DPRO on TSX/CSE) develops and supplies unmanned aerial vehicles (drones) and associated data-analysis systems, catering to public safety, agriculture, industrial inspection and defense sectors. The thematic driver: escalating demand for Western-compliant drone platforms and recent contract news in the defense segment.
📊 Fundamentals
P/E: N/A (company is unprofitable).
P/B: ~14.7× (from one data source) versus industry norms far lower.
Debt/Equity: 0 (virtually no debt, per recent balance sheet).
ROE: negative (loss-making).
Dividend Yield: 0% (no dividend).
Summary: High valuation with minimal profitability but strong balance sheet (low debt) and speculative growth stance.
📈 Trends & Catalysts
Revenue growth: Forecast for ~ +70–80% YoY in some reports, albeit off a small base.
EPS trend: Still in the red and not yet profitable; margin pressure remains.
Balance sheet: Cash rich, debt light — gives operational flexibility.
Fintel
Catalysts: Defense-contract wins (NDAA-compliant drone supply), drone market growth, potential sector rotation into aerospace/defense.
Risks: Very high valuation, execution risk in growth, dilution potential (past funding rounds), speculative nature.
🪙 Industry Overview
Weekly: Up (recent bounce from low base) — e.g., one-month ≈ +41% per one chart.
Monthly: Up strongly (short-term momentum).
12-month: Up significantly (100%+ in one year) but from low base, highly volatile.
Sentiment: Bullish, given thematic tailwinds in drones/UAS and recent momentum, yet tempered by speculative fundamentals.
📐 Technicals
Price ≈ C$11.98
50-SMA ≈ C$9.09 (above trendline) → price well above 50-SMA, indicating strong uptrend but non-trivial pullback risk.
RSI(2): 5.88
Pattern: Strong run-up from the ~$5–6 range into ~$14, now consolidating/pulling back. Support coming into play.
Support: C$11.18 – C$10.38
Resistance: C$13.58 – C$15.18 major zone.
🎯 Trade Plan
Entry Zone: C$12.10-$12.50 (ideally on pullback into support zone)
Stop Loss: C$9.50 (below support)
Target: C$17.85
Risk/Reward: ~ 1:2
Alternate setup: If price breaks above C$15.20 with volume, consider continuation entry targeting C$18+.
🧠 My Take
DPRO offers a high-risk/high-reward swing setup: it carries a speculative valuation and remains unprofitable, but the drone/defense theme is active and price action shows momentum. The most actionable way in is via a pullback into the C$12 support zone, which affords a favorable risk/reward before the next leg higher. A break below support would invalidate the bias.  Long
UCU - Ucore's hidden potential as backbone of future economies Ucore’s Potential:
1. The Secret Link Between Ucore and **the Digital Future** - Ucore’s impact could extend into space exploration, with rare earths playing a key role in satellite and spacecraft manufacturing, also quantum computers, superfast internet infrastructure, and artificial intelligence (AI) hardware.
2. **RapidSX™ technology could disrupt global supply chains**, making Ucore a critical player in the **battle for resource independence** and flipping the script on environmentally damaging practices.
3. **Global car's-like partnerships** could solidify Ucore’s dominance in the **EV supply chain**, driving demand for its materials.
5. Strategic importance for national security - could make Ucore critical not only in clean energy but also in **defense technologies**.
Here’s why:
1. Ucore’s Rare earths elements (REE's) won’t just power EVs, wind turbines, and smartphones. They’re integral to a massive leap in digital technologies and Space Exploration we’re not even aware of yet!
- Rare earth elements are critical to the aerospace industry—from satellite manufacturing to space exploration vehicles.
- SpaceX, NASA, and other space companies rely heavily on rare earths to manufacture their spacecraft and satellites, which require high-performance magnets and motors made from rare earths. As space exploration and satellite communication increase, the demand for rare earths will skyrocket. Ucore can scale its production and provide high-quality materials, it could become a critical supplier for the space industry.
- The 5G rollout is just the beginning. Rare earths elements (REE's) play an important role in the development of **next-generation digital technology** like quantum computers, superfast internet infrastructure, and artificial intelligence (AI) hardware.
- Quantum computers rely on extremely sensitive magnets that can process vast amounts of data at exponential speeds, and rare earths elements (REE's) are at the heart of these advancements. Imagine future powered by AI, the digital economy, and next-gen internet infrastructure.
2. The Hidden Geopolitical Leverage of REE in "NEW Arms Race" and Larger Global Crisis
- The global demand for rare earths isn’t just driven by civilian uses like EVs and smartphones— military demand is increasing exponentially as well. Countries are now in an "arms race" for securing rare earths due to their critical role in defense technologies like military aircraft, robotics, naval vessels, missiles, drones and communications systems.
- Ucore’s potential to supply REE in the U.S. and Canada gives it a strategic importance that few are considering. Should tensions escalate between the U.S. and China or any other major global power, Ucore’s domestic supply could make it an essential defense asset.
- It's not "if", but "when" the U.S. successfully develops domestic sources of critical minerals like those Ucore is working on, it will disrupt China's near-monopoly, leading to geopolitical power shifts. Ucore's Bokan-Dotson Ridge project is part of a larger shift in geopolitical power grip on REE's. Ucore’s goal of processing rare earths domestically in the U.S. through its RapidSX™ technology aligns with national security interests.
- The global critical minerals shortage is a ticking time bomb. Governments are scrambling to secure access to critical resources, and companies like Ucore are positioned to play a huge role in this battle.
This is a longer-term game and Ucore will capture a slice of this market and potentially become a cornerstone player in the digital revolution, supplying the materials behind the next massive technological leap.
Long 
 Long

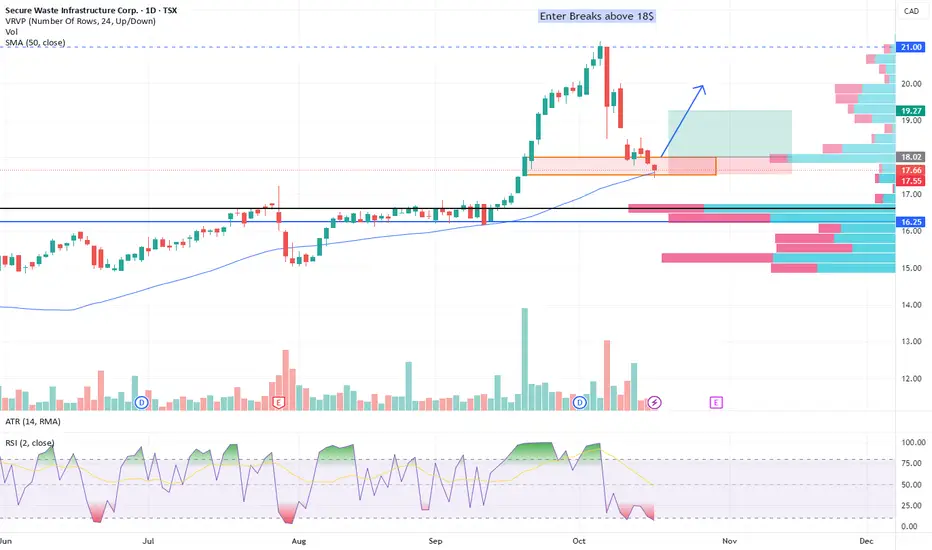
SECURE Waste Infrastructure Corp. (TSX: SES) - Swing Trade🏢 Company Snapshot
SECURE Waste Infrastructure Corp. (TSX: SES) is a Canadian waste-management and energy-infrastructure company servicing upstream oil & gas and industrial clients. It operates in waste-processing, produced-water disposal, landfills and mid-stream oil infrastructure. The company is gaining attention amid modest oil-patch recovery + steady infrastructure demand.
📊 Fundamentals
P/E: ~21× (trailing)
— modestly elevated relative to slower growth peers.
P/B: ~4.7–4.9×
— suggests market is paying for growth or operational leverage.
Debt/Equity: ~1.23×
— moderate leverage for industrial/waste‐midstream business.
ROE: ~21%
— respectable profitability given industry.
Dividend Yield: ~2.2%
— more income + growth than pure yield play.
Summary: Sound balance sheet with decent profitability; valuation shows market is pricing in growth but also some execution risk.
📈 Trends & Catalysts
Revenue growth: TTM ~ +3% on CAD 10.34 B revenue
— growth is sluggish but stable.
EPS/Profitability: Net income ~CAD 197 M, ROE ~21%
— margin remains very thin (~2% net)
Balance sheet: Debt manageable but book value modest; free-cash-flow → positive ~CAD 207 M
Catalysts: Upcoming Q3 earnings due around Oct 30 2025 ; stable oil-field service demand, waste-regulation tailwinds could help; share buy-back history and modest dividend.
Risks: Low growth environment, thin margins, leverage risk if oil-service downturn; valuation leaves less margin for error.
🪙 Industry Overview
Weekly performance: the broader industrial/waste‐infra sector in Canada has been up modestly; SES up ~+28% over last 12 months
12-month trend: SES out-performing several peers in waste/infra space.
Sentiment: Neutral / Cautiously Bullish — the business model is attractive but execution and macro dependencies (oil-services) limit upside.
📐 Technicals
Price ≈ CAD 17.70–18.00.
50-SMA ≈ ~17.40, 200-SMA ≈ ~15.50.
Price sits just above its 50 SMA, above 200 SMA — indicating medium-term support is intact.
RSI(2): 7.16 —oversold (Signal for STrategy)
Pattern: The stock has consolidated between ~15.30-18.50 for several weeks; recent breakout attempt into upper range.
Support: CAD 15.30–16.60.
Resistance: CAD 18.10–18.50 zone (52-week high ~21.15)
🎯 Trade Plan
Entry Zone: CAD 16.60–17.20 on pullback to support or breakout above 18.00.
Stop Loss: CAD 15.20 (clear break of support).
Target: CAD 19.50 (initial) → CAD 21.00 (extended)
Risk/Reward: ~2.5× at initial target
Alternate Setup: If breakout above ~18.00 with volume, enter at 18.10–18.30 with stop ~17.45 and target ~21.00.
🧠 My Take
This is a moderate bullish swing setup. SES offers a structurally solid business with steady cash flow, reasonable profitability and a supportive technical base. The key is entering near support or on a clean breakout with volume. With risk defined and reward decent, it's suitable for a 1–10 day swing trade — but given the modest growth backdrop, patience and disciplined stop management are crucial.  Long