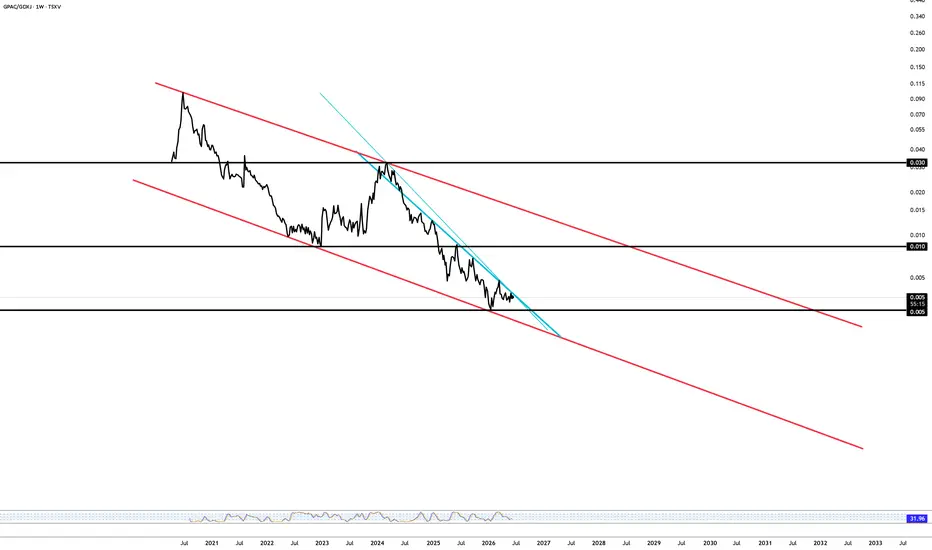
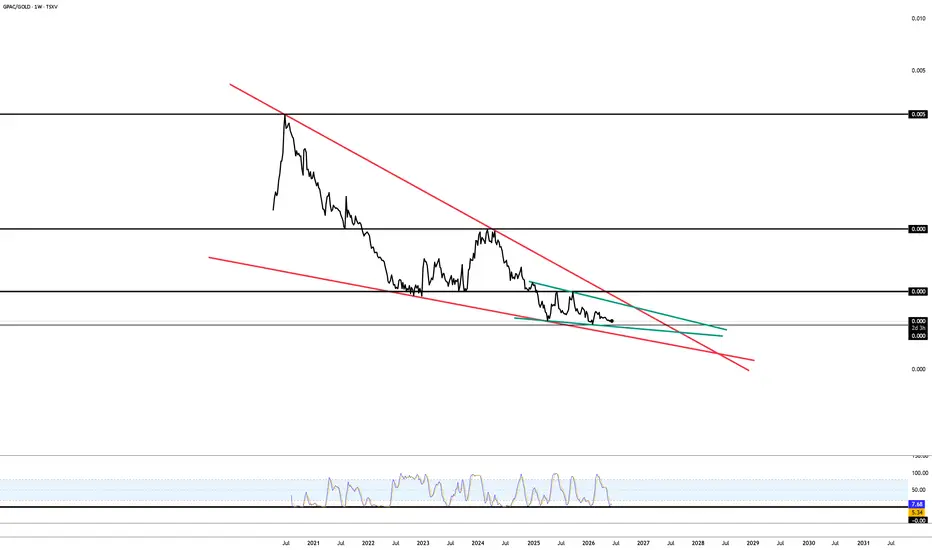
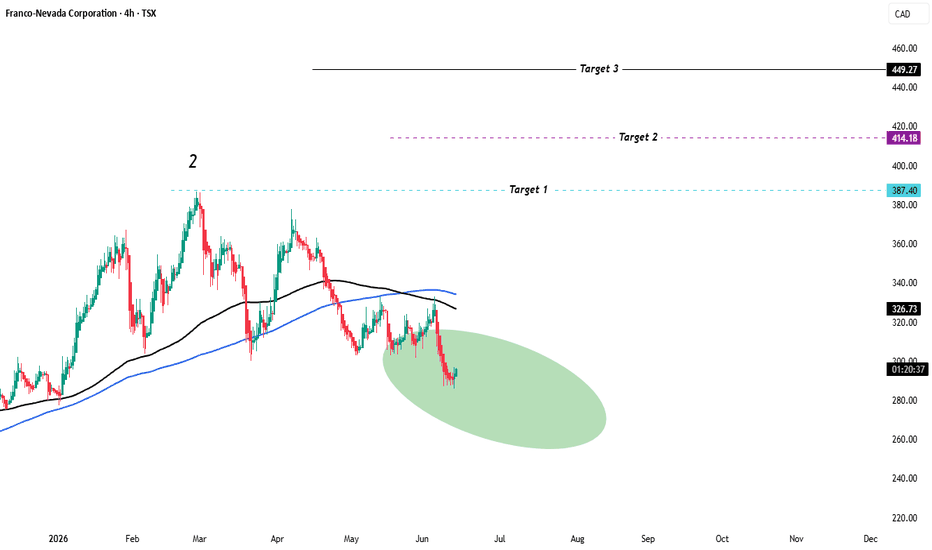
Wheaton Precious Metals CorpWheaton Precious Metals Corp. is one of the largest precious-metals streaming companies in the world, generating revenue primarily through long-term agreements that provide exposure to gold and silver production from mining operators. Unlike traditional miners, the company generally avoids many direct operating and development risks associated with mine ownership, allowing it to maintain a relatively asset-light business model with strong cash-flow characteristics.
From a strategic perspective, Wheaton's business is closely linked to long-term trends in precious-metals prices, inflation expectations, monetary policy, and investor demand for defensive assets. As a result, the company may benefit during periods of economic uncertainty, currency debasement concerns, or increased demand for portfolio diversification.
Looking at the technical landscape, the higher-timeframe structure remains constructive and continues to support a favorable long-term outlook. The broader pattern suggests that the stock may be building a foundation for continued upside development and potentially higher valuation levels over time. However, despite the encouraging long-term structure, lower-timeframe confirmation signals are not yet fully established.
As emphasized in previous analyses, patience and confirmation may provide a more disciplined approach than attempting to anticipate the next move. Investors may prefer to wait for stronger buyer participation and improved trend alignment on lower timeframes. One commonly monitored signal is the 200-period moving average shifting beneath current price action, which may indicate strengthening momentum and increasing buyer control.
From a fundamental perspective, several areas may deserve ongoing attention:
• Revenue growth trends and sensitivity to precious-metals prices
• Operating cash-flow generation and earnings quality
• Free Cash Flow to Firm (FCFF) and Free Cash Flow to Equity (FCFE)
• Growth or decline in Earnings Per Share (EPS) over multiple business cycles
• Capital allocation discipline and balance-sheet strength
• Diversification and quality of streaming agreements
Investors may also evaluate whether:
• Revenue growth is translating into sustainable earnings growth
• Cash-flow generation is supporting shareholder value creation
• Operating costs remain controlled relative to industry peers
• Long-term contracts continue to provide competitive advantages
To estimate a reasonable intrinsic value range, fundamental tools such as Discounted Cash Flow (DCF) analysis, Dividend Discount Models (DDM), Gordon Growth Model (GGM), and cash-flow-based valuation frameworks may complement technical analysis and improve investment decision-making.
While the long-term outlook appears constructive, disciplined risk management, portfolio allocation limits, and confirmation-based entries remain essential. Technical analysis may assist with timing, while fundamental analysis helps determine whether the underlying business justifies long-term capital commitment.
This analysis reflects a personal interpretation of market structure and publicly available information. It is intended solely for educational and informational purposes and should not be considered financial advice or a recommendation to buy or sell any security. Independent research, valuation analysis, and prudent risk management remain essential before making any investment decision.
 Long
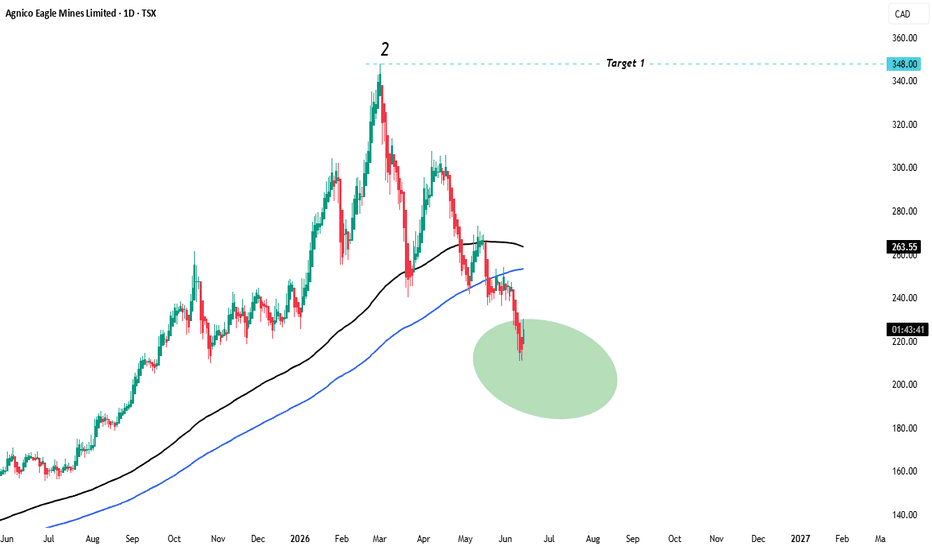
Agnico Eagle Mines LimitedAgnico Eagle Mines Limited is one of the leading gold mining companies in North America, with operations concentrated in politically stable mining jurisdictions. As a precious-metals producer, the company is influenced by gold prices, production efficiency, reserve quality, and cost management. Its performance can also benefit during periods of economic uncertainty when investors seek exposure to defensive or inflation-sensitive assets.
From a long-term technical perspective, the higher-timeframe structure appears increasingly constructive. The broader pattern continues to suggest the possibility of an extended bullish phase, and the overall chart structure may support a future challenge of historical highs and potentially new price-discovery levels. However, despite the encouraging higher-timeframe outlook, lower-timeframe confirmation remains incomplete.
At present, the preferred approach may be patience rather than anticipation. Clear evidence of buyer participation on lower timeframes has yet to fully develop. As discussed in previous analyses, one of the simplest confirmation signals to monitor is the 200-period moving average transitioning beneath price action, accompanied by improving bullish market structure and momentum alignment.
In addition to technical observations, investors may benefit from reviewing several fundamental drivers:
• Revenue trends and their relationship to gold-price movements
• Production growth and reserve replacement quality
• Cost discipline, including operating and all-in sustaining costs (AISC)
• Earnings per Share (EPS) growth consistency
• Free Cash Flow generation (FCFF and FCFE)
• Balance-sheet strength and capital allocation efficiency
Particular attention may be given to whether:
• Revenue is expanding faster than operating costs
• Cost inflation is being effectively managed
• EPS growth is supported by operational improvements rather than temporary factors
• Cash-flow generation remains sustainable across commodity-price cycles
For valuation purposes, investors may also consider:
• Discounted Cash Flow (DCF) analysis
• Dividend Discount Models where applicable
• Gordon Growth Model (GGM) assumptions
• Relative valuation metrics compared with peers in the gold-mining sector
The combination of technical analysis for timing and fundamental analysis for business quality and intrinsic value estimation may provide a more comprehensive framework for long-term investment decisions. While the higher-timeframe structure remains promising, disciplined risk management, position sizing, and confirmation-based execution remain essential.
This analysis reflects a personal interpretation of market structure and publicly available information. It is intended solely for educational and informational purposes and should not be considered financial advice or a recommendation to buy or sell any security. Independent research, valuation assessment, and prudent risk management remain essential before making any investment decision.
 Long
 Long
 Long

 Long
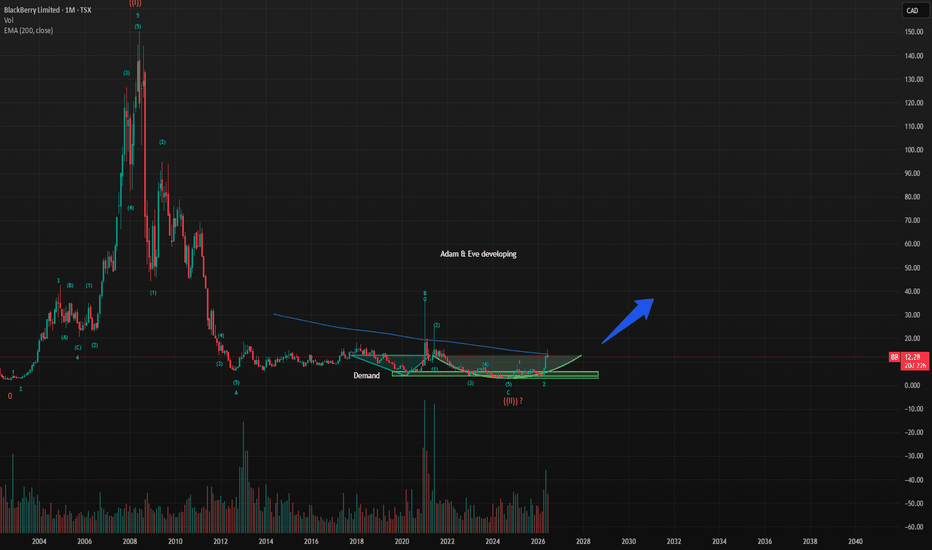
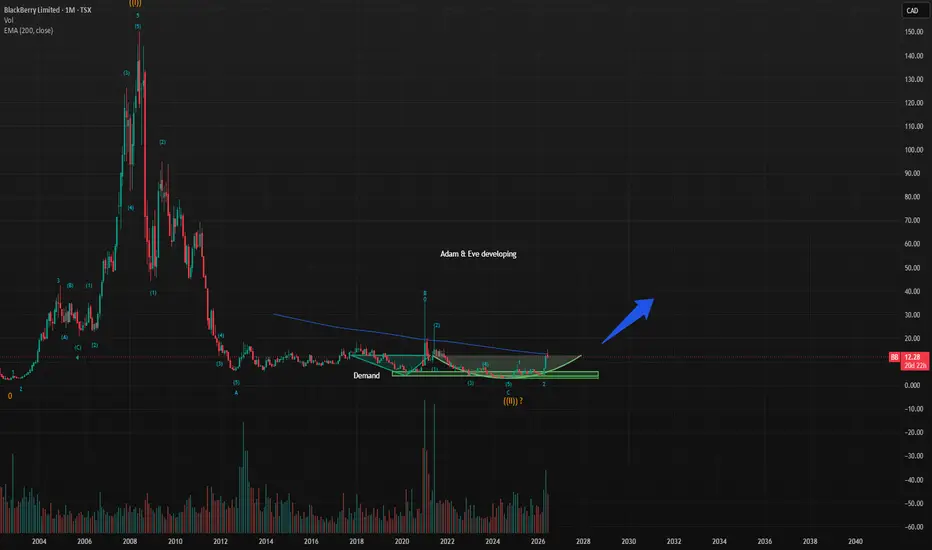
Largo Inc. (LGO) – A High-Risk Bet on a Vanadium RecoveryThe chart does not look bullish yet. The stock remains in a long-term downtrend and the company continues to report losses.
However, the reason I am watching Largo is not because of its current earnings. It is because of where the company sits within the vanadium cycle.
Largo is one of the largest and highest-grade vanadium producers outside China and Russial. The company is essentially a leveraged play on vanadium prices. When vanadium prices are weak, Largo struggles. When vanadium prices recover, operating leverage can work dramatically in the other direction.
That is why I believe the commodity itself is currently more important than the latest quarterly loss.
After a prolonged decline, vanadium prices appear to be stabilizing and showing signs that the bottom may be behind us. The market has spent years pricing in oversupply, weak steel demand and disappointing battery adoption. Today, expectations are extremely low. Historically, those are often the conditions from which commodity recoveries begin.
What makes the setup interesting is that the stock is already trading as if very little will improve.
Price/Sales (TTM): 0.64
That is an exceptionally low valuation for a company controlling a strategic mineral asset. The market is effectively saying that either vanadium remains depressed for years or that Largo will fail to generate attractive returns even if prices improve.
I am not convinced that pessimistic scenario is guaranteed.
Management has outlined a multi-year strategy focused on operational improvements, production stability, cost discipline and positioning the company to benefit from future vanadium demand growth. The long-term investment case is not limited to steel production. Vanadium remains a critical material for aerospace, industrial alloys, defense applications and potentially for large-scale energy storage through vanadium redox flow batteries.
The battery story has disappointed investors for years, but it has not disappeared. Any meaningful increase in adoption could have a significant impact on future vanadium demand.
Technically, the stock is approaching a major support and accumulation zone that has been tested multiple times. Volume has started to increase around these levels and RSI is sitting near historically depressed territory. The trend is still down, so I am not calling a bottom. But from a risk/reward perspective, the setup is becoming more interesting than it was six or twelve months ago.
The key question is simple:
Has vanadium already bottomed?
If the answer is no, Largo may continue to struggle and the stock could remain trapped in a downtrend.
If the answer is yes, and vanadium is entering a new cycle higher, then the market may be significantly underestimating Largo's future earnings power.
This is not a quality compounder. This is not a safe investment.
It is a cyclical turnaround opportunity tied directly to the future direction of vanadium prices.
For investors willing to accept commodity-cycle risk, Largo may be one of the more interesting speculative setups in the sector today. Short 
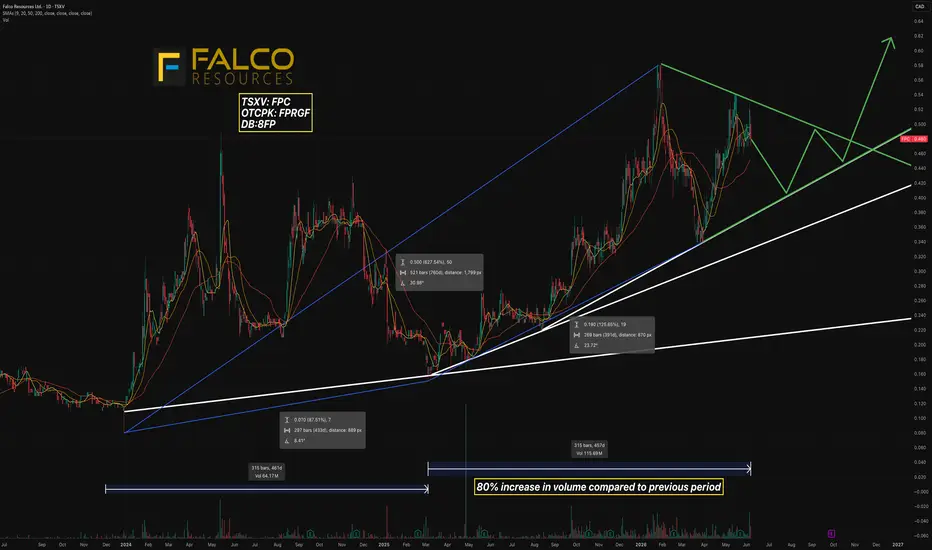
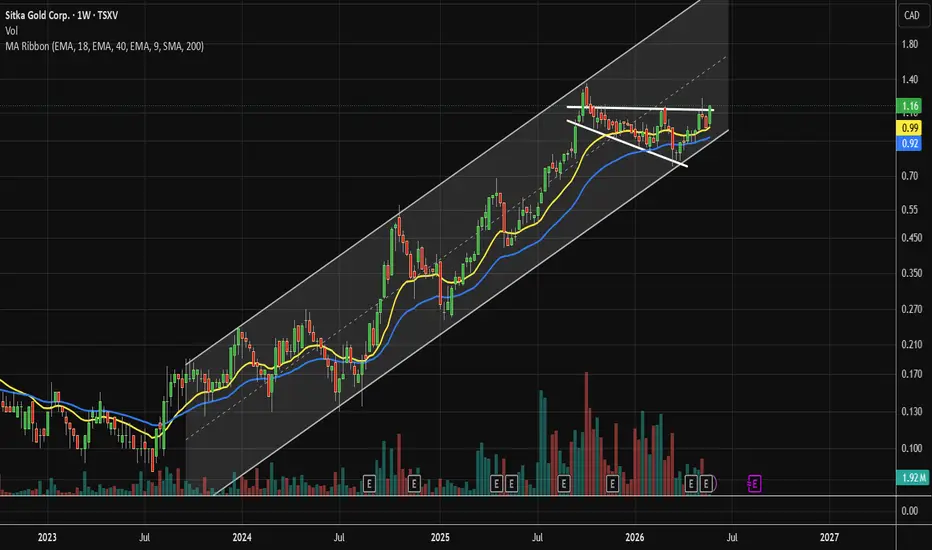
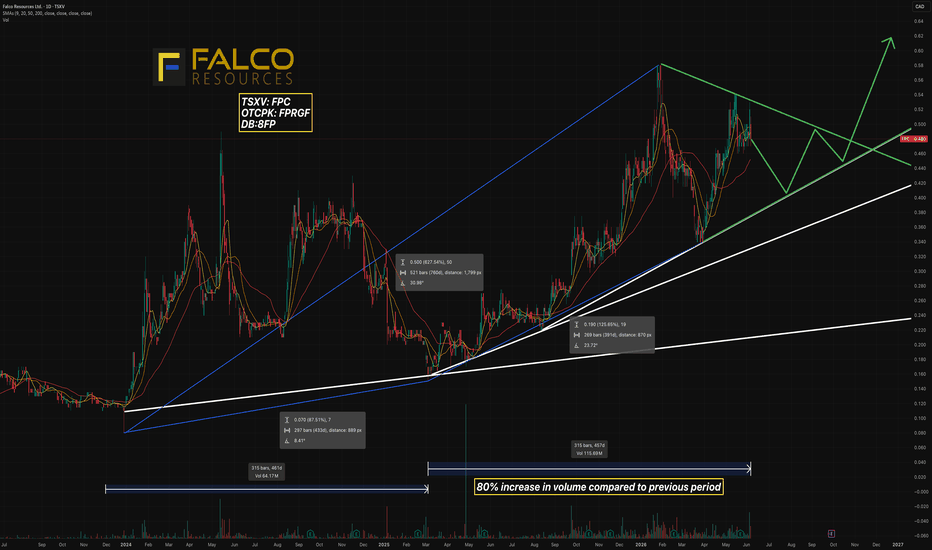
Falco Resources (TSXV) | Volume Expansion + Pennant SetupTSXV:FPC
One of the more interesting junior mining charts developing right now.
After a multi-year accumulation phase, FPC has constructed a clear bullish fan pattern. Each successive trendline break has resulted in a steeper rate of ascent, signaling increasing demand and strengthening market participation.
What's particularly notable is the volume profile.
The current advance has generated approximately 116M shares traded versus roughly 65M shares during the previous comparable period — an increase of nearly 80% . Rising volume accompanying a rising trend is often a sign that institutional and speculative interest is beginning to build beneath the surface.
Price is now compressing between a rising support trendline and declining resistance, creating the framework for a potential bullish pennant . The pattern is not yet complete, but continued consolidation above the rising trendline could set up a breakout attempt in the months ahead.
From a measured move perspective, a breakout from the pennant would project toward the $0.60-$0.65 range, representing the next major resistance zone.
Fundamentally, several catalysts could align with the technical structure:
• Horne 5 continues advancing toward the Québec ministerial decree, one of the most significant permitting milestones for the project.
• Updated feasibility study expected in 2026, incorporating substantially higher gold, copper, silver and zinc prices than the 2021 study.
• Horne 5 remains one of Canada's most advanced undeveloped polymetallic deposits, with projected annual production exceeding 220,000 ounces of gold alongside significant copper and zinc exposure.
• Falco recently identified multiple new exploration targets across the Western Noranda Camp, adding district-scale exploration upside beyond the flagship project.
• Detailed engineering, procurement work, and project advancement continue while the company moves toward potential development decisions.
The chart remains constructive as long as the rising support structure remains intact. A confirmed pennant breakout combined with continued fundamental progress could attract significantly more attention to the story.  Long
$ELD the golden diamond(s)the most significant sum of $ i've put into a single stock was OMXCOP:FOM Foran Mining.
now apart of Eldorado. however the deal went down, the new analysis on the consolidated assets looks like, as Claude put it:
Sum-of-the-parts NAV (after-tax NPV5%, base deck $3,800 Au / $5.00 Cu) $B $/sh
Operating mines (Lamaque, Kisladag, Efemcukuru, Olympias) $5.5b $21
Skouries (100%, gold-copper) $4.5b $17
McIlvenna Bay (100%, copper-zinc-gold-silver) $1.4b $5
Tesla Zone + exploration (risked optionality) $0.5b $2
Pipeline (Perama Hill, Sapes, Stratoni) net of corporate $0.2b $1
Less: net debt −$1.0b −$4
Net asset value $11.1b $42
Current price / implied P/NAV (base deck) $8.8b $33.5 = 0.79x
NAV at spot gold (~$4,450) / implied P/NAV ~$14.2b ~$54 = 0.62x
The thesis is an EBITDA inflection the market isn’t paying for. Eldorado earns ~$1.7b EBITDA in 2026, but Skouries (first concentrate Q3’26, ~140koz Au + 67Mlb Cu/yr at negative AISC) and McIlvenna Bay (commercial Q3’26) roughly double EBITDA to ~$2.8b in 2027 and lift gold output ~40% — the bull rail’s +78% jump in ’27 is that step-change. Reverse-DCF: at $33.5 the EV (~$9.8b, incl. ~$1.0b net debt) implies only ~$1.7b of EBITDA held flat (purple row) — essentially the 2026 trough — so the market gives ~zero credit for the ramp; if 2027 EBITDA lands near base, the same ~5.5x multiple alone re-rates the stock toward the high-$50s. SOTP cross-check (table above): NAV ~$42/sh at a $3,800 base deck (~0.80x), ~$54 at spot gold (~0.62x) — versus the peer ~0.81x P/NAV Eldorado historically traded below. Base FV builds to ~$87 (+10%/yr) as the projects de-risk and FCF (−$0.3b in ’26 → ~$1.8–2.0b/yr) delevers to net cash and funds buybacks; bull ~$180, weighted ~$111. Devil’s advocate: this is a leveraged bet on the gold price — the bear rail (gold fades to ~$2,800) leaves the stock ~flat ($36), and a sharper gold correction would hurt more; Skouries has a history of delays (already slipped a quarter, capital crept to $1.315b) and is only at first-concentrate, not steady-state; the Foran deal diluted existing holders ~24% with nil premium and bolts a copper-zinc VHMS (a metallurgy/jurisdiction ELD has never operated) onto a gold company mid-Skouries-ramp; Kisladag and Efemcukuru sit in Turkiye (FX, inflation, royalty risk); and the out-year net-cash build assumes high metal prices hold. Blue-sky “what has to be true”: the Tesla Zone’s maiden resource (H2’26, 28–45Mt exploration target on existing infrastructure) plus district exploration adds a third growth leg, McIlvenna scales beyond the initial mill, and gold holds $4,500+/copper $6.50+ — turning a two-project re-rate into a multi-decade gold-copper franchise (blue rail ~$289).
Engine: Fair value = forward Adj EBITDA × EV/EBITDA − net debt, ÷ shares, for four scenarios, cross-checked to a sum-of-the-parts after-tax NAV. Foran Mining acquired Apr 14, 2026 (all-share, 0.1128 ELD + C$0.01/Foran share, ~C$3.8B / ~US$2.8B; Foran holders ~24% of the combined company; ~62M shares issued → ~262M total), adding McIlvenna Bay + the Tesla Zone. Q1'26: 100,358 oz gold, revenue $532M, adj EBITDA $336M, adj EPS $0.95, cash $630M, total debt ~$1.3B, FCF −$129M (Skouries capex). 2026 guidance 490–590koz gold, AISC $1,670–1,870/oz; Skouries first concentrate Q3'26, commercial Q4'26 (94% built, total Phase 2 capital $1.315B), ~140koz Au + 67Mlb Cu/yr LOM at negative AISC; McIlvenna commercial Q3'26 (~41Mlb Cu + 20koz Au + 444koz Ag + 54Mlb Zn/yr, 18-yr life, after-tax NPV7% ~$1.05B at $4.53 Cu). 3-yr outlook 620–720koz (2027), 640–740koz (2028); circular 2027 ~$2.1B EBITDA / ~$1.5B FCF. Spot June 3 2026: gold ~$4,450/oz, copper ~$6.50/lb (both near records; FS decks were far lower). Base deck $3,700–4,200 gold / $5.00–6.00 copper. Sources: ELD Q1'26 results, Feb 2026 guidance, Skouries 2021 FS, Foran/McIlvenna 2025 FS, Mar 2026 circular, June 2026 spot. NAV at spot gold (~$4,450) would be ~$54/sh vs ~$42 at base deck. Dividend ~$0.30/yr. IRR rows price-only. Probabilities are judgment. NOT investment advice.  Long

Canadian Natural: Potential UptrendCanadian Natural Resources broke out to record highs in February, and some traders may see further upside in the oil-and-gas producer.
The first pattern on today’s chart is the 2024 high of $56.50. CNQ bounced above that old peak in mid-April, followed by higher lows in early May and late May. That could mean new support has developed above old resistance. It could also be consistent with bullishness resuming in the intermediate term.
Second, the 50-day simple moving average (SMA) is above the 100-day SMA. Both are above the 200-day SMA. That configuration, with faster SMAs above the slower, may reflect a bullish long-term trend.
Third, stochastics are turning up from an oversold condition.
Next, CNQ climbed on Monday and Tuesday but remained below last week’s high and above last week’s low. That kind of bullish inside price action could suggest buyers are gaining control.
Finally, the 8-day exponential moving average (EMA) is nearing a potential cross above the 21-day EMA. That may reflect short-term bullishness.
TradeStation has, for decades, advanced the trading industry, providing access to stocks, options and futures. If you're born to trade, we could be for you. Learn more here about TradingView’s Broker of the Year!
Past performance, whether actual or indicated by historical tests of strategies, is no guarantee of future performance or success. There is a possibility that you may sustain a loss equal to or greater than your entire investment regardless of which asset class you trade (equities, options or futures); therefore, you should not invest or risk money that you cannot afford to lose. Online trading is not suitable for all investors. View the document titled Characteristics and Risks of Standardized Options at www.TradeStation.com . Before trading any asset class, customers must read the relevant risk disclosure statements on www.TradeStation.com . System access and trade placement and execution may be delayed or fail due to market volatility and volume, quote delays, system and software errors, Internet traffic, outages and other factors.
Securities and futures trading is offered to self-directed customers by TradeStation Securities, Inc., a broker-dealer registered with the Securities and Exchange Commission and a futures commission merchant licensed with the Commodity Futures Trading Commission). TradeStation Securities is a member of the Financial Industry Regulatory Authority, the National Futures Association, and a number of exchanges.
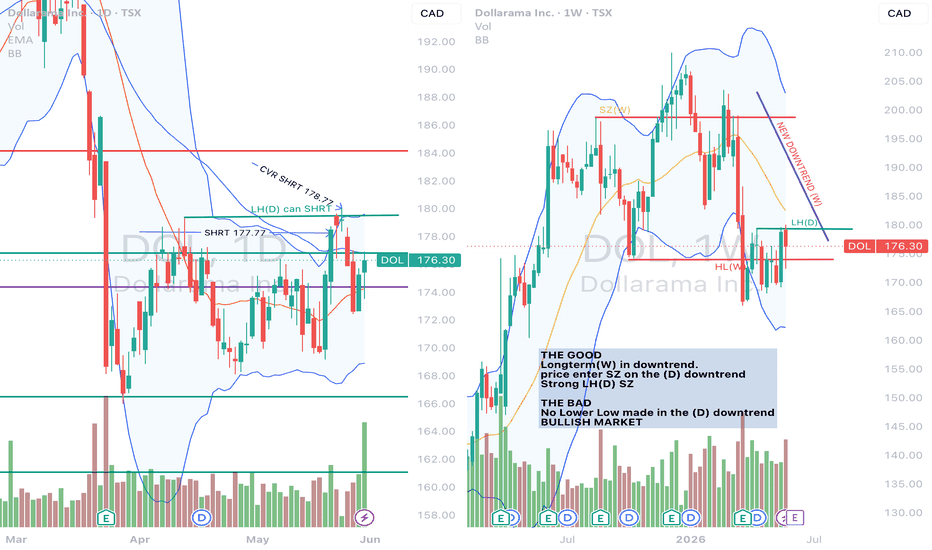
TradeStation Securities, Inc. and TradeStation Technologies, Inc. are each wholly owned subsidiaries of TradeStation Group, Inc., both operating, and providing products and services, under the TradeStation brand and trademark. When applying for, or purchasing, accounts, subscriptions, products and services, it is important that you know which company you will be dealing with. Visit www.TradeStation.com for further important information explaining what this means. ACCEPT THE STP LOSS AND WALK AWAYPeople mostly the non traders, always ask how much money do you plan to win before you enter the trade, as soon as they ask this question their novice trading mind is exposed. A good traders always counts meticulously counts how much one is willing to loose on a trade first.
This is not pessimistic sight this is forward deliberate trading shark thinking.
Let me explain, for the sake of this conversation we will refer to a win as Rw *reward* and a loss as Rs *risk*
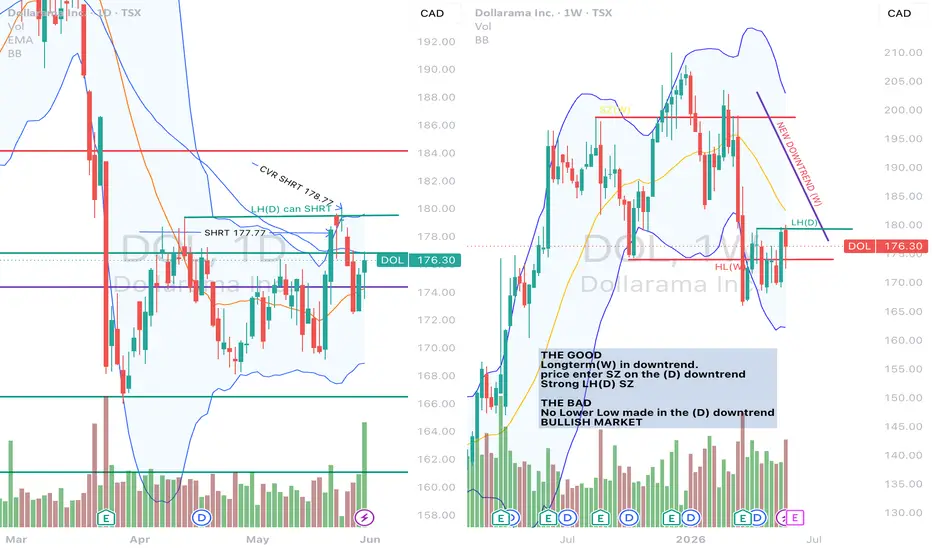
The Good
longterm chart (W) is in a downtrend, having recently broke and closed below the (W) demand zone
the current chart (D) on the left is running up into a Supply zone SZ,
lots of room for price to run down if SZ holds,
Good Rw to Rs ratio
The Bad
market is bullish
historically bullish stock
The (D) downtrend did not make a Lower Low before the correction to the SZ
The Key point to remember here is the Rw to Rs ratio. The trade did not work out as my tight STP loss was triggered above the SZ(D) yet price continued going down, I did not chase, I did not enter the trade again, I accepted the Stop Loss, know what you are willing to risk before you enter a trade
 Short
 Long

Long 
 Long