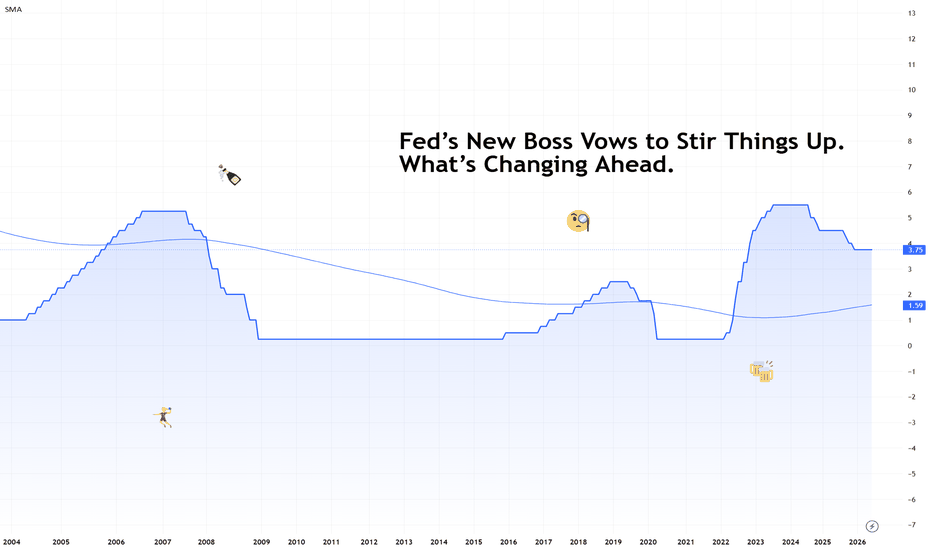
Fed’s New Boss Vows to Stir Things Up. What’s Changing Ahead.What do you mean “Good day?” It’s “Good afternoon.” Or not anymore.
The Federal Reserve got a new leader. Kevin Warsh wasted little time showing that things may look very different from here on out.
His first meeting as Fed Chair delivered a clue right from the opening words. You, and all traders alike, have gotten pretty used to the “Good afternoon” that could slosh billions in seconds.
So when Warsh greeted reporters with a "Good day," traders realized it’s the new normal.
Behind the shift, though, was a subtle message. Warsh appears determined to reshape how the Fed communicates, how it analyzes the economy, and perhaps even how investors think about monetary policy itself.
📈 Rates Stay Put, But The Message Changes
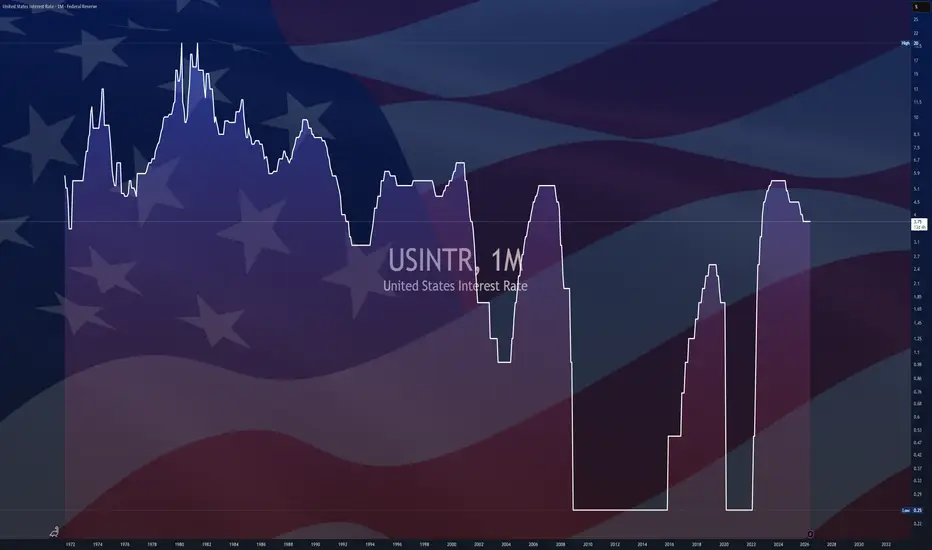
The Federal Open Market Committee voted unanimously, 12-0, to keep interest rates unchanged ECONOMICS:USINTR at 3.5% to 3.75%.
That decision came as little surprise. The bigger story was how things are expected to unfold from here.
Instead of publishing lengthy explanations and detailed hints about future moves, the Fed released a remarkably short statement consisting of only four concise paragraphs. Market watchers accustomed to parsing every adjective found themselves working with much less material.
Warsh's first meeting felt less like a traditional Fed gathering and more like a declaration that the old playbook was being retired.
🔮 Goodbye Forward Guidance
One of the most significant changes involves the end of what’s called "forward guidance."
Forward guidance refers to the practice of central banks giving investors clues about where interest rates might head in the future. During the Powell era, markets often spent months trying to anticipate those signals.
Warsh appears ready to shut that door.
"I think financial markets perform best when they react to incoming data," he said. In other words, he wants traders focused on economic reality rather than trying to predict the Fed's next sentence.
Take that, speculators. But also… let’s get this party started, gamblers and betting bros?
🛠️ Five Task Forces and a Big Cleanup Project
Warsh also announced five new task forces designed to review major areas of the central bank's operations.
The groups will examine Fed communications, the balance sheet, economic data sources, productivity trends, and the inflation framework itself.
That may sound academic, but these reviews could influence how the world's most important central bank operates for years to come.
When reporters pressed him for specifics on inflation, future rate decisions, and even the fate of the famous "dot plot" projections, his answer often boiled down to a variation of: we're studying it.
As Warsh repeatedly noted, "We have a task force for that."
🔥 Inflation: Public Enemy No. 1
While the Fed Chair remained careful about future rate decisions, he spoke with conviction about inflation.
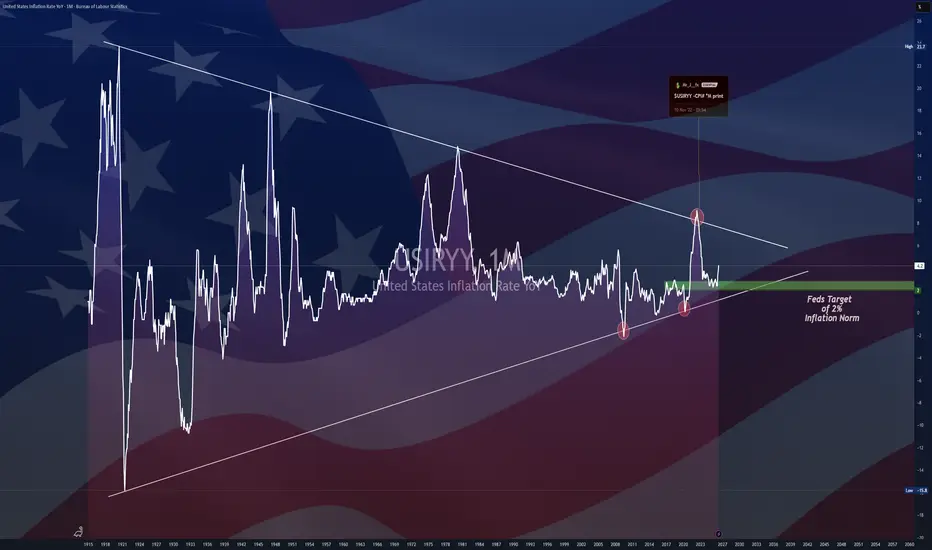
"We've missed for five years, and we're going to fix that," Warsh said, emphasizing that the committee remains fully committed to restoring price stability.
That message landed loudly across Wall Street (before dip buyers showed up) . Markets already expected a tougher stance on inflation. Many investors walked away believing the Fed's posture had shifted even further toward keeping policy tight for longer.
Interestingly, Warsh offered little indication that he shares President Trump's enthusiasm for lower interest rates. Anyone hoping for immediate cuts likely left the press conference disappointed.
🎭 More Mystery, More Volatility?
Perhaps the most important takeaway is that uncertainty is coming.
Under previous leadership, markets often received detailed projections, regular guidance, and a fairly clear sense of where policy was headed. Warsh appears comfortable leaving more questions unanswered.
Even future pressers may become less frequent. He suggested they are most valuable when the Fed actually has something important to say.
That could mean a market driven more by data from the economic calendar and less by Fed interpretation.
🚦 The Beginning of a New Era
Warsh is only one meeting into the job, and the real test will come as inflation, growth, employment, and global events continue to evolve.
But yesterday, investors learned three important things. The new chair values simplicity. He wants markets reacting to data rather than central bank hints. And he intends to rebuild the Fed's credibility around its inflation-fighting mission.
Off to you : Are you ready to embrace a more tight-lipped Fed? And perhaps, sharper volatility during unexpected rate decisions?
 Education
$GBIRYY - U.K Inflation Rate(May/2026)ECONOMICS:GBIRYY
May/2026
source: Office for National Statistics
- The annual inflation rate in the UK stood at 2.8% in May 2026, unchanged from the previous month and below market expectations of 3.0%. The reading remained at its lowest level since March last year.
Inflation slowed in housing and household services (2.7% vs. 3.0% in April), the softest level in almost two years, as owner-occupiers’ housing costs continued to ease, while food and non-alcoholic beverages decelerated further (2.2% vs. 3.0%), hitting their lowest level since December 2024.
Price growth also moderated in clothing and footwear (0.2% vs. 0.7%) and recreation and culture (1.5% vs. 1.7%). This was offset by upward pressure from transport inflation, which accelerated sharply to 6.8%, the highest since December 2022, up from 4.5% in April, driven by higher motor fuel prices, rising air fares, and an upward effect from vehicle excise duty (VED).
On a monthly basis, the CPI rose by 0.2% in May, below forecasts of a 0.4% gain and easing from a 0.7% increase in April. Macro Data Dashboard Review - June 2026With the economy seemingly in a perpetual state of uncertainty this decade, I have decided to make sense of it myself, so I can filter out editorial and political spin. I am sharing my dashboard as an Idea to provide a snapshot at the time of writing for future comparison. Some of these indicators already have received extensive commentary, however I think the context they provide when combined offers a unique perspective, and can give a sharper understanding of major events as they unfold in the future. I will start by breaking down my comments on each indicator and then will give my broad analysis while trying to avoid too much future speculation.
1. US Core PCE ECONOMICS:USCPCEPIAC - Inflation is still higher than the Fed’s target and above the historical baseline, while still lower than in 2021-2022. While it has been sticky, continued inflation persistence lacks the necessary tailwinds that led to the post-covid surge (Fed providing liquidity to bond market & interest rates at the bottom, which led to extreme YoY GDP growth). This matters little to the general public, who are still upset over cumulative price increases in recent years and above-average YoY inflation growth, especially in volatile categories like Food and Energy (which are not included in PCE).
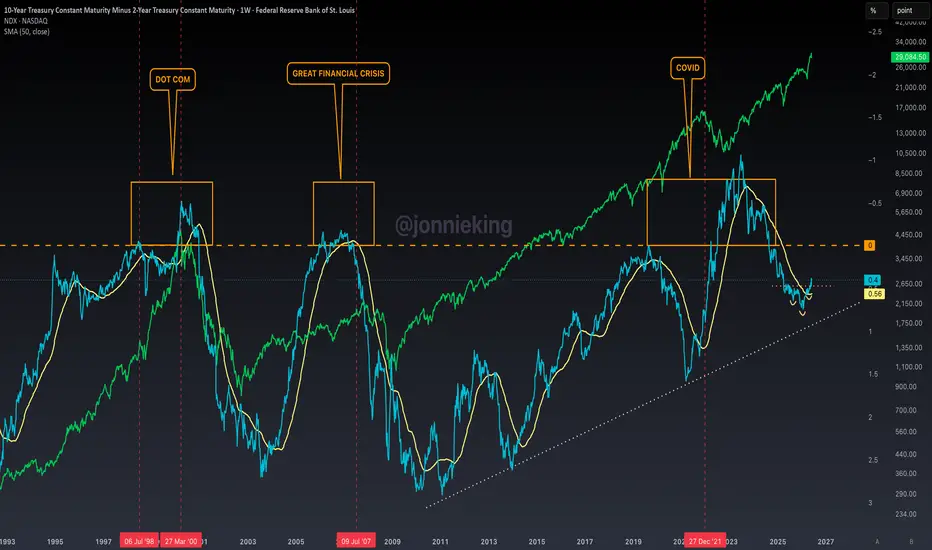
2. Policy Tightness Gauge $ECONOMICS:USINTR-FRED:UNRATE - Low unemployment and elevated interest rates will persist until pressure in the labor market arises, which there are not current signs of.
3. Household Debt Service Payments FRED:TDSP - Compare today’s level to extremes in the mid/late 00’s and 2020. Households are not yet stretched and will likely have capacity to borrow more.
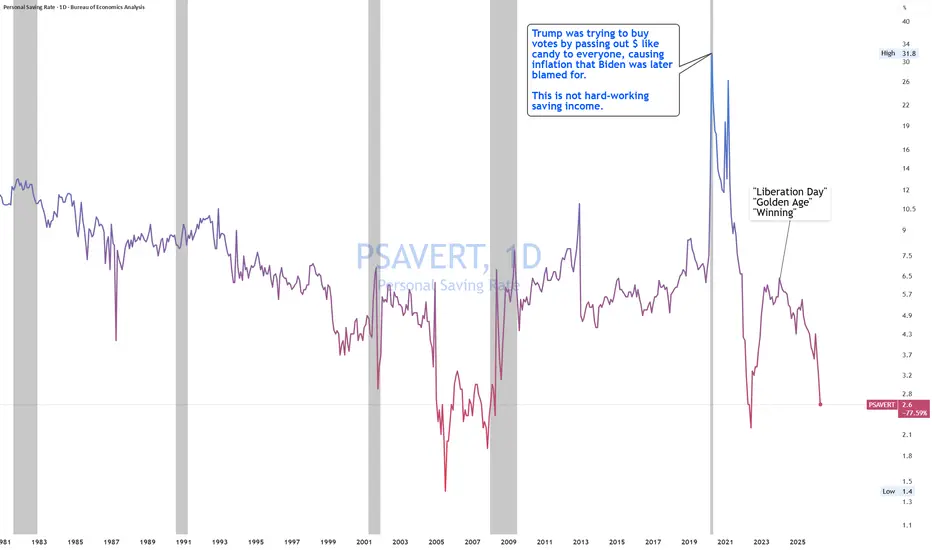
4. Personal Savings Rate FRED:PSAVERT - Individuals are saving below the 3-year average rate. Continued weakness could signal individuals have less capacity to absorb financial downturn.
5. Retail Sales YoY ECONOMICS:USRSYY - Current level is in line with healthy historical levels.
6. Temporary Worker Staffing FRED:TEMPHELPS - Below the 50-period average on the monthly chart and flattening out in recent months. Any significant changes here could be an early labor market indicator.
7. Average Hours Worked ECONOMICS:USAWH - Slightly below average, flattening, and aligned with average historical levels. I would consider this healthy.
8. Average Hourly Earnings ECONOMICS:USAHEYY - Elevated but flat. Wage growth was also an inflation driver at the start of the decade that is no longer a major factor.
9. Fed Balance Sheet Total Assets FRED:WALCL - New Fed Chair Warsh would like to see the balance sheet shrink, however the level remains high and it will be difficult to do so without causing bond yields to rise. Warsh was always a hawk until he sought the nod from the current administration, so we will see how he responds to bond market pressure if it continues.
10. ECONOMICS:USGDPYY - Healthy GDP growth.
11. Debt to GDP $ECONOMICS:USGD/ECONOMICS:USGDP - High and likely to continue growing without major policy changes that manage to both reduce the size of debt while keeping growth stable - a difficult task in today’s regime.
——
To summarize, what my indicators are telling me is that the economy is transitioning into a late-cycle phase but we are not quite there yet. Consumers have been resilient in the face of years of higher rates, and the labor market has cooled to allow GDP growth to remain healthy while blunting the strength of secondary inflation drivers.
Things are pretty balanced at the moment, so the question is what will change to create imbalance, which will force the Fed to change its stance? Will the Fed under Warsh’s leadership bend to political pressure to cut rates at the earliest sign of labor market pressure? Will consumers accept higher rates and continue to spend higher proportions of disposable income on debt payments, while saving less and less? Or will the Fed be forced to step in to calm the bond market in order to keep its own debt service payments at manageable levels (which will run counter to its fight against inflation)?
The biggest question of all is what the late-cycle stage of this cycle will look like. If I had to make an educated guess based on what I’m seeing today, I think this level of balance could continue for months or even years until certain areas are stretched to their extremes. I could see a scenario where consumers continue to borrow at high rates while keeping low personal savings, which will be stimulative to the economy until people can no longer afford the service payments. With the way things are headed in the US political cycle (right wing populism to left wing populism) this scenario fits the bill for a radical shift if it coincides with labor market instability.
I will keep checking this dashboard from time to time, since these indicators update slowly, and will post again whenever imbalances start to form, which based on what I’m seeing, and contrary to popular belief, could take a while.
Why a Fed Rate Hike Is UnlikelyThe geopolitical situation since the end of February has completely reshaped expectations regarding the monetary policy of the U.S. Federal Reserve (Fed). The disruption of the Strait of Hormuz, the sharp rise in oil prices, natural gas, urea fertilizer, and industrial metals, along with the rebound in headline inflation, have led markets to shift from expecting cuts in the federal funds rate to anticipating rate hikes.
The U.S. 2-year Treasury yield is currently well above the Fed's policy rate, meaning the market believes the federal funds rate should be higher than its current level of 3.75%. However, the Fed has changed leadership in the meantime. Kevin Warsh is now the Chairman of the Fed, although Jerome Powell remains a voting member of the FOMC.
The chart below presents market expectations regarding the future path of Fed interest rates. These expectations have been dramatically altered since the end of February.
Despite these new market expectations, largely driven by the persistence of geopolitical tensions in the Middle East and therefore potentially reversible, I believe it is unlikely that Kevin Warsh's Fed will raise the federal funds rate this year, except in an extreme scenario.
Here are the reasons supporting this view:
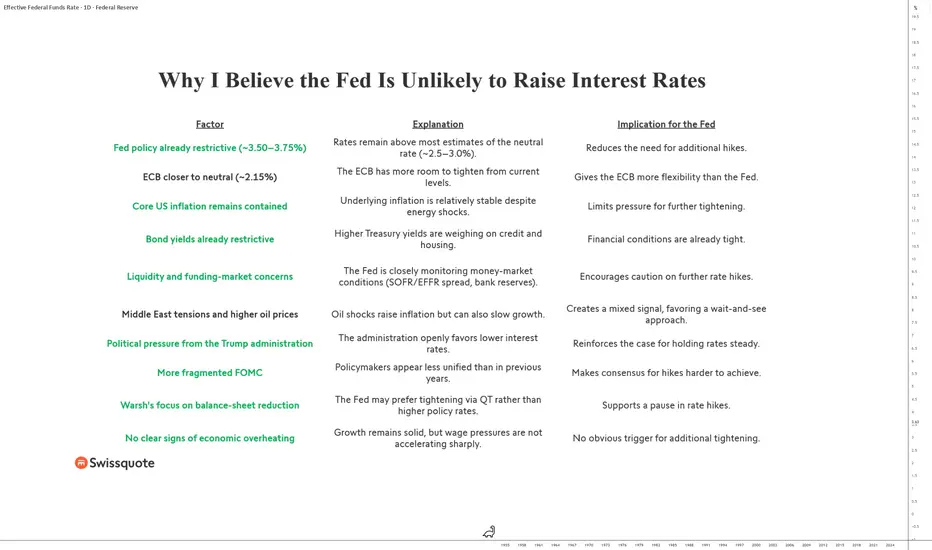
First, the U.S. policy rate is already in restrictive territory. With the federal funds rate at 3.75%, monetary policy remains above most estimates of the neutral rate, generally considered to be between 2.5% and 3%. In other words, the Fed is already exerting a restraining effect on the economy and does not necessarily need to raise rates further to maintain restrictive financial conditions.
Second, underlying U.S. inflation remains relatively contained. While higher oil prices mechanically boost headline inflation, the Fed places greater emphasis on core inflation, which excludes food and energy. As long as core inflation remains under control, a preemptive rate hike appears difficult to justify.
The histogram below shows U.S. core inflation according to the CPI measure. Note that all economic data are available directly on TradingView.
Furthermore, U.S. bond yields have risen sharply in recent months. Long-term interest rates are already exerting significant pressure on credit markets, real estate, and investment activity. Part of the monetary tightening process is therefore being carried out directly by the market itself.
Finally, Kevin Warsh appears to favor reducing the Fed's balance sheet rather than raising interest rates again. Continuing quantitative tightening (QT) allows liquidity to be gradually withdrawn from the financial system and monetary conditions to be tightened without altering the policy rate. This approach seems more consistent in an environment where some liquidity pressures still persist in U.S. money markets.
Unless there is a sustained deterioration in core inflation, a wage-price spiral, or a loss of confidence in inflation expectations, the most likely scenario remains that the federal funds rate will stay at its current level for several more months.
The table below outlines the reasons why it is unlikely that the Fed, under the leadership of Kevin Warsh, will raise U.S. federal funds rates in the near term.
DISCLAIMER:
This content is intended for individuals who are familiar with financial markets and instruments and is for information purposes only. The presented idea (including market commentary, market data and observations) is not a work product of any research department of Swissquote or its affiliates. This material is intended to highlight market action and does not constitute investment, legal or tax advice. If you are a retail investor or lack experience in trading complex financial products, it is advisable to seek professional advice from licensed advisor before making any financial decisions.
This content is not intended to manipulate the market or encourage any specific financial behavior.
Swissquote makes no representation or warranty as to the quality, completeness, accuracy, comprehensiveness or non-infringement of such content. The views expressed are those of the consultant and are provided for educational purposes only. Any information provided relating to a product or market should not be construed as recommending an investment strategy or transaction. Past performance is not a guarantee of future results.
Swissquote and its employees and representatives shall in no event be held liable for any damages or losses arising directly or indirectly from decisions made on the basis of this content.
The use of any third-party brands or trademarks is for information only and does not imply endorsement by Swissquote, or that the trademark owner has authorised Swissquote to promote its products or services.
Swissquote is the marketing brand for the activities of Swissquote Bank Ltd (Switzerland) regulated by FINMA, Swissquote Capital Markets Limited regulated by CySEC (Cyprus), Swissquote Bank Europe SA (Luxembourg) regulated by the CSSF, Swissquote Ltd (UK) regulated by the FCA, Swissquote Financial Services (Malta) Ltd regulated by the Malta Financial Services Authority, Swissquote MEA Ltd. (UAE) regulated by the Dubai Financial Services Authority, Swissquote Pte Ltd (Singapore) regulated by the Monetary Authority of Singapore, Swissquote Asia Limited (Hong Kong) licensed by the Hong Kong Securities and Futures Commission (SFC) and Swissquote South Africa (Pty) Ltd supervised by the FSCA.
Products and services of Swissquote are only intended for those permitted to receive them under local law.
All investments carry a degree of risk. The risk of loss in trading or holding financial instruments can be substantial. The value of financial instruments, including but not limited to stocks, bonds, cryptocurrencies, and other assets, can fluctuate both upwards and downwards. There is a significant risk of financial loss when buying, selling, holding, staking, or investing in these instruments. SQBE makes no recommendations regarding any specific investment, transaction, or the use of any particular investment strategy.
CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. The vast majority of retail client accounts suffer capital losses when trading in CFDs. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Digital Assets are unregulated in most countries and consumer protection rules may not apply. As highly volatile speculative investments, Digital Assets are not suitable for investors without a high-risk tolerance. Make sure you understand each Digital Asset before you trade.
Cryptocurrencies are not considered legal tender in some jurisdictions and are subject to regulatory uncertainties.
The use of Internet-based systems can involve high risks, including, but not limited to, fraud, cyber-attacks, network and communication failures, as well as identity theft and phishing attacks related to crypto-assets.
Education 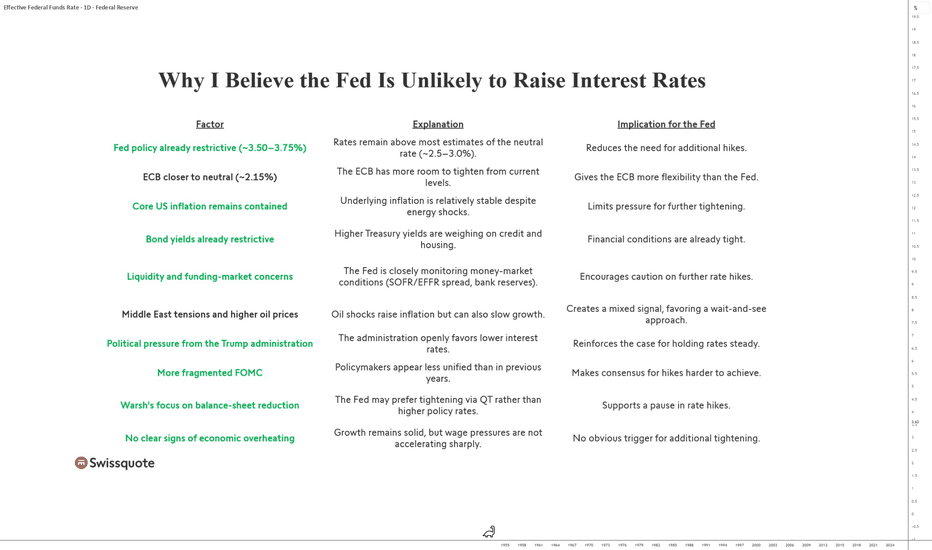
$CNIRYY - Chinese CPI Holds Steady (May/2026)ECONOMICS:CNIRYY
May/2026
source: National Bureau of Statistics of China
- China’s annual inflation held steady at 1.2% in May 2026, unchanged from the previous month but slightly below market expectations of 1.3%.
Non-food inflation edged higher (1.9% vs 1.8% in April), lifted by an acceleration in transport costs (5.4% vs. 4.6%) amid higher energy prices and supply-chain disruptions linked to the ongoing Middle East conflict.
Prices also continued to rise for clothing (1.4% vs. 1.5%), healthcare (2.1% vs. 2.2%), and education (1.3% vs. 1.3%).
Meanwhile, housing costs remained subdued (-0.2% vs. -0.2%). On the food side, prices fell for the second straight month (-1.7% vs -1.6%), marking the sharpest drop since October, largely due to persistently weak pork prices and continued declines in fresh fruit costs.
Core inflation, excluding food and energy, rose 1.1% yoy, after April's 1.2% gain.
On a monthly basis, consumer prices edged down 0.1%, reversing a 0.3% increase in April. However, the decline was milder than forecasts of a 0.2% drop. $USNFP - U.S Non-Farm Payrolls (May/2026)ECONOMICS:USNFP 172K
May/2026
source: U.S. Bureau of Labor Statistics
- The US economy added 172K jobs in May 2026, well above forecasts of 85K, and following an upwardly revised 179K gain in the previous month, continuing to point to a resilient labour market.
Job gains occurred in leisure and hospitality (70K), mainly food services and drinking places (48K); local government (55K), health care (35K) and manufacturing (7K).
Employment in financial activities declined by 22K, mostly insurance carriers and related activities (-11K) and commercial banking (-3K).
Meanwhile, employment in transportation and warehousing was essentially unchanged (+1K) and other industries including construction, wholesale trade, retail trade, information, professional and business services also saw little changes.
In addition, upward revisions to the March figures added to the strength of the report, with employment levels in March and April now estimated to be 93K higher than previously reported. $EUIRYY -E.U Inflation (May/2026)ECONOMICS:EUIRYY 3.2%
May/2026 +0.2%
source: EUROSTAT
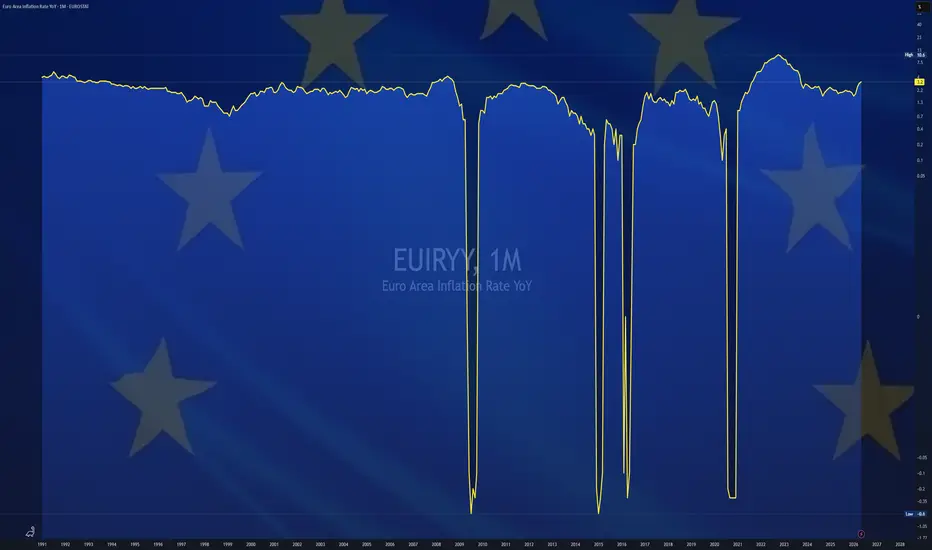
- Eurozone consumer price inflation reached 3.2% in May 2026, up from 3.0% in April and matching market expectations, according to preliminary data.
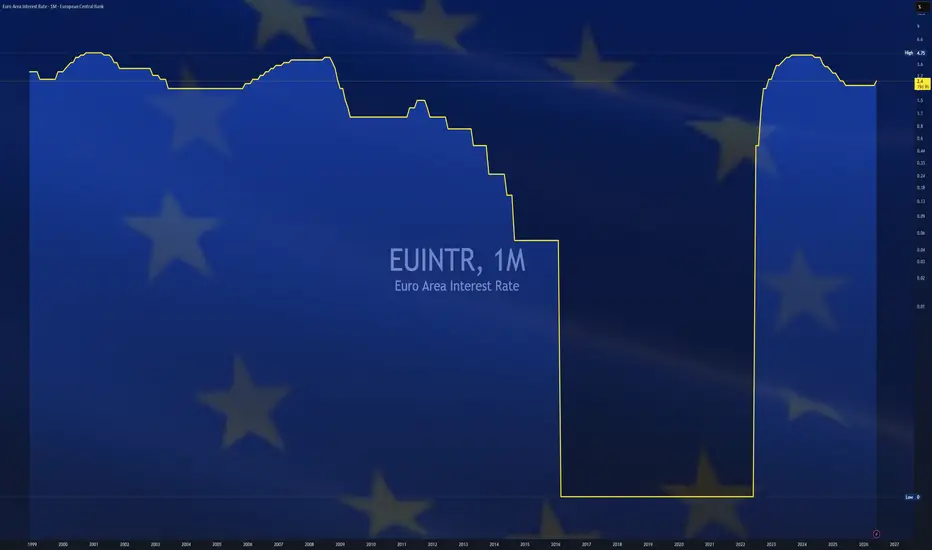
This marks the highest rate since September 2023, staying significantly above the European Central Bank’s 2.0% target.
Energy costs surged 10.9%, the steepest rise since February 2023, fueled by supply constraints tied to the Middle East conflict. Prices also accelerated for services (3.5% vs. 3.0% in April) and non-energy industrial goods (0.9% vs. 0.8%), while inflation for food, alcohol, and tobacco eased (2.0% vs. 2.4%).
The core rate, excluding energy and food, climbed to 2.5% from 2.2%, suggesting broadening price pressures beyond energy. Among major Eurozone economies, inflation picked up in Spain (3.6% vs. 3.5%), the Netherlands (3.4% vs. 2.5%), Italy (3.3% vs. 2.8%), and France (2.8% vs. 2.5%), but slowed in Germany (2.7% vs. 2.9%). $USGDPQQ - U.S GDP (Q1/2026)ECONOMICS:USGDPQQ 1.6%
Q1/2026 +0.6%
source: U.S. Bureau of Economic Analysis
- The US economy expanded an annualized 1.6% in Q1 2026, up from 0.5% in Q4 but below 2% in the advance estimate, primarily reflecting downward revisions to investment and consumer spending.
Consumer spending rose 1.4%, less than 1.6% in the advance estimate.
The rise was mainly supported by demand for services (1.8%) while goods remained subdued (0.4%).
Also, gross private domestic investment rose 7%, below the 8.7% reported in the advance estimate.
Business investment in equipment surged 17.2%, while spending on intellectual property products increased 11.6%.
In contrast, investment in structures fell 5.4%, and residential investment declined 6.2%.
Meanwhile, net trade contributed negatively to GDP (-1.25 pp), as exports rose by 13.1% (vs 12.9% in the first estimate) while imports jumped 21.1% (vs 21.4%).
Government spending rose 4.4%, in line with the initial estimate, recovering from a 5.6% contraction in Q4, as activity resumed following the end of the government shutdown. Japan's "Money Printer Go Brrr?" Experiment: When the Math Stops**Japan's "Money Printer Go Brrr?" Experiment: When the Math Stops Adding Up** 📉💸
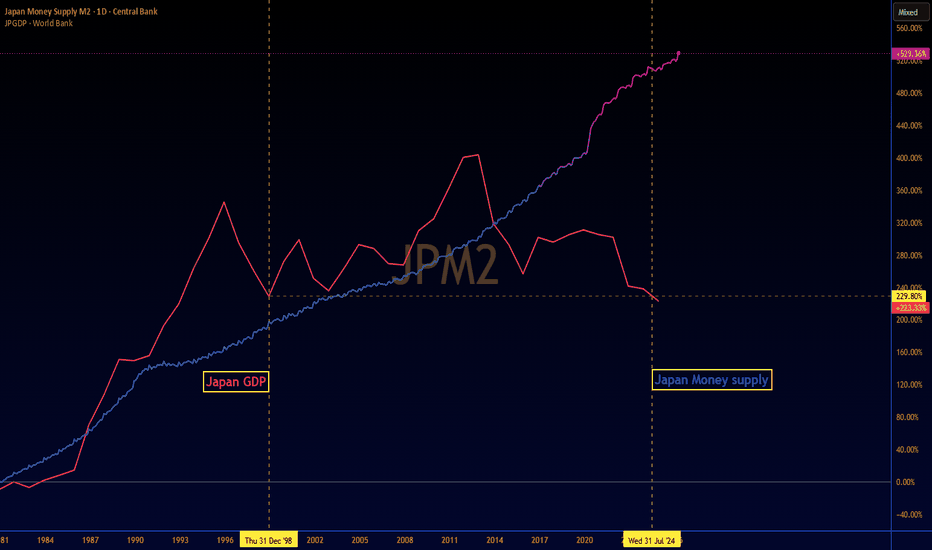
Here's a powerful long-term overlay chart (1981–2024) showing **Japan M2 Money Supply** (Central Bank data) vs. **Japan GDP** (World Bank data), both indexed as cumulative percentage growth from the starting point.
- **M2 Money Supply**: +529.36% 🔥 (the soaring purple line)
- **Japan GDP**: +223.33% (the red line that peaked decades ago and has been far more modest since)
The divergence is insane.
For decades, Japan has run one of the most aggressive monetary experiments in modern history, zero rates, massive QE, Abenomics, yield curve control, the works. The Bank of Japan flooded the system with liquidity. Yet GDP growth never kept up. The classic Quantity Theory of Money (MV = PY) math that "more money = more spending/inflation/growth" broke down hard.
Why? Collapsing **velocity of money**, structural headwinds (aging population, zombie companies, massive public debt, cultural saving preference), and repeated bouts of deflationary psychology. Japan essentially proved that you can print enormous amounts of money without generating proportional nominal GDP growth when the money just sits in banks or government bonds instead of circulating productively.
This chart is a masterclass in why monetary policy has limits, especially in a high-debt, low-growth, demographics-challenged economy. The "lost decades" weren't solved by the printer alone.
What do you think, is Japan the ultimate case study in monetary policy limits, or is the recent inflation pickup finally changing the game?
Would love to hear your take below 👇
feel free to like, comment, and spark some discussion!
#Japan #M2 #GDP #MonetaryPolicy #Abenomics #Macroeconomics #Economics #TradingView  Education
Short 
Long 
$JPIRYY -Japan CPI (April/2026)ECONOMICS:JPIRYY 1.4%
April/2026 -0.1%
source: Ministry of Internal Affairs & Communications
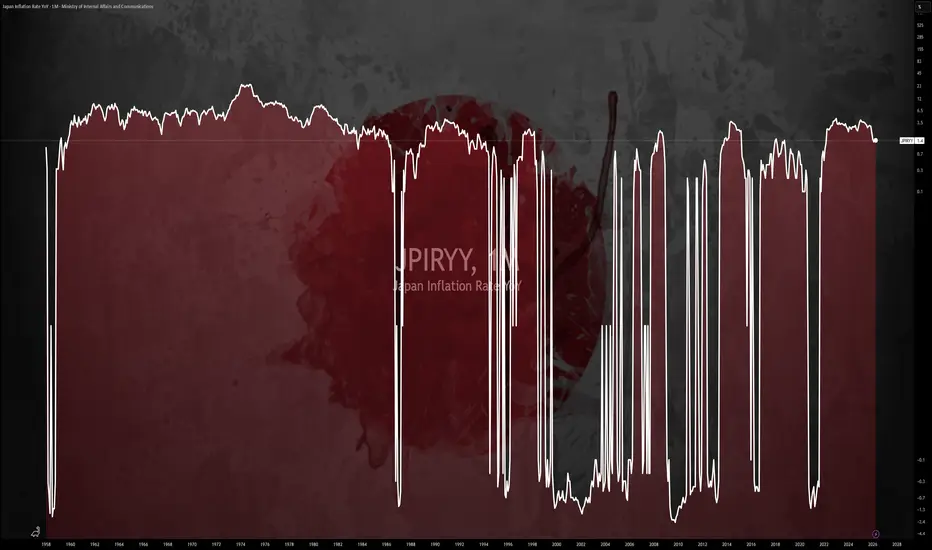
- Japan’s annual inflation edged down to 1.4% in April 2026 from 1.5% in the prior month. Food prices rose the least in 18 months amid a further slowdown in rice costs.
Inflation also slowed for transport (1.5% vs 2.1%), housing (0.8% vs 1.0%), clothing (1.5% vs 2.1%), household items (1.8% vs 2.7%), recreation (1.3% vs 2.3%), and miscellaneous goods (0.1% vs 0.7%).
Healthcare costs were flat after rising 0.2% previously.
In contrast, inflation for communication accelerated (7.4% from 7.0%). Meanwhile, electricity prices fell at a slower pace (-2.6% vs -8.0%), as did gas prices (-3.4% vs -5.2%), with the impact of subsidies fading.
Tokyo reportedly moves to ease living costs amid the impact of a weak yen and high energy prices.
Core inflation also eased to 1.4% from 1.8% in March, the lowest level since March 2022, remaining below the central bank’s 2% target for a third consecutive month.
On a monthly basis, consumer prices inched 0.1% higher, slowing from March's 0.4% increase.