TAQA โ Breakout Above 13.70 Resistance TAQA โ Breakout Above 13.70 Resistance ๐โก
The Reality: I see a "Fundamental Anchor" leading Egyptโs energy distribution across gas, electricity, and refined products.
I note that TAQA is currently benefiting from the national gas grid expansion and the privatization of the electricity market, while shifting focus toward EV charging infrastructure and green hydrogen in 2026.
The Utility Engine: I recognize that while high CapEx for grid expansion keeps immediate margins stable, the utility-bas
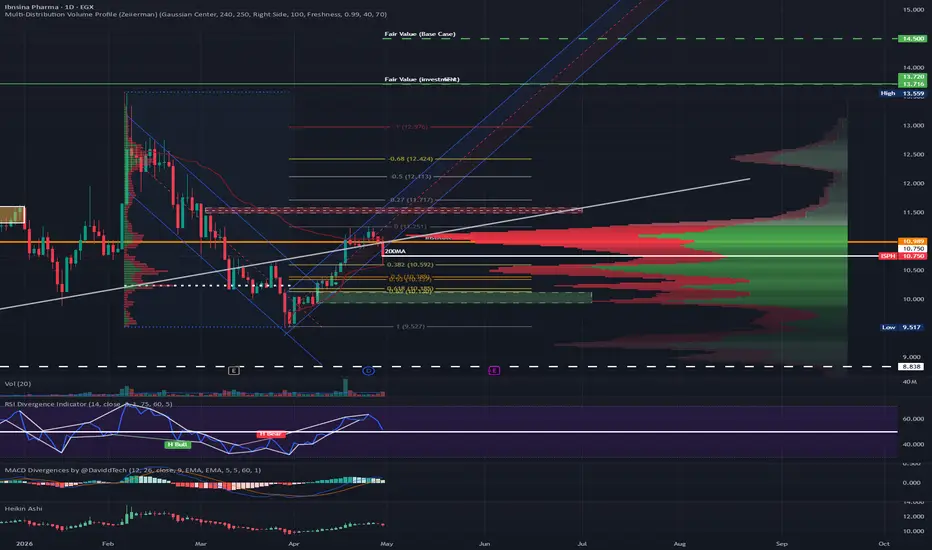
ISPH Structural RisksISPH Structural Risks
I am tracking Ibnsina Pharma (ISPH) as it exhibits several bearish signals following its dividend date.
Here is the breakdown of the current technical setup:
Negative Indicators: The stock closed with a long red candle on high volume, breaking the main 11.00 support.
This return below the long-term trendline suggests a fake breakout. ๐
The 200MA Pivot: Price is currently resting on the 200MA.
While recent negativity feels like "noise" post-dividends, this level must
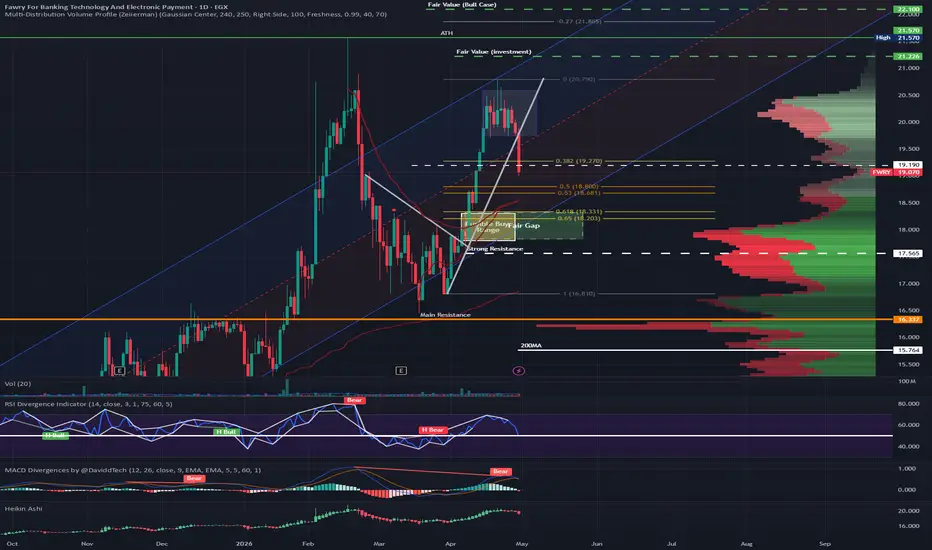
FWRY Technical Analysis: Tracking the Correction๐ FWRY Technical Analysis: Tracking the Correction
I am closely monitoring FWRY following its recent price action.
Here is the current technical outlook:
Resistance & Consolidation: After hitting the upper limit of its long-term uptrend on Feb 25, the stock entered a two-week consolidation phase and is now showing signs of softness.
Structural Breaks: Weโve seen the price break below several key technical markers, including the rising trend line, the consolidation channel, the 0.382 Fibonac
LCSW (Lecico Egypt): The Export HedgeLCSW (Lecico Egypt): The Export Hedge ๐๐ข
The Driver: A massive USD generator.
With 81.4% of sanitary ware volume exported to Europe and the Middle East, Lecico acts as a powerful natural hedge against EGP volatility. ๐น๐ก๏ธ
Sharia Status: โ
Still Compliant. As of the April 2026 update.โช๏ธ๐
The 2026 Strategy: Management is betting big on the future, planning EGP 650M+ in investments this year to upgrade production lines.
While 2025 profits (EGP 244M) "normalized" from the 2024 peak, they remain
SKPC โ Fundamental Strength vs. The 2.5-Year Downtrend SKPC โ Fundamental Strength vs. The 2.5-Year Downtrend ๐๐งช
The Reality: I see a "Vital Industrial Anchor" that is navigating a complex recovery phase.
While 2025 saw a painful 55.38% decrease in net profit (down to EGP 1.133 billion), the outlook for 2026 is much brighter. I note that export expansion into 57 countries, including success in South American markets, is the primary engine for the projected 1.45 EGP EPS recovery.
The Fundamental Fortress: I recognize SKPC as a high-quality entity,
SUGR โ Operational Giant vs. Financial Decay SUGR โ Operational Giant vs. Financial Decay ๐๐ฌ
The Reality: I see a "Fundamental Trap" masquerading as a staple powerhouse.
While Delta Sugar historically benefits from high global sugar prices which hit 14.5 US cents/lb in April 2026 the internal financials have turned ugly.
I note a staggering FY 2025 net loss of EGP 526.13 Million, a total reversal from its profitable 2024.
The Debt Crisis: I observe a company under extreme leverage.
The Debt-to-Equity ratio has surged to 269.7%, and wi
TMGH: Mass Distribution Detected! 5.6M Shares Dumped in Last HouAnalysis Snapshot:After a deep dive using the "Microscope" on TMGH (Talaat Moustafa Group), the technical indicators are screaming "Distribution" despite the price holding near the peak.Key Technical Observations:Massive Outflow: A staggering 5.62 million shares were liquidated during the last hour of Thursday's session (April 30, 2026). This is a clear "Whale footprint" of institutional exiting.CMF Alert: The Chaikin Money Flow (CMF) has plunged to -0.55. This significant negative value confirm
MASR โ ATH Resistance vs. Bearish Divergence MASR โ ATH Resistance vs. Bearish Divergence ๐๐๏ธ
The Reality: I see a "Real Estate Cornerstone" thriving in East Cairo, particularly with the Taj City and Sarai projects.
While the stock has surged to 6.11, I note that cash flow is heavily committed to accelerated project deliveries, meaning profits are currently more "accounting-based" (Percentage of Completion) than liquid cash.
The Fundamental Moat: I recognize MASR as a "Safe Haven" for local liquidity. Its massive land bank acts as an in
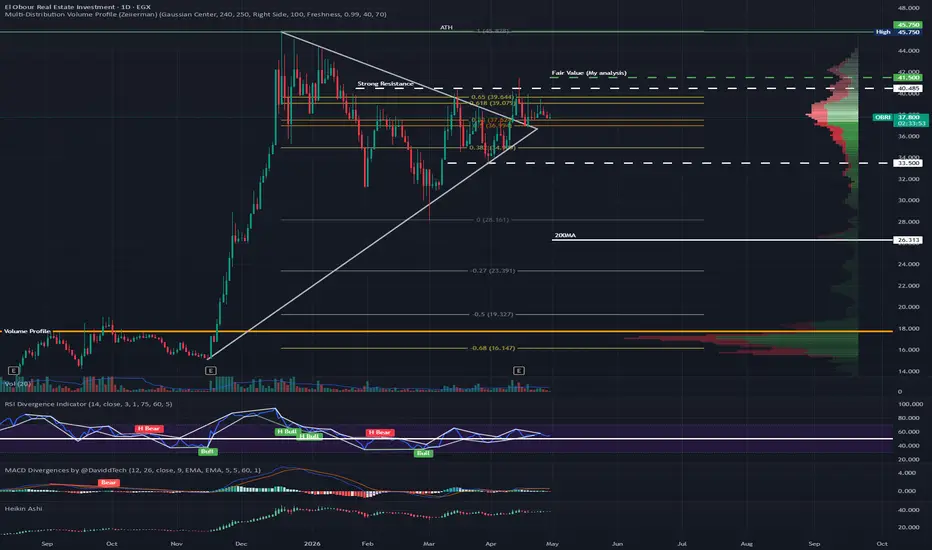
OBRI โ Resistance Rejection & Declining Volume OBRI โ Resistance Rejection & Declining Volume ๐๐๏ธ
The Reality: I see a "Speculative Hold" navigating a high-demand but high-cost environment.
While the company thrives on its strategic land bank in Qalyubia and East Cairo, it is being squeezed by the 2026 reality of expensive construction materials and high interest rates.
The Cash Trap: I note that while the stock price has shown life, operating cash flow remains tight.
Because earnings are largely tied to "Percentage of Completion" account
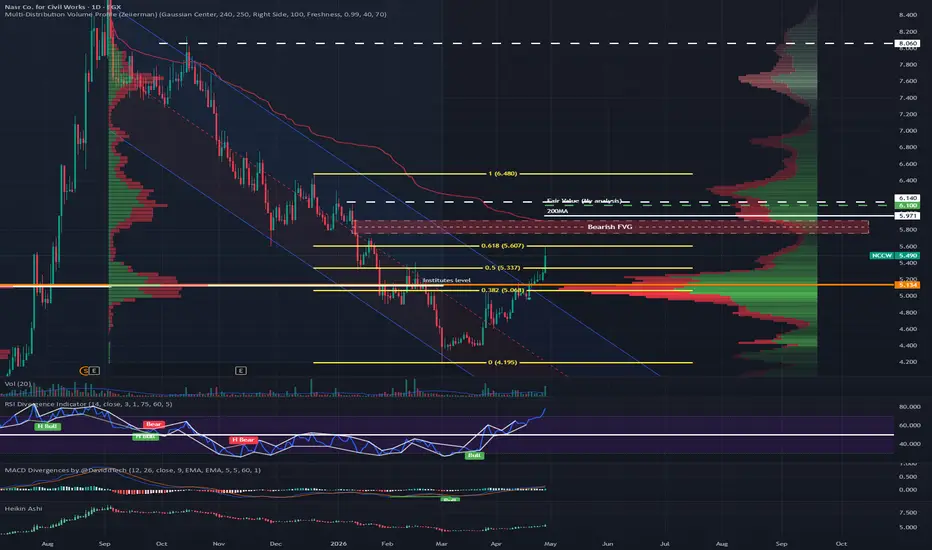
NCCW โ Project Backlog vs. Margin CompressionNCCW โ Project Backlog vs. Margin Compression ๐๐๏ธ
The Reality: I see a "Mid-Cap Contractor" currently stuck in a cooling cycle. ๐ฌ๏ธ
While 2024 was stellar, the FY 2025 results show an 11.4% decline in net profit to EGP 60.35 million.
The story here is a "Margin Pinch" revenue was stable at EGP 348.7M, but domestic rising costs for materials and overhead are eating the bottom line. ๐ฉน๐๏ธ
The Regional Pivot: I note the company is looking outside for growth, recently signing a EUR 46M agreement in
EGAS โ Ascending Triangle Breakout on 10X VolumeEGAS โ Ascending Triangle Breakout on 10X Volume ๐๐ฅ
The Reality: I see a critical "Infrastructure Engine" powering Egyptโs energy transition.
Revenue grew 20% to reach EGP 9 billion in FY 2025, with a solid 25% jump in net profit for the first nine months.
As the primary executor of the national natural gas delivery project, its growth is directly tied to national development.
The Cash Cycle: I note that despite the high revenue, immediate cash margins remain tight. This is a capital-intensi
(CRST) Crest Mark For Contracting And Real Estate Development:
๐ Market Structure & Trend
The stock is currently range-bound after a prior upward move.
Price action shows consolidation between ~0.54 and ~0.65 EGP, forming a horizontal trading range.
The recent bounce suggests buyers are defending the lower support zone, but momentum is still not strong enough for a confirmed breakout.
๐ Key Levels
๐ข Support
0.575 โ 0.59 EGP โ Primary demand / entry zone
0.539 EGP โ Strong support & invalidation level (Stop Loss)
๐ด Resistance
0.646 โ 0.652 EGP โ I
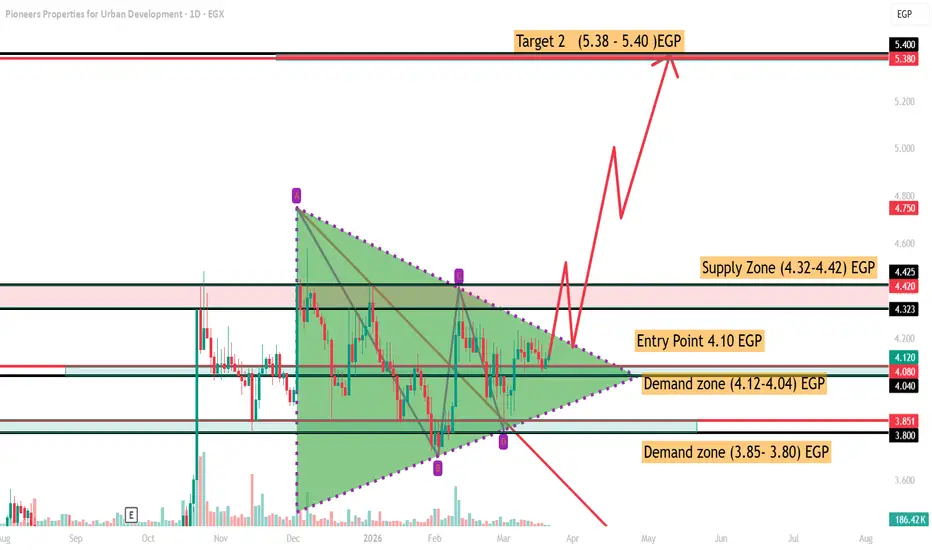
(PRDC) Pioneers Properties for Urban Development ๐ Market Structure & Pattern
The stock is forming a symmetrical triangle (compression pattern) after a prolonged consolidation.
Price is near the apex, which means a strong breakout is ูุฑูุจ.
The internal structure (AโBโCโD swings) suggests accumulation phase rather than distribution.
๐ Key Levels
๐ข Demand Zones (Support)
4.12 โ 4.04 EGP โ Primary demand (current holding area)
3.85 โ 3.80 EGP โ Stronger support (last ุฏูุงุน zone)
๐ด Supply Zone (Resistance)
4.32 โ 4.42 EGP โ Key breakout bar
EFID โ Testing Support Before the ATH Run EFID โ Testing Support Before the ATH Run ๐๐ฐ
The Reality: A "Blue-Chip Powerhouse" in its prime! ๐๏ธ
Editaโs FY 2025 results were nothing short of staggering, with net profit surging 72.6% to EGP 2.4B.
This isn't just "inflation pricing" it's a massive regional expansion into Morocco and Iraq combined with a dominant 50% share of the local cake market.
The Cash Machine: Edita is a master of "Cash-and-Carry." ๐ธ
Nearly 100% of its operating profit is captured as actual liquid cash, meaning its
BTFH โ Negative Cash Flow vs. The Fintech Pivot BTFH โ Negative Cash Flow vs. The Fintech Pivot ๐๐ฆ
The Reality: A massive financial turnaround with a "Cash Flow" catch. ๐ญ
Beltone has transformed from a loss-making entity into a profit powerhouse, with FY 2025 net income reaching EGP 1.35 billion.
However, the negative Operating Cash Flow (CFO) is the "elephant in the room."
The company is aggressively funneling its EGP 6.96B revenue into building a massive EGP 30B+ lending portfolio, meaning profits are currently on paper (accruals) rathe
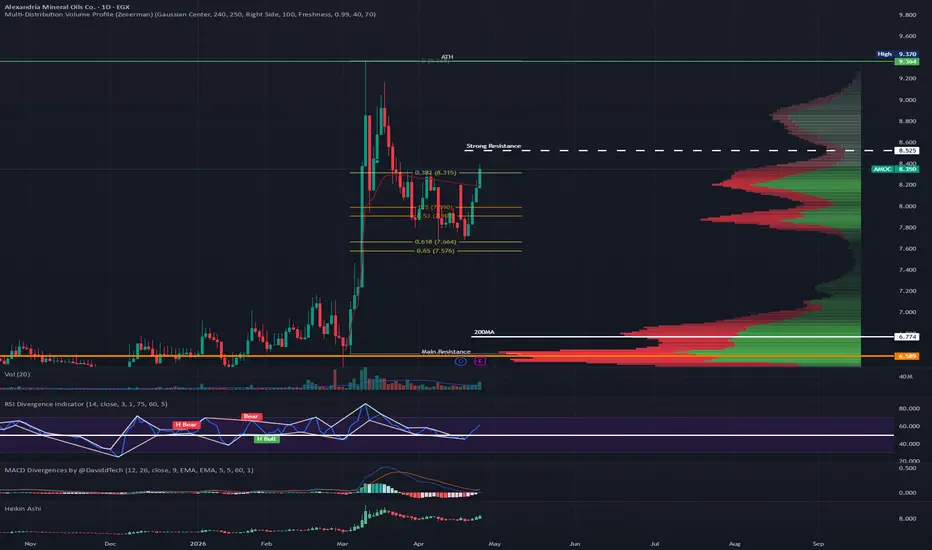
MOC โ Golden Zone Rebound vs. Market Fatigue AMOC โ Golden Zone Rebound vs. Market Fatigue ๐๐ข๏ธ
The Reality: A "Lean & Mean" energy machine! ๐๏ธ
AMOC is showing impressive resilience with revenue hitting EGP 20.74B (+14% YoY).
Unlike many peers, it has a "clean" profit profile over 90% of income comes from core refining, with almost no reliance on "paper gains" from currency fluctuations. ๐๐ธ
The Fortress Balance Sheet: In a sector usually weighed down by debt, AMOC is a rare breed it holds more cash than debt. ๐ฆ๐ก๏ธ
Working capital has st
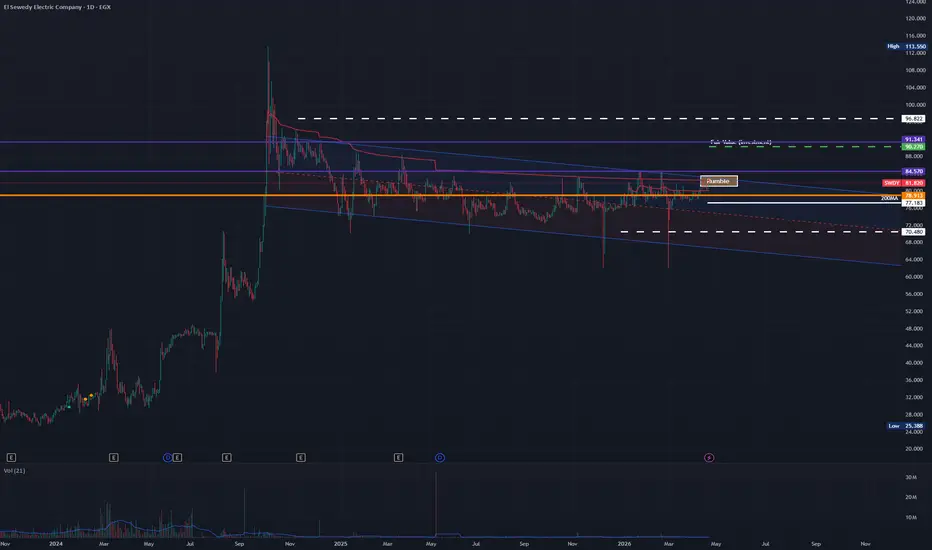
The Situation with Elsewedy Electric (SWDY)The Situation with Elsewedy Electric (SWDY)
While Elsewedy Electric remains a fundamentally strong powerhouse in the industrial sector, the recent buyout has fundamentally changed its trading dynamics.
Here is a breakdown of why itโs currently a "dead zone" for retail investors:
1. The Liquidity Trap
The stock is currently suffering from extremely low liquidity.
When a major entity buys out the majority of shares, the "free float" (the shares actually available for public trading) shrinks t
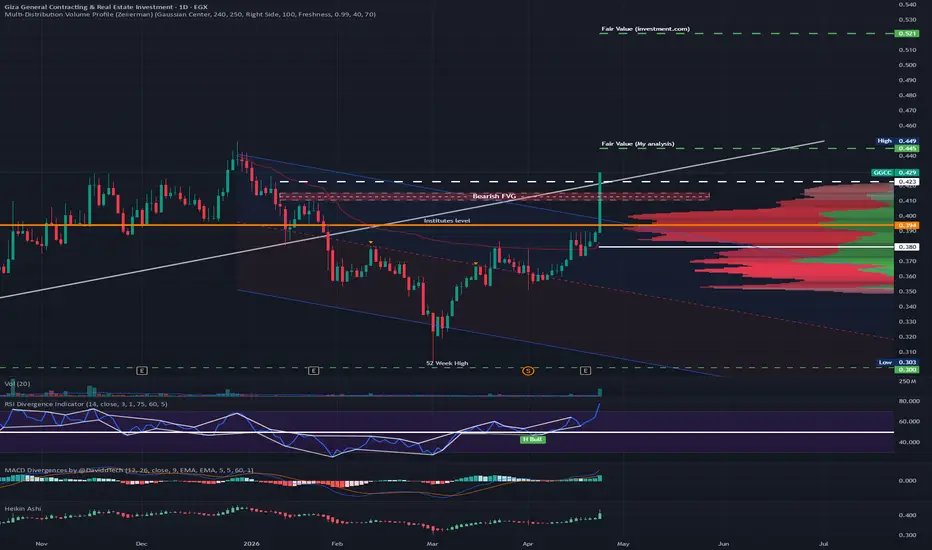
GGCC โ Breakout Digesting the Capital Hike GGCC โ Breakout Digesting the Capital Hike ๐๐๏ธ
The Reality: A "Penny Stock" powerhouse with high-volume dynamics. ๐
GGCC manages a massive EGP 1.13 billion revenue stream, yet operates on razor-thin margins. While it boasts a solid 95% core contracting income, the real pressure comes from a 0.9x interest coverage ratio.
In a high-interest environment, this leaves almost no room for operational errors or payment delays. ๐โ
The Capital Shift: The stock is currently digesting a major supply shoc
RMDA โ Golden Zone Consolidation & Pricing Power RMDA โ Golden Zone Consolidation & Pricing Power ๐๐
The Reality: A true fundamental "Engine" disguised by debt! โ๏ธ
RMDA's revenue growth is massive (+48%), and the core business is far more profitable than the bottom line looks.
While net income is EGP 268M, the operating income is nearly EGP 942M.
The "gap" is simply the cost of debt used to fuel their high-margin expansion into chronic-care medicine. ๐ฅ๐
The Cash Power: RMDA is a cash-flow monster, generating EGP 1.22B from operations annu
ATQA โ The 10.36 Breakout vs. The Billet SqueezeATQA โ The 10.36 Breakout vs. The Billet Squeeze ๐โ๏ธ
The Reality: A "Rolling Mill" caught in a brutal margin squeeze. ๐๐
ATQA reported a staggering 94.7% drop in 2025 net profit (down to EGP 30.7M from EGP 577.7M in 2024), despite revenue actually growing to EGP 6.33B.
Because they aren't an integrated producer (like Ezz Steel), they are at the mercy of rising global billet prices and energy costs, leaving them with a razor-thin 0.5% net margin. ๐๏ธ๐ฅ
The Valuation Gap: The financials are in a
IEEC โ Technical Breakout vs. Accrual BloatIEEC โ Technical Breakout vs. Accrual Bloat ๐๐๏ธ
The Reality: (IEEC) is currently a "Speculative Small-Cap" that is struggling to turn projects into profits. ๐
Revenue growth is visible, but the 87% collapse in net income is a massive red flag. ๐ฉ
The company is suffering from "Slow Collection Syndrome," common in the construction sector, where receivables age significantly before turning into cash.
At a Debt-to-Market Cap ratio that is increasingly strained, the company is one missed mileston
UNIP โ Scrap Value vs. Financial Reality UNIP โ Scrap Value vs. Financial Reality ๐๐ฆ
The Reality: A classic "Value Trap" in the penny stock realm. ๐ธ๏ธ
While revenue sits at EGP 1.37 billion, net income has collapsed by 87% to a mere EGP 13.05 million.
With a razor-thin net profit margin of 0.95%, the company is effectively dancing on the edge of a loss. โธ๏ธ๐ด
The Cash Squeeze: The balance sheet is under heavy fire. ๐
Less than 40% of operating profit is turning into cash, as liquidity remains trapped in slow-moving inventory.
With a