ELSH: Real Estate Land Bank and Rental Buffer Support Pullback๐ ELSH: Real Estate Land Bank and Rental Buffer Support Pullback Setup ๐๏ธ
๐งพ Shareholders and Free Float:
HCCD holds 44.54% state owned strategic stake. ๐งพ
Misr Insurance Holding Company owns 15.86% strategic stake. ๐๏ธ
Public and retail free float stands at 39.60%. ๐
๐ The Pulse:
Price ratios sit around historical average with average fundamentals. ๐
Indicators display negative signals in the short term. ๐
Volume is descending during this pullback which is a positive sign. ๐ง
Price has not broken
MCQE: Below Average Ratios With Good Liquidity On Fibonacci ๐ MCQE: Below Average Ratios With Good Liquidity On Fib Retracement ๐
๐๏ธ Fundamentals:
๐ Strengths and Catalysts:
High regional construction volume in Southern Egypt drives top-line leverage. ๐
โ ๏ธ Weaknesses and Risks:
A tight free float of 9.3% exposes retail orders to slippage. โ ๏ธ
Energy cost inflation in petcoke and coal inputs threatens operating margins. โ ๏ธ
๐งพ Shareholders and Free Float:
Al Ahly Capital Holding owns ~20.5% and Mohamed Ashraf Omar Omar holds ~18.0%. ๐งพ
State and corporate
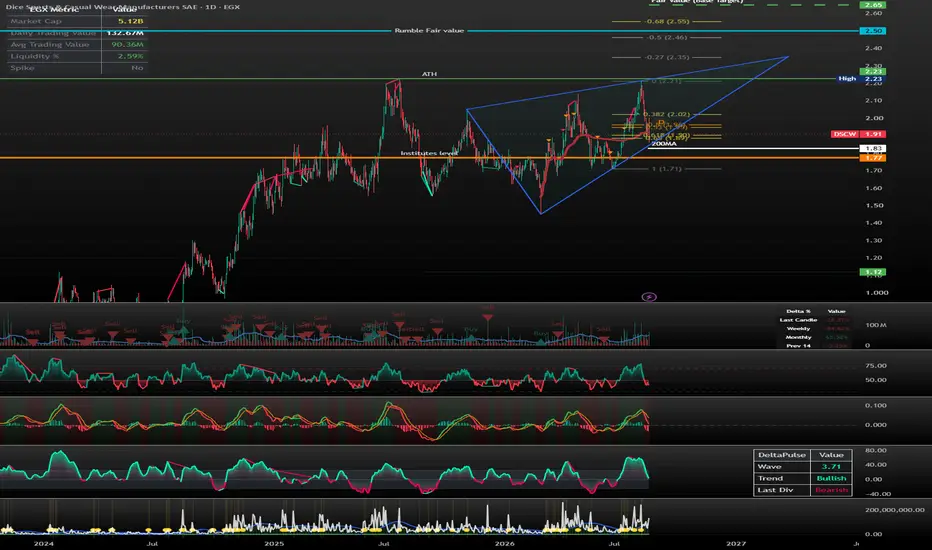
DSCW: Pullback Testing Triangle Lower Support After ATH๐ DSCW: Pullback Testing Triangle Lower Support After Reaching All-Time High ๐
๐๏ธ Fundamentals:
โ ๏ธ Weaknesses and Risks:
Severe margin compression led to a Q1 2026 net loss of EGP 159.7 million due to soaring debt service. ๐
Highly leveraged balance sheet with interest-bearing debt exceeding 48 percent of total assets. โ ๏ธ
Operating cash flow generation remains extremely thin relative to short-term maturities at 3.1 percent OCF-to-debt. ๐ธ
๐งพ Shareholders and Free Float:
Nagy Thomas and related
SCEM: Sinai Cement Pullback Presents Prime Long-Term Entry Level๐ SCEM: Sinai Cement Pullback Presents Prime Long-Term Entry Levels ๐๏ธ
๐๏ธ Fundamentals:
๐ Strengths and Catalysts:
H1 2026 consolidated net profit jumped to EGP 1.56 billion, reflecting strong pricing power. ๐
Export expansion in regional markets acts as a hard-currency hedge against EGP volatility. ๐ต
P/E ratio of 7.59x TTM presents a clear discount to sector peers alongside high ROE. ๐
โ ๏ธ Weaknesses and Risks:
High reliance on imported petcoke leaves margins exposed to global fuel price spik
GTWL: Momentum Surge Meets Stretch Valuations and Solvency Risks๐ GTWL: Momentum Surge Meets Stretch Valuations and Solvency Risks ๐งถ
๐๏ธ Fundamentals:
๐ Strengths and Catalysts:
Export focused manufacturing benefits directly from competitive EGP costs. ๐
Operational recovery is driving high trailing earnings growth. ๐
Proposed capital rights issue aims to restructure the balance sheet. ๐๏ธ
โ ๏ธ Weaknesses and Risks:
Valuation trades at a premium 26.6x P/E with high price ratios. โ ๏ธ
Fundamentals remain below average alongside poor cash flow management. ๐
Tight
MPCI: Strong Uptrend Momentum Against Regulatory Margin Pressure๐ MPCI: Strong Uptrend Momentum Against Regulatory Margin Pressure ๐
๐๏ธ Fundamentals:
๐ Strengths and Catalysts:
State backing via HoldiPharma provides durable order flow in public procurement channels. ๐๏ธ
Strong operational momentum drove TTM EPS growth up +95.1% YoY. ๐
โ ๏ธ Weaknesses and Risks:
High dependence on imported APIs creates foreign exchange friction. โ ๏ธ
Premium valuation metrics at 12.04x P/B leave little buffer for operational misses. ๐
Regulated drug price ceilings limit immedia
MCRO โ Triangle Breakout Continues Toward 1.75EGX:MCRO confirmed a bullish breakout from the descending triangle structure on the daily chart, followed by strong upward momentum and a sequence of higher highs.
The previously identified targets at 1.26, 1.30, 1.50, and 1.59 have all been reached. After testing higher levels, the stock is currently consolidating near 1.56 while remaining above the former breakout area and the rising long-term moving average.
The next challenge is the 1.59โ1.60 resistance zone. A confirmed daily close abov
KABO โ Bullish Continuation Toward 10.00 and 10.35EGX:KABO remains in a strong daily uptrend after completing a significant advance from the 6.30โ6.90 accumulation area.
The previously identified targets at 6.90, 7.20, 9.00, and 9.30 have already been reached. The current open setup was activated at 9.00, with the price now consolidating around this important breakout level.
Holding above 9.00 keeps the bullish continuation scenario valid. A confirmed daily breakout above the 9.30โ9.35 resistance zone could support another upward leg toward
IEEC: Extreme Overbought Levels and Weak Fundamentals Signal RED๐ IEEC: Extreme Overbought Levels and Weak Fundamentals Signal Warning ๐จ
๐๏ธ Fundamentals:
๐ Strengths and Catalysts:
Balance sheet recapitalized with reduced long-term debt after restructuring. ๐
Expansion of national public infrastructure projects offers bidding opportunities. ๐
โ ๏ธ Weaknesses and Risks:
Company is making operational losses with very weak fundamentals. ๐
Thin gross margins of 7.8% TTM stem from reliance on sub-contracting models. โ ๏ธ
Negative operating cash flows and high work
CCAP: Head and Shoulders Breakdown Confirmed on Double Avrg Vol๐ CCAP: Head and Shoulders Breakdown Confirmed on Double Average Volume ๐
๐๏ธ Fundamentals:
โก Strengths and Catalysts:
Massive top-line revenues exceeding EGP 135B provide strong operational leverage. ๐
Senior debt reductions at ERC decrease the overall interest burden over time. โก
โ ๏ธ Weaknesses and Risks:
A high interest-bearing debt burden creates persistent net losses at the bottom line. โ ๏ธ
Foreign exchange volatility creates risk on foreign currency debt holdings. ๐ธ
๐งพ Shareholders and Fre
NIPH: Operational Turnaround Disconnected From Extreme Valuation๐ NIPH: Operational Turnaround Disconnected From Extreme Valuation ๐งช
๐๏ธ Fundamentals:
Strengths and Catalysts:
Net profit turned around with +155% YoY growth due to price adjustments. ๐
State-backed contract security through HoldiPharma provides strong institutional positioning. ๐ข
Regulatory drug repricing in Egypt acts as a direct revenue driver. ๐
Weaknesses and Risks:
Valuation shows an extreme disconnect at 69x P/E compared to the 15x sector average. โ ๏ธ
Cash conversion remains low as capi
VLMRA: Triangle Consolidation Above 200-Day Moving Average ๐ VLMRA: Triangle Consolidation Above 200-Day Moving Average ๐
๐๏ธ Fundamentals:
Strengths and Catalysts:
Offers a high dividend yield of 7.91% backed by robust USD denominated cash flows. ๐ต
Trades at a deep valuation discount of 7.54x P/E and 1.03x P/B. ๐ท๏ธ
Gas distribution infrastructure expansion and subsidiary dividends serve as core growth catalysts. ๐
Weaknesses and Risks:
High stock beta of 1.74 creates wider price swings during general market downturns. โ ๏ธ
Revenue remains exposed to com
COMI: Leading Private Banking Franchise Consolidates Below ATH ๐ COMI: Leading Private Banking Franchise Consolidates Below ATH ๐๏ธ
๐๏ธ Fundamentals:
Strengths and Catalysts:
Leading Egyptian private bank with top tier 34.2% ROE and rapid digital adoption. ๐
High local interest rates and strong treasury yields drive core interest revenue. ๐ต
Cross border operations, East Africa expansion, and the yomo platform act as growth engines. ๐
Weaknesses and Risks:
Balance sheet shows heavy concentration in domestic treasury bills and bonds. โ ๏ธ
Foreign portfolio capi
MICH: Zero-Debt Chlor-Alkali Leader Consolidating Near ATH ๐ MICH: Zero-Debt Chlor-Alkali Leader Consolidating Near ATH ๐งช
๐๏ธ Fundamentals:
Strengths and Catalysts:
Dominant producer of caustic soda and chlorine with 47%+ net margins and exceptional balance sheet showing zero debt and EGP 646.6 mn net cash. ๐
Plant modernization and capacity expansion expected in H2 2026/2027 serve as key catalysts. ๐
Weaknesses and Risks:
Product concentration exposes revenue directly to cyclical global chlor-alkali price downturns and local power subsidy cuts. โ ๏ธ
Net
TMGH: Sideways Consolidation & BB Squeeze Signal Impending Break
๐ TMGH: Sideways Consolidation & Bollinger Squeeze Signal Impending Breakout ๐
๐๏ธ Fundamentals:
Strengths and Catalysts:
Unrivaled sales backlog exceeding EGP 350+ billion secures multi-year revenue visibility. ๐
High-margin recurring income stems from USD-denominated luxury hotel portfolio. ๐จ
Regional expansion via Saudi Arabia Banan and SouthMed unlocks new buyer demographics. ๐
Weaknesses and Risks:
Low cash dividend yield results from heavy capital reinvestment. โ ๏ธ
Inflationary pressures
MASR: Strong Fundamentals Support Uptrend Channel Pullback ๐ MASR: Strong Fundamentals Support Uptrend Channel Pullback ๐
๐๏ธ Fundamentals:
Strengths and Catalysts:
Massive low-cost land bank in East Cairo drives industry-leading margins. ๐
Accelerating sales bookings and unbilled receivables provide high earnings visibility. ๐
Geographical expansion and recurring income hospitality assets support growth. ๐จ
Weaknesses and Risks:
Raw material cost inflation impacts construction gross margins. โ ๏ธ
High prevailing inflation exerts purchasing power pressur
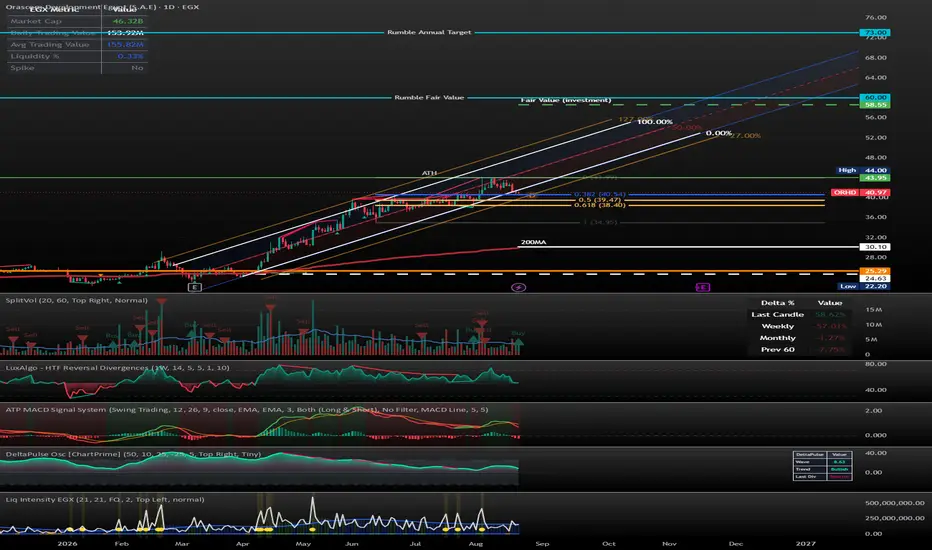
ORHD: Operational Strength Meets Technical Channel Setup ๐ ORHD: Operational Strength Meets Technical Channel Setup ๐
๐๏ธ Fundamentals:
Strengths and Catalysts:
Extensive hotel portfolio with over 2,500 keys in El Gouna and Red Sea hubs acts as a hard-currency revenue hedge. ๐ข
Massive land bank acquired at low historical cost offers a long-term development runway. ๐บ๏ธ
Acceleration of expansion and deliveries at 'O West' in West Cairo serves as a core driver for Q3/Q4 cash collections. ๐๏ธ
Below-average price-to-earnings valuation pairs with healthy prof
PHDC: Triangle Consolidation Before Major Breakout ๐ PHDC: Triangle Consolidation Signals Potential Trend Continuation Above 15.8 ๐
๐๏ธ Fundamentals:
Strengths and Catalysts:
Historic presales momentum exceeded EGP 180 billion in 9M-2025. ๐
Geographical diversification expands into high-margin North Coast developments. ๐๏ธ
Regional expansion extends footprint into the UAE. ๐
Strategic land plots acquired in New Administrative Capital and Sheikh Zayed. ๐บ๏ธ
Weaknesses and Risks:
High debt-to-equity ratio of 1.58x increases rate exposure. โ ๏ธ
Elevate
REMCO โ 1H Technical AnalysisBased on the chart, REMCO is approaching a potentially important breakout from a multi-month contracting structure. The setup is bullish, but the key is whether price can convert the 4.20โ4.00 EGP entry area into support.
๐ Pattern / Structure
The chart appears to be forming a contracting triangle / corrective structure after the sharp move to point A (~4.56).
The sequence marked A โ B โ C โ D shows decreasing volatility and converging trendlines. The current price around 4.20 is approaching
EHDREgyptians Housing Development & Reconstruction โ 1H Technical Analysis
Based strictly on the TradingView chart provided, the structure is bullish, but price is currently testing an important decision area around 2.89โ2.95 EGP.
๐ Market Structure
Current price: ~2.96 EGP
The chart shows a sequence of higher lows and higher highs, indicating improving bullish structure.
Price has broken above the 2.89โ2.95 EGP resistance area and is now trading just above it.
The rising green trendline is acting
GBCO: Neckline Break Signals Pullback Toward 200 MA๐ GBCO: Neckline Breakdown Signals Pullback Toward 200 MA Within Long-Term Uptrend โ ๏ธ
๐๏ธ Fundamentals:
Leading Egyptian passenger vehicle assembler and regional distributor with strong market share. ๐
Good fundamentals with above-average, reasonable valuation price ratios. ๐
Sharia status: Non-Compliant due to interest-bearing debt exceeding limits and conventional financial services operations. โ ๏ธ
๐ The Pulse:
Primary multi-year ascending trend channel remains intact. ๐
Indicators are showing
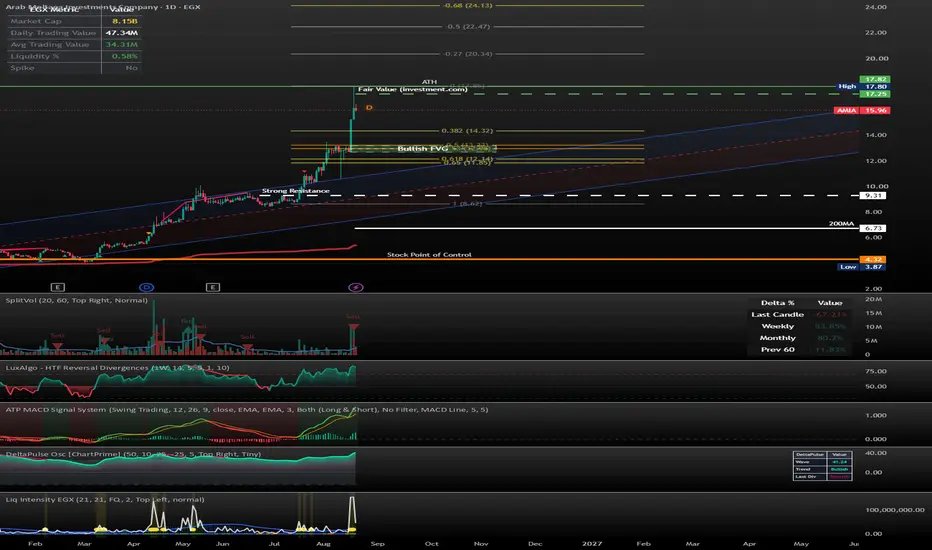
AMIA: Valuation Risk Demands Caution Ahead ๐ AMIA: Valuation Risk Demands Caution Ahead โ ๏ธ
๐๏ธ Fundamentals:
Arab Moltaqa Investments demonstrates solid operational growth with TTM EPS expanding +227.2% YoY to EGP 0.87 and a high ROE of 30.9% outperforming the sector.
However, high ownership concentration limits free float to ~17.8%, while interest rate volatility poses risks to subsidiary borrowing costs and transaction volumes.
Potential catalysts include unlocking asset values through subsidiary IPOs or partial divestments in H2 202
PHDC: Solid Fundamentals, Awaiting Breakout ๐ PHDC: Solid Fundamentals, Awaiting Breakout ๐๏ธ
๐๏ธ Fundamental Review:
๐ Business Quality:
Palm Hills Development (PHDC) is a major Egyptian real estate developer with a massive land bank, backlog deliveries, Ras Al Hikma coastal projects, and regional UAE expansion.
๐ฐ Financial Strength:
Great fundamentals with moderate valuation ratios, though leverage is high (~158% Debt/Equity) due to construction financing.
๐ The Pulse:
Structure is very bullish, consolidating near major resistance. ๐
GSSC: Extremely Expensive, Breakout Confirmation Required ๐ GSSC: Extremely Expensive, Breakout Confirmation Required โ ๏ธ
๐๏ธ Fundamentals:
GSSC benefits from strategic port-silo assets and a strong position in Egypt's grain-import infrastructure. ๐พ
However, cash flow remains very weak and valuation ratios are extremely expensive. โ ๏ธ
Sharia status: Compliant. ๐ข
๐ The Pulse:
GSSC has a very tightly held float, which can create sharp price expansions but also increases volatility and liquidity risk. โ ๏ธ
I would only consider a trade after two consecutive