SDTI โ 501% Leverage vs. The 66.30 ATH TargetSDTI โ 501% Leverage vs. The 66.30 ATH Target ๐๐ฅ
The Reality: A "Debt-Heavy" recovery play! ๐๏ธโ ๏ธ
While the stock has surged 141% in 6 months, the fundamentals are on thin ice.
EBIT is positive (~EGP 245M), but Operating Cash Flow only covers 65% of that profit.
The rest? Trapped in receivables and accruals. ๐ธ๐ณ๏ธ
The Insolvency Risk: Debt is EGP 1.65B against tiny equity of EGP 329M a staggering 501% Debt-to-Equity ratio! ๐โ
Operating cash flow only covers 10.3% of total debt.
One bad touri
SAUD โ Market Share GrabSAUD โ Market Share Grab ๐๐ฆ
โข The Reality: Al Baraka is a growth monster hiding in a value stock's body! ๐น๐
Total assets exploded by EGP 19B in a year, fueled by a 15% jump in deposits! ๐
With an ROE of 28.4%, itโs outperforming the sector, yet it still trades at a massive discount compared to giants like CIB. ๐ธ๐ฆ
โข The Cash Quality: No "Paper Profits" here! ๐๐ซ
93% of income comes from core banking (Murabaha/Musharaka), meaning itโs real cash, not accounting tricks! ๐ฐ๐ฅ
Liquidity is surging
ELEC โ Record EBIT, Zero Cash & Massive Debt ELEC โ Record EBIT, Zero Cash & Massive Debt ๐๐
โข The Reality: ELEC is an industrial giant with a "Liquidity Crisis." While EBIT is at record levels, the cash conversion is terrible only 38 piasters of every EGP 1.00 profit actually hit the bank.
The rest is stuck in a massive EGP 1.9B receivables hole, signaling a major collection lag from mega-projects. ๐ณ๏ธ๐ธ
โข The Debt Trap: With EGP 4.8B in liabilities and a staggering 299% Debt-to-Equity ratio, ELEC is drowning in leverage. ๐โ
In Egypt'
ELSH โ Bloated Inventory & Bearish TechnicalsELSH โ Bloated Inventory & Bearish Technicals ๐๐๏ธ
โข The Reality: A major "Relative Strength" laggard. ๐ข While the rest of the sector is booming, ELSHโs net profit tanked 23% (EGP 64.7M down from 84.4M).
With inventory bloating in projects like "Gardenia Sol" and capital tied up in slow-moving assets, the company is losing its competitive edge. ๐งฑ๐ฉ
โข The Valuation Trap: Don't be fooled by the 11.6x P/E. ๐คก
DCF models suggest an intrinsic value as low as 6.3 EGP based on future cash flows.
You
AJWA โ Retail Power vs. Cash Flow Reality AJWA โ Retail Power vs. Cash Flow Reality ๐๐ฅ
โข The Reality: This is a classic "Paper Profit" trap. ๐๐ณ๏ธ
While the ledger shows a shift to a ~EGP 37M profit, the cash flow is screaming the opposite. Cash from Operations fell by over 400%, meaning the company is essentially subsidizing its growth with reserves rather than generating actual liquidity. ๐ธ๐จ
โข The Warning: Receivables are ballooning. ๐ AJWA is selling products but failing to collect the cash fast enough, leading to a negative cash co
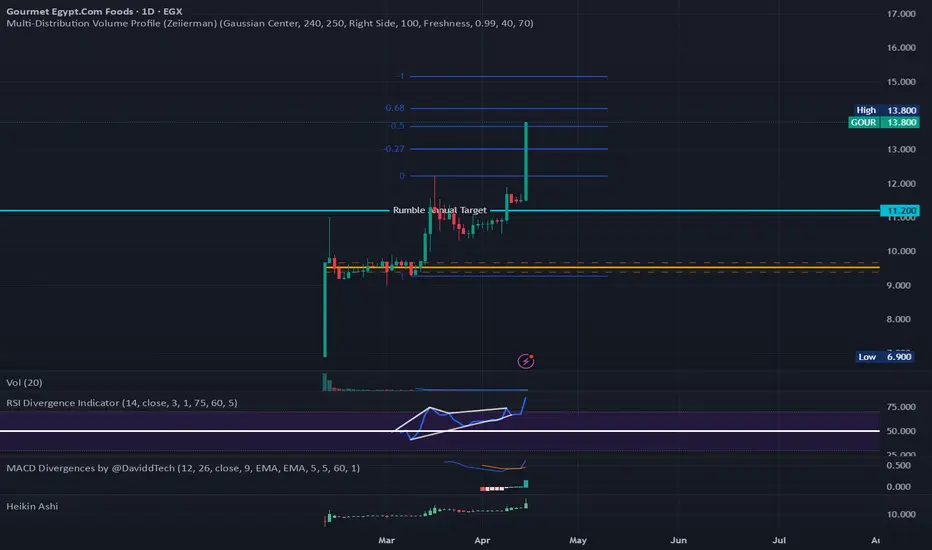
GOUR institutional FOMO. The Reality: The stock is absolutely on fire! ๐ฅ
Crossing 13.80 EGP marks a massive breakout, leaving the IPO price of 6.90 far in the rearview mirror (a 100% gain since Feb 2026!). ๐๏ธ๐จ
โข The P/E Adjustment: At the new price of 13.80, the Price-to-Earnings ratio has shifted to 26.14x (based on FY2025 earnings of 211.2M EGP and 400M shares). ๐ข๐
While this is "Premium Pricing," it is backed by an explosive 56% profit growth rate. ๐๐ฐ
As long as it holds above 13.00, the vertical momentum is th
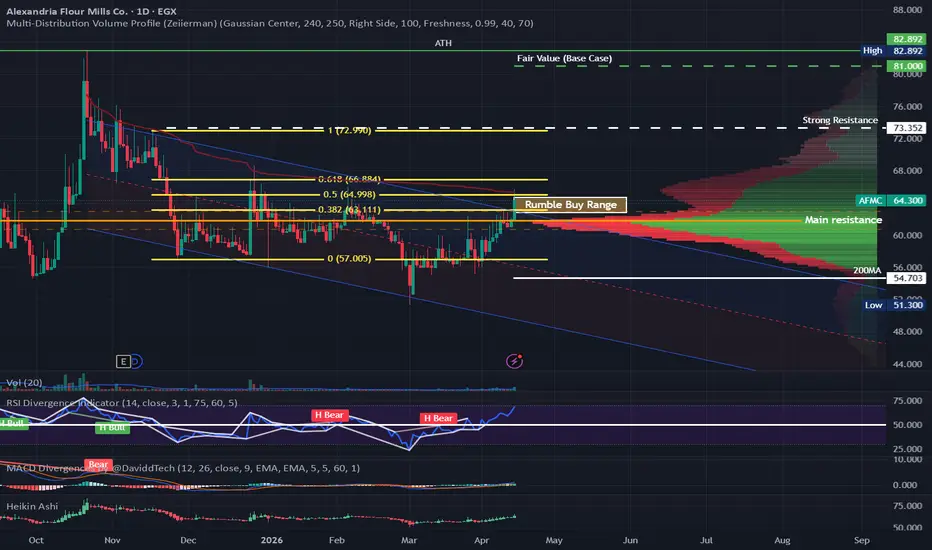
AFMC โ Defensive Anchor Breaking FreeAFMC (Alexandria Flour Mills) ๐โ๏ธ
The Reality: The "Income Anchor" is moving! โ AFMC is a defensive powerhouse with a Beta of 0.44, meaning itโs where capital hides during market storms. ๐ก๏ธ
However, its 91.1% Payout Ratio is a double-edged sword investors love the dividends, but the lack of reinvestment in infrastructure has kept revenue growth relatively flat. ๐๐ฆ
The Breakout: The technical "hibernation" is over! ๐ปโก๏ธ๐
Todayโs surge above the 61.50 resistance, backed by EGP 23M in volume (a
CLHO โ 50% Capacity Surge Meets Breakout Setup! CLHO โ 50% Capacity Surge Meets Breakout Setup! ๐๐ฅ
Fundamental Analysis:
Cleopatra (CLHO) is shifting gears! โ๏ธ Adding 440 beds in 2026โa 50% capacity surge! ๐ฅ๐ Supported by EGP 3.5 Billion in East Cairo & Sky Hospital expansions! ๐๏ธ๐ฐ
Interest expenses from Q4-2025 are a hurdle, but operational efficiency is winning! ๐ Procurement costs are down to 23%! ๐โจ
Revenue already crossed EGP 1B early this year! ๐ค๐ฅ
This is a leader in a breakout setup! ๐ก๏ธ๐
Technical Analysis:
Long-term uptrend is in
EGTS โ The Sahl Hasheesh Anchor: Recovery or Bubble?EGTS โ The Sahl Hasheesh Anchor: Recovery or Bubble? ๐๐๏ธ
The Reality: EGTS is currently the definition of a Speculative Divergence.
While the company reported a massive turnaround in late 2025 with EGP 1.05B in net profit, the stock price is heavily decoupled from its operational reality.
At ~9.18 EGP, it is trading nearly 200% above its estimated cash flow value of 3.06 EGP. ๐ธ๐ณ๏ธ
The Strategy: This is a "Traderโs Stock," not a "Value Play."
The price action is driven by land dispute resoluti
CSAG (Canal Shipping Agencies): The Suez Dividend Engine CSAG (Canal Shipping Agencies): The Suez Dividend Engine ๐ข๐ฐ
The Cash Cow: The company's greatest strength its liquidity.
CSAG is currently targeting a net profit of EGP 970M for the upcoming fiscal year.
Holding nearly a billion in cash with zero debt makes it a "fortress" on the balance sheet, ensuring it remains a top-tier dividend payer (currently yielding roughly 10%). ๐ฆ๐ต
The Subsidiary Safety Net: Its heavy reliance on dividends from its stakes in Damietta (DCHC) and Port Said (PSCCH) c
SCEM (Sinai Cement): The Superior Sleeper SCEM (Sinai Cement): The Superior Sleeper ๐๏ธ๐
The Balance Sheet Power: "Clean Slate" here.
The sale of the 25.4% stake in Sinai White Portland Cement for roughly โฌ30M (~EGP 1.5B+) transformed SCEM's financials.
This massive cash injection, combined with an incredibly low debt-to-equity ratio, makes it one of the most structurally sound industrial players on the EGX. ๐ฆ๐งผ
The Turnaround: This isn't just about cash; it's about performance.
Annual revenue now exceeds EGP 9.0B, and 9M-2025 net pr
MPCI (Memphis Pharma): The State-Owned Momentum PlayMPCI (Memphis Pharma): The State-Owned Momentum Play ๐โ
The Index Gap: Even though the industry is "halal," MPCI remains outside the EGX33 Shariah Index.
As with many state-owned entities, the lack of a dedicated Sharia board or specific debt-ratio thresholds keeps it off the official list. โช๏ธ๐ซ
The Cash Disconnect: While the stock has seen massive price appreciation recently, the disconnect between reported earnings and actual Operating Cash Flow is a major vulnerability. In this market, when
ADIB (Abu Dhabi Islamic Bank - Egypt): The Sharia Anchor ADIB (Abu Dhabi Islamic Bank - Egypt): The Sharia Anchor ๐ฆ๐ก๏ธ
The Value Thesis: The "Golden Boy" of the index.
A P/E < 5x while delivering +40% profit growth is an anomaly usually reserved for deep-value gems.
It is the definition of a "Growth at a Reasonable Price" (GARP) play. ๐๐
The Distribution Warning: The declining Volume MA since the All-Time High (ATH) is a classic institutional signal.
It suggests "Quiet Distribution" where big players are offloading shares to retail without crashin
AMER (Amer Group): The Retail Trap AMER (Amer Group): The Retail Trap ๐๏ธ๐ชค
The Headline Illusion: That 139% profit leap is a ghost.
With negative operating cash flow, the company is effectively losing money on its actual day-to-day business, regardless of what the accounting entries say.
Headlines are for retail; cash flow is for traders. ๐ธ๐
The Debt Weight: Serving a heavy debt load while the business isn't generating liquid cash is a recipe for a liquidity crunch.
This is exactly why the "floor is soft." โ ๏ธ๐๏ธ
The Technical
DOMT: Margin Pressure & Debt WeightDOMT: Margin Pressure & Debt Weight ๐ง๐
The Marketing War: A 46% spike in marketing costs is a double-edged sword.
It shows Domty is desperately defending its territory against OLFI and JUFO, but itโs a "race to the bottom" that is cannibalizing their profit margins. ๐ธโ๏ธ
The Cash Crunch: This is the biggest red flag. Generating EGP 9.39B in sales but only holding EGP 110M in operating cash flow is a massive disconnect. It suggests that while they are moving product, they are struggling to coll
EGAL: Riding the Global Metal Wave EGAL: Riding the Global Metal Wave ๐๏ธ๐
The Inventory Edge: In a commodity super-cycle, holding massive Inventory is a strategic advantage.
With global aluminum prices surging to four-year highs (hitting $3,571/ton on the LME this April due to supply disruptions in the Strait of Hormuz).
That "stockpiled" profit is effectively a massive unrealized gain that will hit the cash books as sales finalize. ๐ญ๐ฐ
The Technical Roadmap:
The Trend: Still locked in a beautiful uptrend channel.
The 3-week
HELI (Heliopolis Housing): Asset Wealth vs. Cash Reality HELI (Heliopolis Housing): Asset Wealth vs. Cash Reality ๐๏ธ๐ชค
The Disconnect: The "Earnings Trap."
High reported profits without matching Operating Cash Flow usually mean the gains are on paper deferred payments from land auctions or asset revaluations.
In a high-interest environment, "Cash is King," and paper profits can't pay the bills. ๐ธ๐
The Technical Roadmap:
The Trend: Still riding a solid uptrend channel, but the momentum is being tested. ๐
Support Level 1 (The White Line): This is ou
ALCN (Alexandria Containers): Fundamental Giant vs. Technical WaALCN (Alexandria Containers): Fundamental Giant vs. Technical Warning ๐ขโ
The Monopoly Edge: this is a state-adjacent monopoly.
Its fundamental strength is undeniable, but the stock is currently fighting a heavy technical "tide." ๐๐๏ธ
The Technical Red Flags:
Bearish Divergence: The RSI is showing a clear divergence at the All-Time Highs (ATH), suggesting the momentum is gasping for air even as prices look high. ๐๐
Double Top & Trend Break: The breakdown of the primary uptrend line and the co
DSCW (Dice Sport & Casual Wear): The Retail Rally DSCW (Dice Sport & Casual Wear): The Retail Rally ๐งต๐
The Euphoria Factor: The breakout at 1.87 was fueled by individual traders, leaving the stock vulnerable to "profit-taking" from institutions that are staying away due to the company's leverage. ๐ข๐
The Debt Burden: The Reality: While the top line looks decent, the Total Debt-to-Equity ratio (~252%) is a massive weight.
In a high-interest environment, servicing this debt eats into the margins, which is exactly why "big money" is hesitant. โ ๏ธ
AMIA (Arab Moltaqa Investments): The Quality TrapAMIA (Arab Moltaqa Investments): The Quality Trap ๐ธ๏ธ๐
The Profit Illusion: While the headlines scream growth, a massive chunk of that is non-operational.
Relying on "revaluation of investments" and "interest income" rather than core fees means the business isn't actually getting better at what it does.
it's just benefiting from accounting adjustments and high interest rates. โ ๏ธ๐ชค
The Cash Gap: The high level of non-cash earnings is a major red flag.
If the profit isn't translating into operat