Long
Will SNDK go down to $1,450 GEX magnet level this week?SNDK is currently trading near $1,531, while this week’s gamma-exposure snapshot shows the largest negative GEX concentration at the $1,450 strike, with estimated net GEX of approximately -$22.1 million.
That places the $1,450 level roughly 5% below the current price.
The main question is whether $1,450 could attract price as expiration approaches—or whether the negative gamma surrounding this strike makes it more likely to behave as an acceleration and volatility zone.
Negative gamma should not automatically be interpreted as support or a guaranteed price magnet. In a negative-gamma environment, dealer hedging may reinforce the direction of the underlying move. If SNDK weakens and breaks below the nearby $1,500 area, hedging flows could potentially contribute to a faster move toward $1,450.
Possible scenarios:
• Above $1,500: Price remains separated from the largest negative-GEX concentration, reducing the immediate probability of a $1,450 test.
• Below $1,500: The distance to $1,450 narrows, making the large GEX concentration increasingly relevant.
• Near $1,450: Watch whether price stabilizes, rejects the level, or accelerates through it. The reaction may be more useful than assuming the strike will automatically provide support.
GEX levels are estimates based on options positioning and assumptions about dealer exposure. They can change as contracts are opened, closed, or approach expiration. For that reason, the $1,450 level is best treated as a potential reaction zone—not a guaranteed target.
For traders who incorporate GEX into their process:
1. Would $1,450 be classified as a magnet or an acceleration level?
2. Is a break below $1,500 necessary before considering $1,450 relevant?
3. How often do large negative-GEX strikes attract price compared with positive-GEX strikes?
4. What confirmation—volume, implied volatility, price action, or time to expiration—is most useful?
This analysis is educational and does not constitute financial advice.
 Short
 Long
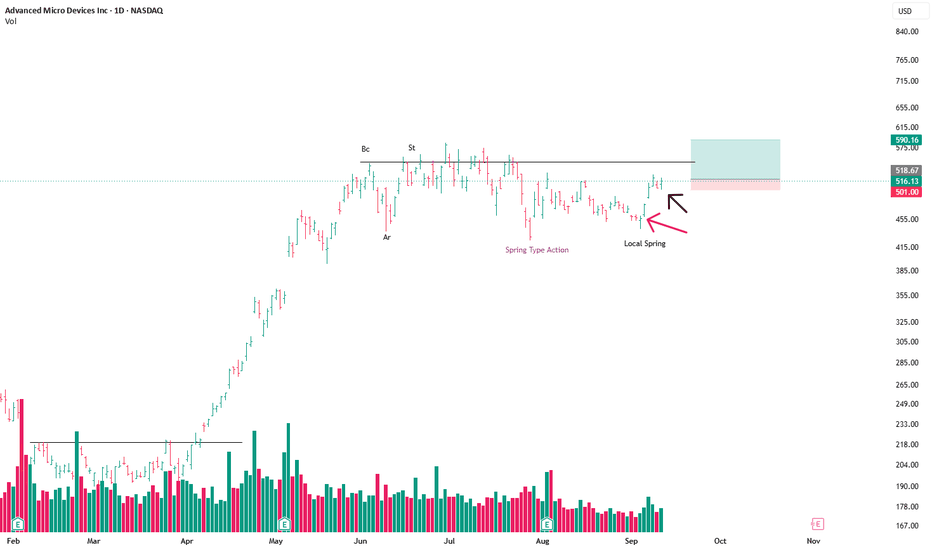
Intel's Bold Rebirth: AI, Chips and Global PowerIntel faces a pivotal transformation in 2026. Global tech demands force radical shifts in silicon manufacturing. Artificial intelligence drives unprecedented semiconductor growth. Intel must adapt to survive. The global economy relies on robust supply chains. Macroeconomic pressures squeeze legacy hardware producers. Memory prices have risen sharply, with SK Group Chairman Chey Tae-won describing them as abnormally high and calling for supply expansion. Data centers devour available global silicon output. This creates immense economic friction. Intel seeks dominance in this new paradigm. The company pivots increasingly from monolithic processors to agile chiplets. This strategic shift redefines global high-tech industries.
Geopolitics and Geostrategy
Semiconductors dictate modern geopolitical leverage. The US government aggressively secures domestic supply chains, and last year took a 10% equity stake in Intel itself. Commerce Secretary Howard Lutnick has publicly pressed foreign memory giants to build locally, telling an audience at Micron's New York fab in July that he wants to bring Samsung Electronics and SK Hynix to the United States to build production facilities. Intel broke ground on its New Albany, Ohio campus in 2022 with an initial $28 billion commitment and a longer-term vision approaching $100 billion across as many as eight fabs. After missing its original 2025 target, Intel pushed first production to 2030 or 2031, five to six years later than planned. The site remains strategic, designed to support 14A and future nodes. Korea JoongAng Daily reported in July that SK Hynix was in talks to acquire the campus. SK Hynix firmly denied these specific buyout claims in a Korea Exchange filing. However, Semafor subsequently reported early-stage discussions about an operational partnership, so strategic collaboration remains viable. SK Hynix is testing integration of its HBM with Intel's EMIB-based 2.5D packaging technology, and Samsung and Micron are assessing EMIB as well, reflecting memory makers' push to diversify away from tight TSMC CoWoS supply. Intel leverages government support aggressively. Geostrategy now revolves around localized silicon independence.
Business Models and Economics
Intel embraces a radically new business model. The company separates its foundry operations from chip design. This bold move attracts external clients, and Intel has onboarded marquee customers including Apple and SpaceX under chief executive Lip-Bu Tan. High capital expenditures challenge traditional profit margins. Building advanced fabs costs tens of billions. Intel Foundry lost $10.3 billion in 2025 on $17.8 billion of revenue, followed by a further $2.4 billion loss in the first quarter of 2026. The Arizona Fab 52 has begun mass production of 18A nodes. Intel pushes the Ohio facility launch to 2030. Joint investment programs spread massive financial risks. Brookfield partnered with Intel for Arizona expansions. Intel monetizes its advanced packaging capabilities effectively. Supplying ecosystem partners diversifies revenue streams.
Company Culture and Leadership
Management prioritizes pragmatic adaptability over rigid tradition. Decades of monolithic CPU dominance fostered complacency. Chief executive Lip-Bu Tan, appointed in 2025, ruthlessly targets high-growth AI sectors. The corporate culture now emphasizes rapid iteration. Teams race to bridge previous technological gaps. Intel acknowledges its late entry into AI hardware. Leaders implement an aggressive recovery strategy that has included large-scale layoffs and capital expenditure cuts. This requires immense organizational resilience. Managers foster diverse industry collaboration initiatives, and Intel hired Lee Seok-hee, SK Hynix's former chief executive, in June to help run its packaging business. Intel builds partnerships rather than fighting isolationist battles. This cultural evolution ensures long-term survival.
Technology, High Tech and Innovation
Innovation centers on heterogeneous compute architectures. Intel moves steadily away from traditional monolithic chip designs. Advanced packaging technology connects specialized silicon chiplets. Engineers optimize hardware specifically for large language models. New chips feature efficient SoftMax calculations for transformers. Speculative kernel execution accelerates chiplet GPU performance. Early exit mechanisms speed up neural inference. Sparse neural network inference reduces required computational power. Hardware compression of sparse matrices eliminates wasted operations. These innovations make AI deployments significantly cheaper.
Cybersecurity and Patent Analysis
Intel's patent portfolio reveals clear strategic priorities. Advanced packaging dominates recent filings, consistent with the company's chiplet and EMIB strategy. AI accelerator filings surged during 2025. Cybersecurity remains a foundational pillar for enterprise clients. The portfolio shows a deliberate security evolution. Intel transitioned from client-side secure enclaves. The focus shifted to cloud-scale confidential computing. Trust Domain Extensions now secure shared cloud environments. Hardware encryption protects critical AI matrix accelerators.
Science and The Pharmaceutical Industry
Intel silicon supports breakthroughs in modern medical science. The Intel Pharma Analytics Platform, developed with contract research organization ICON under an agreement first announced in 2018, captures sensor data from remote study subjects. Edge-to-cloud AI quantifies therapy impacts objectively. This automation aims to reduce clinical trial costs. High-quality data accelerates new drug market delivery. A notable personal link runs through the leadership. Lip-Bu Tan, Intel's chief executive, serves as board chairman of Greenstone Biosciences, the Palo Alto company combining human iPSC biology with AI-driven drug discovery. Greenstone has announced collaborations with NVIDIA and with Illumina rather than with Intel. Silicon innovation nonetheless underpins computational drug discovery across the sector.  Long
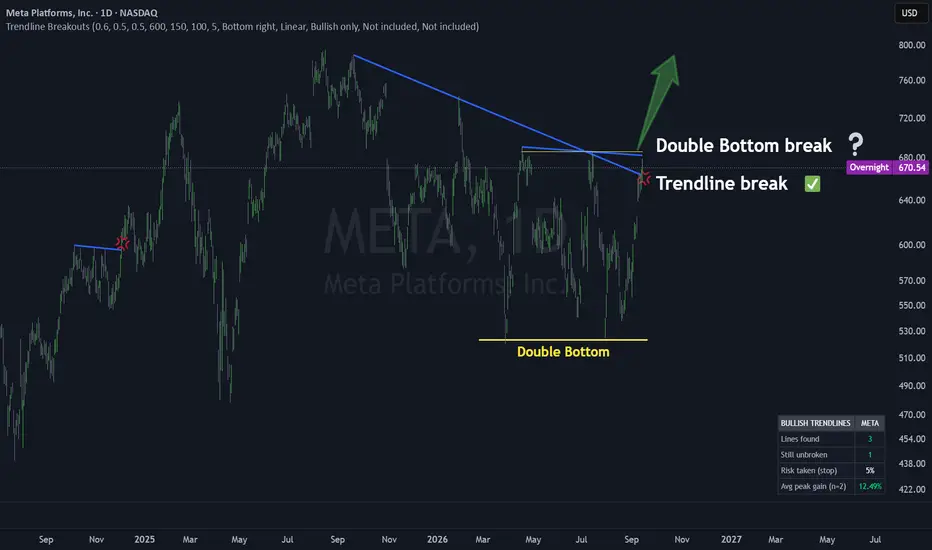
A New Trendline Break in META, With a Double Bottom Next to ItA New Trendline Break in NASDAQ:META , With a Double Bottom Next to It
There are two things I love in this chart, and they are happening at the same time.
The first is the blue line. Since last autumn, every rally in META stopped there. Buyers pushed, sellers were waiting, price turned back. On Monday, price closed above the Trendline.
A trendline is a queue of sellers. Each time price touched the line, someone in the queue sold. On Monday the queue ran out and that's a short term bull signal.
The second thing is the shape under the line. Two lows at about the same level, a bounce in the middle. A double bottom. The neckline is the yellow line near $688. Price is sitting right under it.
Why I care about Monday
Most days on a chart are noise. The day a trendline breaks is not a normal day. When a line like this one gives way, the next weeks are, on average, much better than the weeks that follow any random day. How much better, with the sample size and the bad cases, is in a study I will publish soon here.
To properly find trendlines and avoid drawing trendlines with different criteria everyday, I built the indicator you see here. It finds these lines by itself and marks the break. No drawing, no opinion.
It already happened once on this chart
Scroll left to late 2025. META broke a trendline of the same kind. What followed was a rally of about 20% . One example proves nothing. But it shows you what the setup looks like when it works.
The Chart
The level I watch next is the yellow line near $688. If price closes above it, the double bottom is complete and the two signals agree. Above that, the last area where sellers showed up in size is near $800. That is a reference, not a target. Below, the blue line is now the level that has to hold.
The full trendline statistics are shared on my profile.  Long

You can see Bear thereTechnical Analysis — ADBE (Daily TF)
The chart shows a clear short-term bearish structure. Price has been making lower highs and is currently showing rejection after the recent retracement.
1. Bearish impulse
Price dropped sharply from around $275–276 toward $250.
This created strong downward momentum and established the current bearish structure.
The large bearish candles indicate that sellers were dominant during the initial move.
2. Current upward move = retracement
After reaching around $250, price bounced strongly toward $264–265.
However, the rebound has not broken the previous major high around $275–276.
Therefore, technically, this can be interpreted as a retracement within the larger bearish move, rather than a confirmed trend reversal.
3. Rejection around $264–265
Price reached approximately $264–265 and was immediately followed by a bearish candle.
This indicates selling pressure appearing at the retracement area.
The inability to hold above $260–265 strengthens the bearish interpretation.
4. Important levels
$264–265: immediate resistance / retracement rejection area
$260: important short-term level
$252–250: previous support / recent low
$240–236: potential downside areas if $250 breaks
Bearish scenario
If ADBE continues to trade below the $264–265 resistance zone, the current structure remains bearish. A break below $250 would provide stronger technical confirmation that sellers are attempting to extend the downward move.
The projected arrow toward $240–236 represents a potential continuation target, not a guaranteed destination.
ADBE remains technically bearish on the Daily timeframe. The recent upward movement from the $250 area appears to be a retracement rather than a confirmed trend reversal. Price rallied toward $264–265 but failed to sustain the recovery and faced clear rejection. The lower-high structure remains intact, while the previous bearish impulse continues to dominate price action. As long as price remains below the $264–265 resistance zone, the bearish structure remains valid. A break below $250 could open the way toward lower support levels around $240–236. Therefore, the current upside movement can be viewed as a retracement within the broader bearish structure rather than a confirmed bullish reversal.
TRADE at your own risk. This is only personal opinion and not financial advice.  Short

 Long
 Long
Cloudflare New High: AI Safety Threat Turns Into Growth Engine?Cloudflare (NET) has become one of the strongest names in software and cybersecurity. On September 14, the stock surged 7.8% to $330.36 and touched $334.60 intraday, extending a sharp September rally.
The immediate catalyst is a broader reassessment of which companies could benefit from the next phase of artificial intelligence. But Cloudflare’s rally is about more than short-term rotation. The company increasingly sits at the intersection of AI agents, internet infrastructure, cybersecurity and machine-generated traffic.
The key question is whether that strategic position can support a valuation that has already become extremely demanding.
AI Is Becoming a Tailwind Rather Than a Threat
For much of the AI boom, software companies faced a difficult question: if AI can automate workflows, write code and replace parts of traditional software, will existing platforms eventually lose pricing power?
Cloudflare presents a different case. As AI models and autonomous agents generate more internet traffic, the infrastructure required to identify, secure, route and control that traffic becomes more important.
A recent partnership with OpenAI highlights this shift. On September 3, Cloudflare announced Vulnerability Discovery and Remediation, a security service using OpenAI Daybreak models, including GPT-5.6 Cyber. The system combines AI-based code investigation with real-time information from Cloudflare’s global network.
That gives Cloudflare an interesting position in the AI ecosystem. It does not need to compete directly with frontier model developers. Instead, it can provide the security and network layer through which increasingly autonomous software operates.
Cloudflare is also experimenting with new ways to monetize AI traffic. Its Pay Per Crawl system allows website owners to charge AI crawlers for access to their content. Although the product remains in beta, the strategic direction is clear: Cloudflare wants to become an intermediary between AI systems and the open internet.
Growth Is Accelerating — But Valuation Is the Main Risk
The AI narrative is supported by improving fundamentals.
Cloudflare generated $696.1 million in second-quarter revenue, up 36% year over year. Current remaining performance obligations grew 35%, while management raised full-year 2026 revenue guidance to $2.864-$2.870 billion.
That acceleration matters. Cloudflare spent several years trading at a premium while revenue growth gradually slowed. A return toward the mid-30% range strengthens the argument that AI, security and developer infrastructure are creating another growth cycle.
The problem is that investors are already paying heavily for that scenario.
With the stock around $330, Cloudflare’s equity value is approaching $120 billion. Against roughly $2.87 billion of expected 2026 revenue, the company is trading at around 40 times current-year sales.
Even on non-GAAP earnings, the valuation remains exceptionally high.
The market is therefore pricing Cloudflare as more than a fast-growing cybersecurity company. Investors are effectively assuming it can become a critical infrastructure layer for the AI-driven internet while sustaining very high growth for years.
That may eventually prove correct, but the margin for disappointment is now small. Strong results alone may not be enough. Revenue growth, large-customer expansion and guidance will increasingly need to exceed already elevated expectations.
After the Breakout, What Should Traders Watch?
Technically, NET has entered price-discovery territory.
The first key level is $334-$335, around the latest intraday high. A clean breakout above this area would confirm that buyers remain willing to chase the stock after its rapid September move.
Below that, $315-$320 is the first important support zone. A pullback into this area would still be consistent with a strong trend.
The more important level is $300-$305. As long as NET remains above $300, the broader breakout structure stays intact and weakness can still be viewed as consolidation rather than trend failure.
A decisive move below $300 would change the setup. It would suggest that the recent AI-security revaluation moved too quickly and could expose the stock to a deeper retracement.
Cloudflare therefore presents a clear tension: fundamental momentum is improving at the same time valuation risk is becoming more extreme.
AI may be expanding Cloudflare’s addressable market rather than disrupting it, which helps explain the recent re-rating. But with NET near record highs and trading around 40 times expected 2026 sales, the next leg higher will require continued execution.
From here, the fundamentals need to catch up with the price.  Long

 Long
 Short

 Short
How Far Could Intel Stock Fall After Quadrupling in a year?Intel (INTC) has delivered one of the more dramatic turnarounds in the market over the past year, but the stock’s recent pullback has raised a difficult question: after such a powerful run, how much of those gains could a broader market shock take back? The answer matters because Intel has historically fallen harder than the S&P 500 when shocks hit, and its current valuation and trading level leave plenty of room for volatility.
Intel stock fell 5.6% on September 10 and now trades near $100. That price is about 29% below its 52-week high. Even after that decline, however, the shares have still returned 310.5% over the past year. In other words, anyone who bought a year ago has more than quadrupled their money, despite the recent weakness. The central issue is not whether Intel has been a winning stock — it clearly has — but how much of that extraordinary gain could be erased if the market enters another period of stress.
Why Is Intel Stock Off Its High?
The latest drop is not necessarily a verdict on the business. Even after falling 5.6% on September 10, Intel stock was still up 11.4% over the past week, which shows that a single session does not tell the whole story. More broadly, Intel has not provided a specific reason for the wider slide from its high. That leaves investors to weigh other factors, including a major capital raise and the stock’s own stretched recent performance.
Separately, in August, Intel sold $20 billion of new stock at $95 a share. That offering price is below where the stock currently trades. The company said it would use the proceeds for general corporate purposes and to enable growth opportunities. Before the sale, management had said that a very successful Intel might need outside capital for additional investment. Intel now plans more than $20 billion of capital spending in 2026, citing strong customer demand, and management expects 2027 capital spending to be significantly higher. By the company’s account, server CPU demand is far outpacing supply.
That combination — a huge stock sale, ambitious spending plans, and soaring demand — helps explain why investors are focused on both the opportunity and the risk. The capital raise gives Intel more resources to invest, but it also dilutes existing shareholders and signals that the company’s growth ambitions are expensive. If demand remains strong, the spending could pay off. If the cycle turns, the same spending could become a burden.
Is Intel’s Business Getting Worse While It Spends?
No. The fundamentals have actually been improving. Revenue over the trailing twelve months is $57.03 billion, up 7.5%. That compares with a three-year average growth rate of just 1.9%. The operating margin over the same twelve-month period is 7.6%, which is Intel’s best in three years. Over the past three years, the average operating margin was negative 2.0%. So Intel is not deteriorating while it spends. It is growing faster than its recent historical average and generating its strongest operating margin in years.
That improvement gives the bull case something concrete to stand on. A company with accelerating revenue and better profitability is generally in a stronger position to absorb heavy investment. It also means that if the broader market avoids a severe shock, Intel’s earnings power could continue to improve.
How Much Further Could Intel Stock Fall in a Shock?
History offers a sobering guide. During the 2022 inflation shock, Intel fell 52%, while the S&P 500 fell 24%. That means Intel’s decline was more than twice as deep as the index’s drop. On average, Intel has fallen harder than the S&P 500 when shocks hit. That pattern matters because it suggests Intel is not a defensive stock in a market downturn. It is a high-beta name that can suffer disproportionately when sentiment turns.
The recovery timeline is also important. From its low after a shock, Intel has needed a median of about five months to regain its pre-shock high. The slowest recovery, after 2022, took about 39 months and ran through the 2024 shock. That is a long time for investors to wait just to get back to even. It also shows that even if Intel’s business improves, the stock may not immediately recover its lost ground.
So the old downside still applies. Faster growth and the best operating margin in three years give a rebound something to build on. They are not, however, a reason to assume Intel would fall less than it has in past shocks. A stronger business can support a recovery, but it does not erase the stock’s historical tendency to drop harder than the broader market.
The Bottom Line
Intel stock has more than quadrupled over the past year, but it is already about 29% below its 52-week high. The business is improving: revenue is growing faster than its three-year average, and operating margin is at a three-year high. At the same time, the company is spending heavily, raised $20 billion in new stock at $95 a share, and faces a market that has historically punished Intel more severely than the S&P 500 during shocks.
The key takeaway is not that Intel will fall by a specific percentage. It is that the stock’s own history shows a larger downside in market shocks than the index, and there is no fundamental reason yet to size Intel for a shallower fall. Growth and margin improvement may help the eventual rebound, but they do not remove the risk. Investors should weigh the improving business against the stock’s record of sharp drawdowns and slow recoveries.
Short 
American Airlines Faces Fuel-Cost Pressure as Oil Tops $100!American Airlines (AAL) is confronting a fresh fuel-cost headwind as crude oil prices surge back above $100 a barrel, a development that has prompted Barclays to lower its price target on the carrier. The move reflects growing concern that higher energy costs could continue to weigh on airline profitability in the near term, even as the industry tries to maintain momentum on the revenue side.
Despite the reduction in price targets, Barclays analyst Oglenski is urging long-term investors to look beyond short-term swings in fuel prices. In his view, the more important consideration is the strength of revenue growth across the airline group. He argued that the current setup points toward “structurally higher margin potential if energy markets return to prewar levels.” That framing suggests the present pressure should be treated as a temporary drag rather than a permanent problem for the group’s earnings power. In other words, if oil markets eventually normalize, the underlying business could emerge with better margins than the market currently assumes.
For now, however, fuel costs remain significantly higher than they were a year ago. Jet fuel is up 45.4% from $2.34 per gallon in July 2025, and that elevated level continues to squeeze airline profits. There has been some recent monthly improvement, but it has not been enough to erase the broader cost pressure. Fuel remains one of the largest variable expenses for airlines, so even a modest increase in oil prices can have an outsized effect on earnings, cash flow, and margin expectations.
The surge in oil prices is tied in part to the broader geopolitical backdrop. The U.S.-Iran conflict, which erupted after U.S. and Israeli strikes on Iran in February, has settled into a grinding, protracted confrontation with no ceasefire in sight. That ongoing instability has kept markets on edge, particularly because of the risks surrounding the Strait of Hormuz. A large share of the world’s seaborne oil passes through the Strait, so any disruption there can quickly tighten global energy supplies and drive prices higher. Those disruptions remain a persistent risk factor and a key driver behind the elevated jet fuel prices that are currently squeezing airline margins.
Even with those roadblocks, the carriers have shown some resilience on the top line. All three carriers posted revenue growth in fiscal second-quarter 2026, suggesting that demand for air travel remains healthy enough to support higher sales despite the cost pressures. That revenue growth is central to the bullish longer-term argument: if airlines can keep growing revenue while eventually benefiting from lower fuel costs, their earnings power could improve meaningfully.
Oil prices have now topped $100 a barrel for the first time since May. At the time of writing, Brent crude futures were up about 2.5% at $107.20 a barrel, while WTI crude rose 2.44% to $102.49. Those levels underscore how quickly energy markets have repriced geopolitical risk and how difficult it may be for airlines to avoid further cost pressure if the conflict persists.
The bottom line is that American Airlines and its peers are caught between two forces. In the near term, elevated oil and jet fuel prices are pressuring margins and prompting analysts to adjust their targets. Over the longer term, however, Barclays sees a path to structurally stronger margins if energy markets eventually return to prewar conditions. The key question is whether revenue growth can remain strong enough to carry the carriers through the current period of elevated fuel costs.  Long

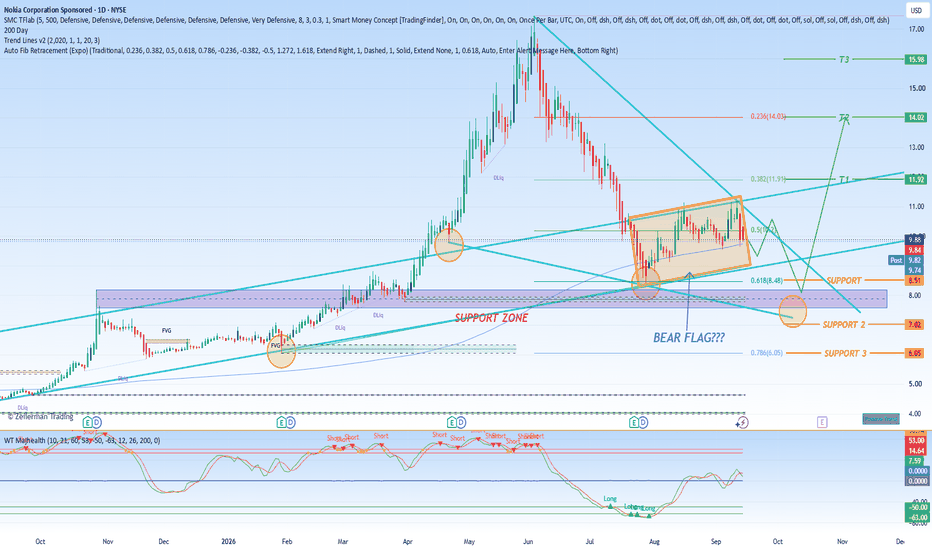
Nokia Stock Rises Overnight as Rosenblatt Calls It!Nokia Corp. (NOK) shares moved higher overnight after Rosenblatt initiated coverage of the telecom equipment maker with a Buy rating and a $15 price target. That target implies roughly 55% upside from the stock’s last closing price, suggesting the firm sees a significant gap between where Nokia trades today and where it could be valued if investors begin to recognize its growing role in AI infrastructure.
The overnight gain followed a difficult regular trading session. Nokia stock had fallen more than 13% during the day, logging its worst single-day decline since June. Despite that sharp selloff, the shares traded more than 1% higher overnight after Rosenblatt’s bullish initiation, indicating that the analyst note helped stabilize sentiment and drew attention to a part of Nokia’s business that may be underappreciated by the market.
Rosenblatt Lauds Nokia’s AI Infrastructure Positioning
Rosenblatt started coverage with a Buy rating and described Nokia as an “AI optical powerhouse” that is currently being valued like a traditional telecom company. In the firm’s view, Nokia is better positioned for the expansion of AI infrastructure than many investors currently recognize. The analyst argues that the market may still be looking at Nokia primarily through the lens of its legacy telecom equipment business, while overlooking the company’s growing importance in optical networking and other infrastructure layers tied to AI data-center buildouts.
A central part of the bull case is Nokia’s growing role in optical networking. Optical networking is critical to moving large amounts of data quickly and efficiently across networks, and it becomes especially important as AI workloads increase demand for bandwidth, speed, and reliable connectivity. Rosenblatt highlighted that Nokia has captured meaningful business in “scale-across,” which is described as one of three optical networking fabrics. The firm considers that segment particularly valuable because equipment that becomes embedded into network designs can be difficult for customers to replace later. Once a vendor’s technology is designed into an infrastructure layer, switching costs can be high, creating a stickier revenue opportunity and a potential competitive advantage.
That dynamic helps explain why Rosenblatt views Nokia’s optical business as strategically important. It is not simply about selling more hardware. It is about becoming part of the underlying architecture that AI-driven networks depend on. If Nokia can deepen its presence in those layers, it may benefit from long-lived deployments and recurring demand as customers expand capacity.
Nokia’s Valuation Could Have Room to Rise
Rosenblatt’s $15 price target assumes that Nokia currently derives roughly one-third of its infrastructure exposure from AI, with the remaining two-thirds coming from telecom. The analyst believes that mix could change substantially as investment in AI infrastructure remains elevated. If AI becomes a larger share of Nokia’s infrastructure business, the company’s earnings and revenue profile could begin to look less like a traditional telecom supplier and more like a key enabler of AI networking.
That shift matters for valuation. Telecom equipment companies often trade at lower multiples because their markets are mature, competition is intense, and growth can be slow. AI infrastructure companies, by contrast, can command higher multiples because investors expect faster growth and greater strategic importance. Rosenblatt’s argument is that Nokia is currently caught in the middle: it has a “powerhouse AI optical franchise” but is still trading at a telco multiple. If the market begins to re-rate the stock toward an AI infrastructure valuation, the firm believes there could be room for more upside.
For that reason, Rosenblatt describes its $15 price target as “potentially conservative.” The firm suggests that Nokia’s consistent shift toward AI could leave room for further revaluation if the company continues to win business and if AI-related demand remains strong. In other words, the target is not necessarily the ceiling. It reflects a view that Nokia’s business mix is changing, but it may not fully capture how much the mix could shift over time.
Why the “Dark Horse” Label Fits
Calling Nokia an AI optical dark horse captures the idea that the company may be overlooked by investors who associate it with traditional telecommunications rather than the AI infrastructure boom. Nokia is not typically grouped with the most prominent AI winners, yet Rosenblatt argues that its optical networking and scale-across capabilities give it a meaningful role in the infrastructure that supports AI. If that role grows, the market may need to reconsider how it values the company.
At the same time, the stock’s recent volatility shows that sentiment remains fragile. The more than 13% regular-session decline before the overnight rebound indicates that investors are still sensitive to news, competitive pressures, and broader market conditions. Rosenblatt’s initiation provides a counterpoint, but it will ultimately be judged by whether Nokia can convert its AI infrastructure positioning into visible financial results.
The Bottom Line
Nokia shares rose overnight after Rosenblatt initiated coverage with a Buy rating and a $15 price target, implying 55% upside. The firm called Nokia an “AI optical powerhouse” trading at a potentially conservative valuation. Rosenblatt sees Nokia benefiting from its optical networking business, especially its scale-across position, and believes the company’s business mix could shift further toward AI as infrastructure demand remains strong. While the market still appears to value Nokia like a traditional telecom company, Rosenblatt argues that its AI optical franchise deserves more credit. The key question now is whether Nokia can prove that shift is durable enough to justify a higher multiple.
 Long
 Long
 Long
 Long
Long